
Latest News
LG Electronics Wins 5 GW Chiller Framework Deal in North America: Data Center Cooling Enters Full-Chain Competition
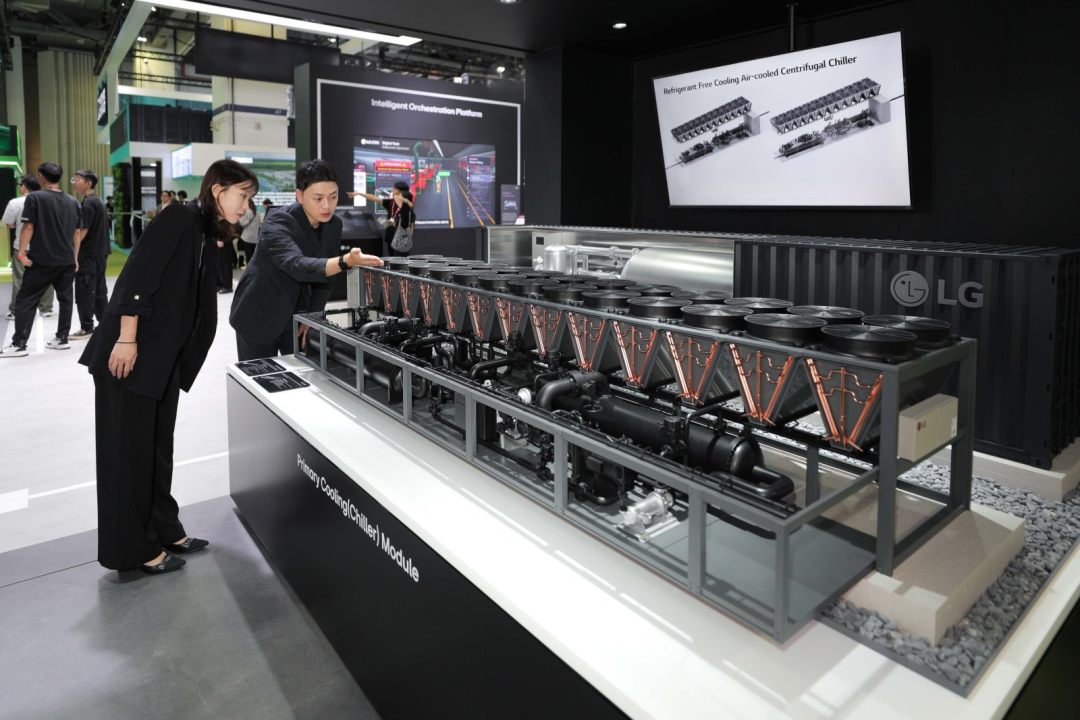
On October 5, LG Electronics announced a long-term chiller supply framework agreement with North American infrastructure platform AIR Control Concepts, covering large AI data center projects in the United States and Canada with a combined capacity of more than 5 GW. This is not a single-site equipment order but a supply arrangement spanning multiple projects and multiple years. The China Energy Storage Alliance (CNESA) notes that rapid GPU power iterations are turning data center cooling from a supporting function into a capacity constraint for AI infrastructure, and thermal management and energy storage are rising in tandem within AIDC infrastructure.
1. What 5 GW Means
Measured against the 50-100 MW IT loads of medium-sized AI data centers in China, 5 GW equates to the cooling capacity of fifty to sixty, or even over a hundred, medium-sized data halls, close to the cooling volume of a core-city compute cluster. The partner, AIR Control Concepts, is a North American infrastructure platform spanning HVAC, electrical, and controls businesses, integrating more than 50 operating companies and over 3,500 technical staff, with long-standing involvement in North America's core data center clusters and top-tier global operators among its customers. A long-term framework agreement with such a platform marks the formal entry of LG chillers into North America's mainstream AI data center supply chain. The order momentum is backed by figures: in the first half of 2026, LG's data center cooling solution orders reached USD 428 million, and the company expects total orders for the year to reach the "billions of dollars" level; the earlier target of KRW 1 trillion (about USD 680 million) in chiller revenue for 2027 is likely to be met ahead of schedule at the current pace.

2. Where the Heat Comes From: Chip Power Pushes Air Cooling to Its Limit
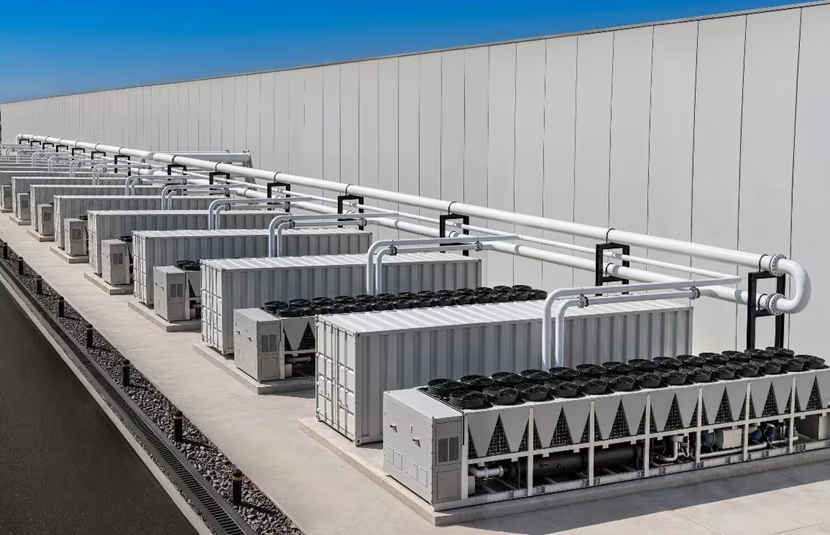
The North American data center cooling market is about USD 9.35 billion in 2026, close to 40% of the global total; within it, the AI thermal management segment is growing at a compound annual rate of about 22%, among the fastest in the data center industry. The root cause is chip power: a single Blackwell-architecture GPU now has a thermal design power (TDP) of 1,000 W, and the next generation could approach 1,400 W. Once rack power density exceeds 200 kW, traditional air cooling can no longer hold, and liquid cooling moves from an option to a must. For liquid cooling to scale, retrofitting campus chiller plants is an unavoidable prerequisite: of the roughly USD 725 billion in combined 2026 capital expenditure by the four major North American cloud providers, about 75% is going to AI infrastructure, and cooling is a hard requirement within it. The division of labor is clear: chillers are the campus-level source of cooling, producing chilled water and ultimately rejecting heat outdoors, while CDUs (coolant distribution units) are the rack-level hub, connecting the chiller's chilled-water loop on one side and server cold plates on the other, precisely controlling the temperature, pressure, and flow of the coolant on the chip side.
3. LG's Three Steps
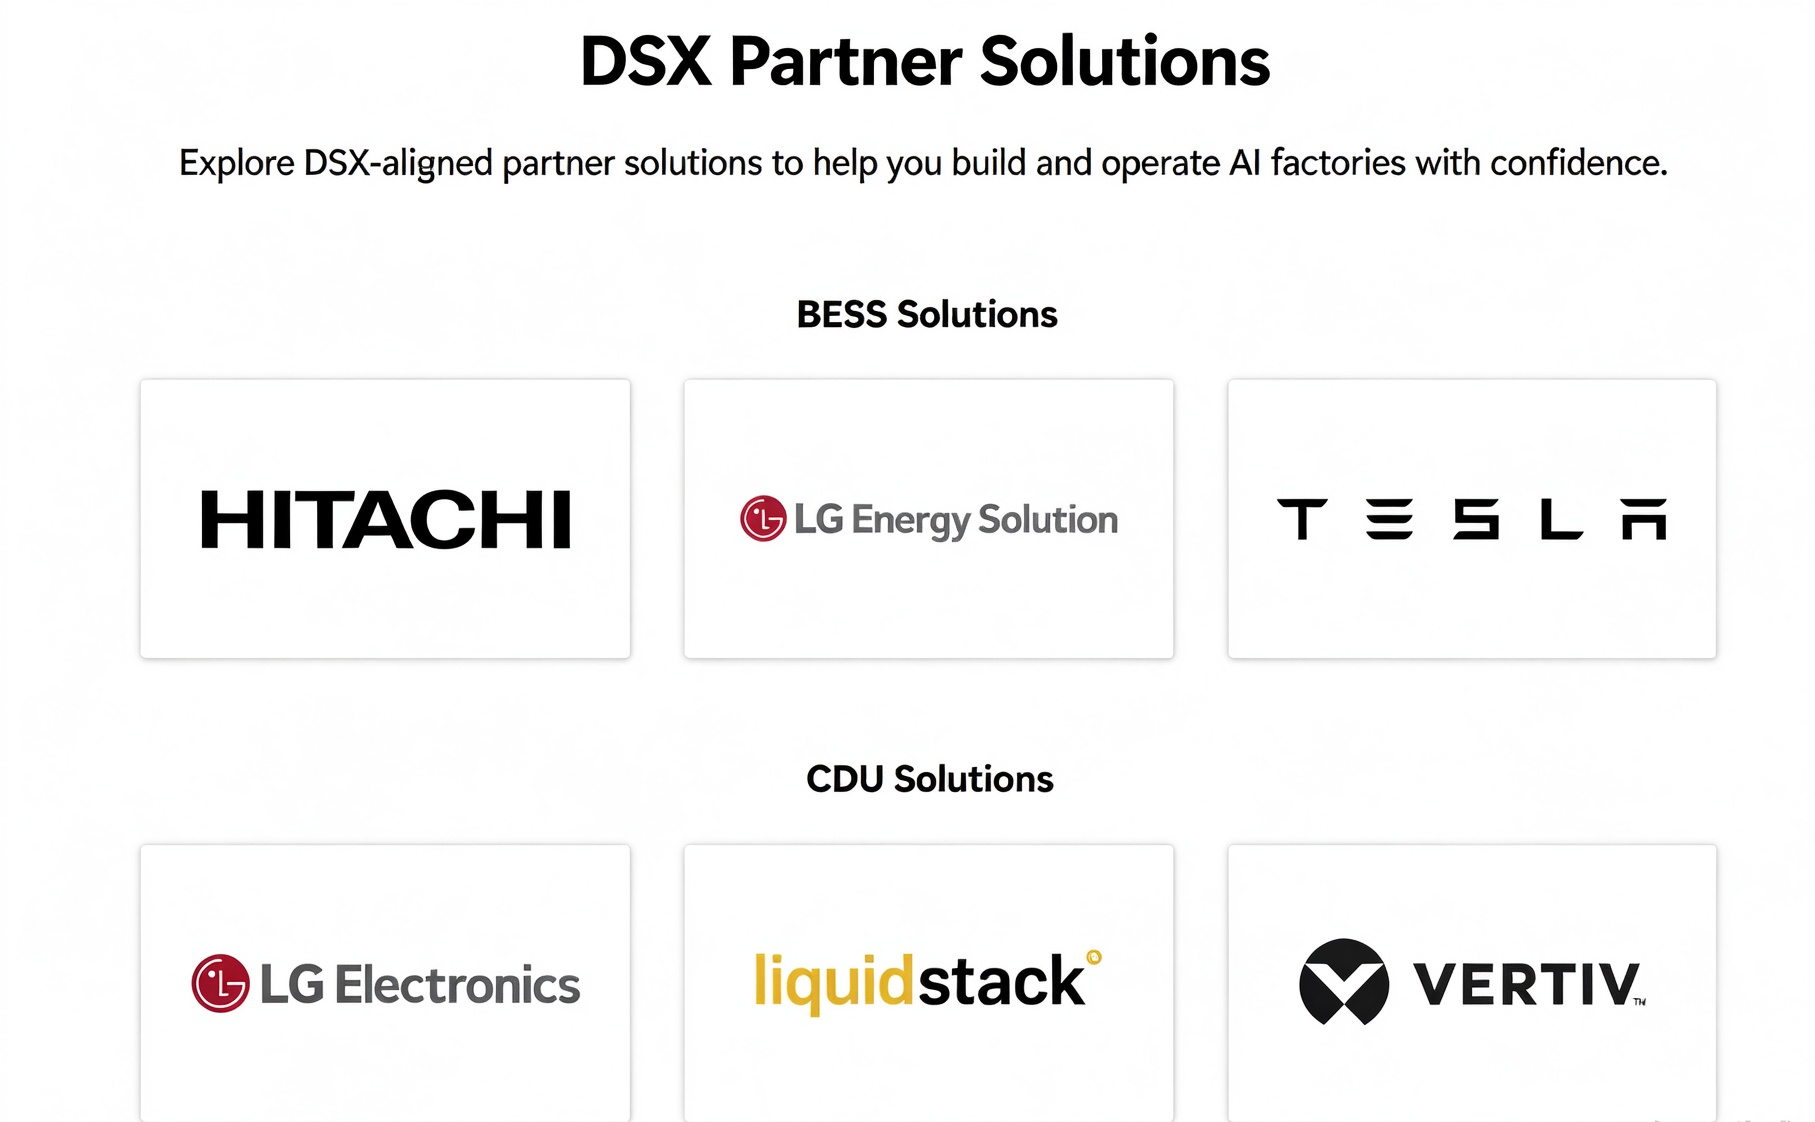
First, aligning with chipmakers' standards. This year, LG's 600 kW, 1 MW, and 2.6 MW CDUs successively passed NVIDIA infrastructure qualification, and the 2.6 MW CDU entered the first batch of the NVIDIA DSX Ready list, effectively NVIDIA's official entry threshold for AI factory infrastructure, granting seamless integration with NVIDIA compute cluster reference architectures. Verification of the 4 MW CDU is underway, and LG has also become a preferred partner for NVIDIA power and cooling solutions.
Second, moving capacity forward. On October 1, LG announced a new chiller and CDU production base in Virginia, USA, alongside capacity expansion at its Changwon and Pyeongtaek plants in Korea, forming a three-base layout across the US and Korea to shorten delivery cycles for North American projects and meet local supply chain requirements.
Third, expanding its footprint. Beyond North America, data center cooling projects in the Middle East and Indonesia are advancing in parallel; drawing on synergies across the group's electronics, HVAC, and energy divisions, LG aims to move from a single-product supplier to an end-to-end data center thermal management solution provider.
4. The Logic of the Cooling Business Has Changed: From Support to Capacity (CNESA Observation)
A few years ago, data center cooling was a supporting business where vendors competed on energy efficiency ratio, price, and delivery time. That logic is being rewritten: whether a vendor can keep pace with GPU power iterations, align with chipmakers' standards, and withstand heat densities of several hundred kilowatts per rack is now the ticket to entry. Customers no longer ask for single products but for complete solutions from chip cold plates to campus chiller plants, making full-chain integration the dividing line. Notably, LG appears in both the energy storage and CDU columns of the NVIDIA DSX Ready partner list: power supply and cooling are equally hard requirements for high-density AIDC, and cooling and energy storage are both becoming capacity constraints in AI infrastructure. Only vendors whose capacity and service networks span the global market can capture this wave of demand.
Sign up for our free monthly newsletter to stay informed about the Chinese energy storage market.