
Latest News
China’s 15th Five-Year Implementation Plan for New-Type Energy Storage
By 2030, China’s new-type energy storage sector will complete its transition from large-scale capacity build-out to market-driven commercial operation. The national target sets the installed capacity of new-type energy storage at 300 GW, with an average storage duration of roughly 3 hours. This milestone is designed to enable deeper integration and interactive coordination across generation, grid, load and storage segments within the power system, unlock the multi-dimensional value of energy storage, and underpin the construction of a new-type power system.
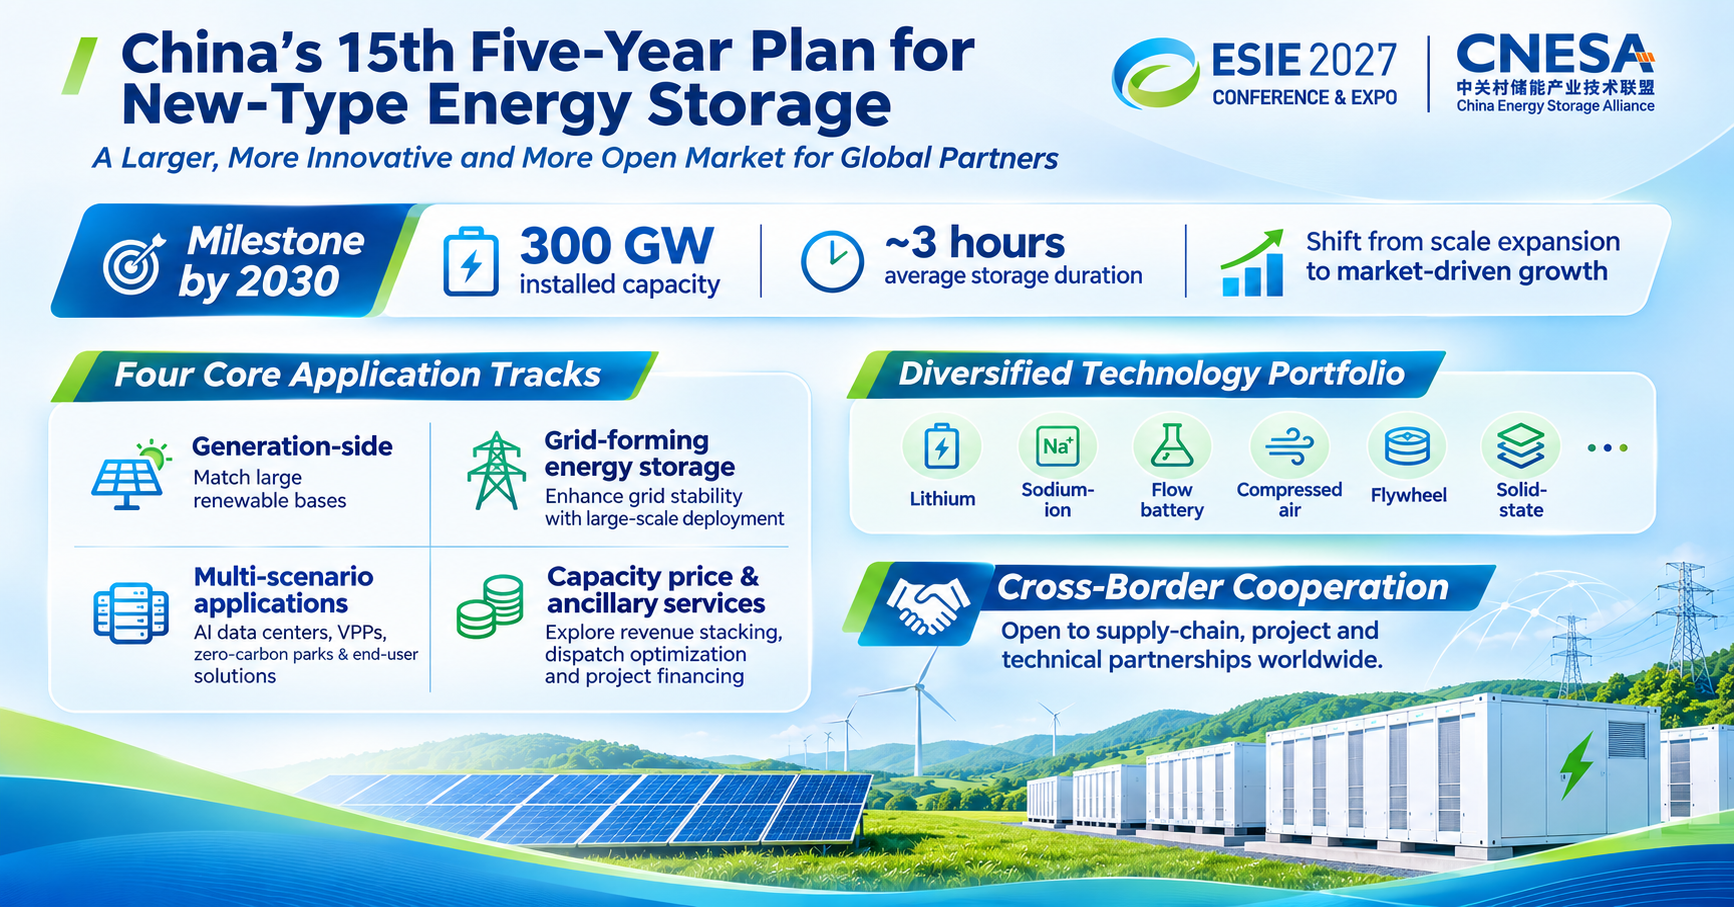
Overarching Guideline & Foundational Principles
The core development guideline is to foster new strategic emerging industries and vigorously advance new-type energy storage deployment. The plan is guided by four foundational principles:
1. Scientific planning and optimized allocation: Deploy storage resources rationally across regions to match local demand.
2. Technology leadership and innovation-driven growth: Prioritise R&D and commercialisation of diversified storage technologies.
3. Standardised governance with safety and efficiency: Establish robust regulatory frameworks to secure reliable, safe operation.
4. Market-led, orderly development: Let market mechanisms steer project rollout while avoiding unregulated overexpansion.
Six Core Development Objectives
1. More rational scale and spatial layout: The plan defines quantified development targets for the 15th Five-Year period. It guides new storage assets toward regions with pressing needs for peak-load relief, renewable integration and power system stability.
2. Diversified technological innovation: China will consolidate its existing strengths in lithium-ion battery storage, scale up sodium-ion and flow battery solutions, and push compressed-air and liquid-air storage toward full commercial maturity.
3. Well-ordered industry governance: Standardised management will cover the full lifecycle of new storage projects, including planning approval, grid connection scheduling and ongoing monitoring.
4. Rich and expanded application scenarios: Beyond traditional power-source and grid-side deployment, the policy strongly supports storage adoption in green direct-wire supply, zero-carbon industrial parks, virtual power plants and other innovative use cases.
5. Improved market frameworks: The reform agenda targets refined electricity market rules and pricing systems, enabling storage assets to fairly participate in spot, auxiliary service and capacity markets and capture their full economic value.
6. Resilient and robust industrial ecosystem: Policy support will strengthen the whole supply chain, reinforce safety standards, and facilitate the healthy, large-scale expansion of the domestic new energy storage industry.
Three Pillars of Deployment: Eleven Application Scenarios
1. Generation-side new-type energy storage
By 2030, new energy bases will be equipped with approximately 50 GW–60 GW of supporting new-type energy storage. Both centralised and distributed renewable farms, alongside conventional power plants, will be encouraged to deploy storage as required. Key functions:
· Support the delivery and grid integration of large-scale renewable bases
· Boost local consumption of distributed renewables
· Strengthen the market participation capability of renewable assets
· Improve the flexible regulation capacity of conventional generation
2. Grid-side new-type energy storage
By 2030, standalone grid-side storage capable of peak-load relief will reach around 142 GW. This segment will support the coordinated operation of microgrids and pioneer novel grid storage configurations. Key functions:
· Enhance the overall regulation capability of the power system
· Reinforce regional power supply security
· Enable the build-out of advanced distribution networks
· Substitute for costly traditional power grid infrastructure investment
3. Multi-scenario innovative energy storage
The plan endorses storage deployment in integrated source-grid-load-storage projects, green direct supply lines, smart microgrids, high-renewable distribution networks and virtual power plants. It accelerates the development of zero-carbon parks, cross-sector coupling and non-electrical energy utilisation. Key functions:
· Enable end-users to operate low-carbon, green power loads
· Co-evolve alongside emerging power market models
· Drive cross-industry integration and new business formats
Five Priorities for Technological Innovation
1. Advance new energy storage technologies: Upgrade lithium-ion battery systems, roll out sodium-ion storage, and push compressed air, liquid air and flywheel storage toward commercialisation. Pilot schemes will cover supercapacitors, supercritical carbon dioxide, liquid hydrogen, gravity storage, molten-salt heat storage, solid-state batteries, heat pumps, thermal storage and hydrogen storage.
2. Develop grid-optimised storage: Centred on real-world use cases, authorities will roll out grid-adapted storage portfolios, refine planning methodologies and unify equipment technical standards.
3. Promote mixed-duration storage solutions: Develop safe, long-lifetime short-duration storage as well as large-capacity long-duration storage. Coordinate the matched deployment of electrochemical, thermal and hydrogen storage assets.
4. Achieve breakthroughs in core equipment: Build a complete domestic supply chain for storage hardware and lift independent R&D capacity for critical technical equipment.
5. Solve shared foundational technical challenges: Improve high-efficiency control and scheduling algorithms, explore the integration of energy storage and artificial intelligence, and advance digital and intelligent transformation.
Ten Supporting Policy Measures
1. Boost innovation with multi-pronged incentives: Refine the supporting policy system for storage technologies, accelerate pilot demonstration and real-world deployment, and cultivate specialised technical talent.
2. Strengthen whole-lifecycle project management: Roll out standardised specifications, tighten oversight for standalone grid-side storage, and enforce local regulatory responsibilities.
3. Elevate storage scheduling and operational competence: Improve coordination between grid dispatch and storage resources, optimise synergistic operation of storage paired with wind, solar and conventional generation.
4. Build up the national standard system: Accelerate the formulation and revision of standards covering materials, equipment, construction, operation and safety, while aligning with international norms.
5. Carry out continuous industry supervision: Include new storage within full-cycle market oversight, strengthen compliance inspections and regulate revenue settlement.
6. Enforce rigorous safety management: Implement a full-coverage safety governance system, clarify the primary responsibility of project owners, and carry out end-to-end risk control.
7. Enable storage participation in electricity markets: Remove institutional barriers for storage to trade in auxiliary service, capacity and spot markets.
8. Complete the pricing mechanism framework: Improve capacity pricing, time-of-use tariffs and other compensation rules so that storage can fully reflect its market value.
9. Support sound industrial development: Consolidate domestic manufacturing and R&D capacity, optimise the industrial layout and structure, and avoid disorderly low-quality expansion.
10. Deepen international exchange and collaboration: Establish stable bilateral and multilateral communication channels, create mutually beneficial cooperation frameworks, and support domestic enterprises to explore overseas markets.
Closing Outlook
This implementation plan marks a clear, forward-looking policy signal for global energy stakeholders. China will continue to open its new-type energy storage sector to international partners, welcoming collaboration on project development, supply chain cooperation, technology exchange and joint market exploration to advance the global clean energy transition together.
Global Energy Storage Alliance Initiative Launched at COP31
A new international initiative to strengthen cooperation on energy storage was launched today at the China Pavilion at COP31, bringing together leading companies, industry associations and institutions from China and around the world to advance the development and deployment of energy storage.
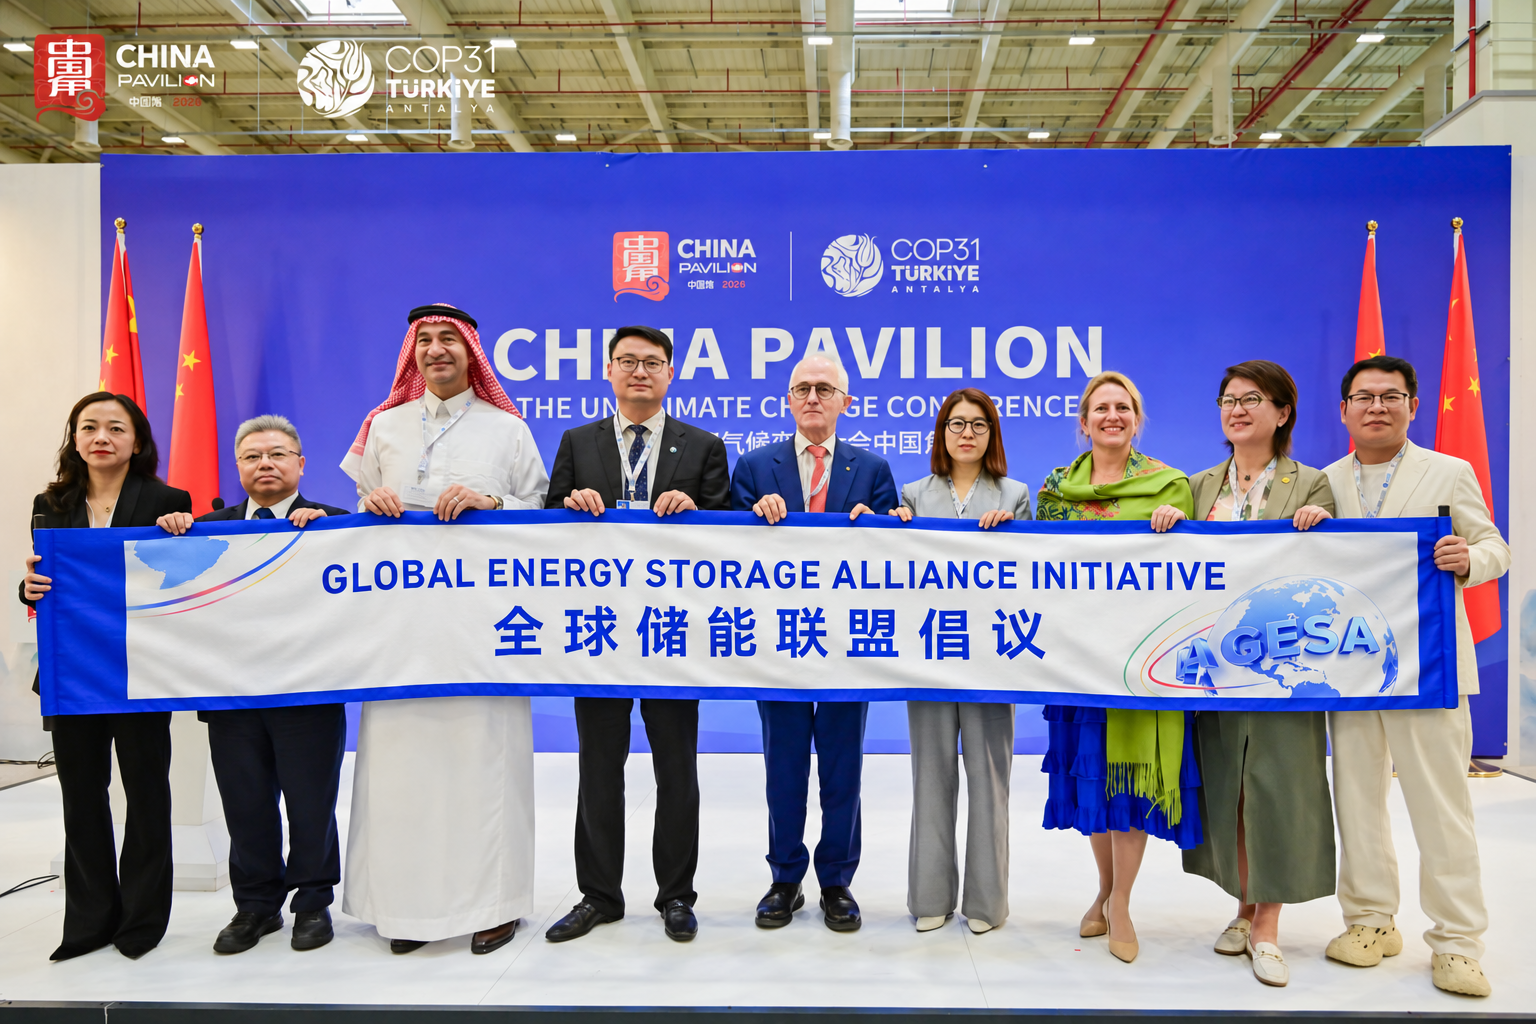
The Global Energy Storage Alliance (GESA) Initiative was jointly launched by the China Energy Storage Alliance (CNESA), the China Renewable Energy Engineering Institute (CREEI), and China Southern Power Grid Energy Storage Co., Ltd., alongside leading domestic and international industry partners. A number of international institutions and industry organisations have expressed interest in participating.
The launch took place during the side event “Digital-Intelligent Innovation for Green Electricity: Building a New Power System & New Practices for Global Energy Transition”, held at the China Pavilion during the 31st Conference of the Parties to the United Nations Framework Convention on Climate Change (COP31). The event brought together senior representatives of governments and international organisations, including Li Gao, Vice Minister of Ecology and Environment of China; Xiong Minfeng, Deputy Director-General of the Department of International Cooperation of the National Energy Administration of China; Francesco La Camera, Director-General of the International Renewable Energy Agency (IRENA); and Selwin Hart, UN Assistant Secretary-General and Special Adviser to the Secretary-General on Climate Action and a Just Transition.
A platform for global collaboration
The launch comes at a time when energy storage is gaining recognition as an increasingly important component of the global energy transition. As countries seek to expand renewable energy while maintaining secure and reliable power systems, energy storage is becoming central to efforts to enhance system flexibility, improve the integration of renewables and strengthen energy security. Yet significant barriers remain, underscoring the need for greater international cooperation.
Speaking at the launch event, Dr. Jiang Hao, Assistant to the Director-General, Lead Scientist and Director of the International Cooperation Department of CREEI, said that as the global energy transition gathers pace, an increasing number of countries and regions are recognising the value of energy storage and making it a priority on their sustainable development agendas. However, amid a complex and evolving international landscape and rising energy security concerns, the global energy storage sector continues to face significant challenges, underscoring the need for stronger international dialogue and cooperation. Against this backdrop, the establishment of GESA was proposed, with a mission to advance the large-scale, diversified and innovation-driven development of energy storage worldwide. Through enhanced international engagement and collaboration, GESA aims to help establish energy storage as core infrastructure for new power systems and make a positive contribution to the global energy transition and efforts to address climate change.
Liu Wei, Secretary-General of CNESA, outlined GESA’s six priority areas: facilitating global dialogue; developing global energy storage databases and standard systems; advancing research, development and deployment of frontier technologies; improving market mechanisms and fostering business model innovation; strengthening supply chain coordination and promoting global trade; and facilitating investment, financing and project cooperation. She emphasised that GESA would serve as an open, inclusive and pragmatic global platform, bringing together stakeholders across the industry on the basis of fairness, mutual benefit and practical cooperation. GESA aims to turn shared aspirations into concerted action and advance global energy storage cooperation towards more coordinated, organised and structured development.
Addressing barriers to energy storage deployment
The launch also highlighted the practical challenges that need to be addressed to accelerate energy storage deployment across different markets.
Drawing on China Southern Power Grid’s experience, Sun Liqun, Deputy General Manager of China Southern Power Grid Energy Storage Co., Ltd., highlighted that energy storage had evolved from a supporting resource for renewable energy into an indispensable component of new power systems. He noted that the sector still faces key challenges, including inadequate mechanisms to recognise and remunerate the value of short- and long-duration storage, fragmented technical standards and regulatory frameworks across countries, and barriers to project development, financing and viable business models in emerging economies. These challenges underscore the importance and timeliness of establishing GESA.
Supporting the global energy and climate agenda
The launch at COP31 places energy storage more firmly within the international dialogue on energy and climate action. By providing a platform for governments, businesses, research institutions and industry organisations to exchange experience and strengthen cooperation, GESA seeks to advance recognition of energy storage’s contribution to higher renewable energy utilisation, more resilient power systems, energy security and sustainable economic development.
GESA invites energy storage industry associations, companies, research institutions, international organisations and other stakeholders worldwide to take part in the initiative. Through collective engagement and practical cooperation, it aims to unlock the transformative potential of energy storage and support progress towards global energy goals, climate objectives and the United Nations Sustainable Development Goals.
GESA welcomes participation from energy storage industry associations, businesses, research institutions, international organisations and other stakeholders worldwide. By bringing these partners together, the initiative seeks to unlock the transformative potential of energy storage and contribute to the achievement of global energy goals, climate action and the United Nations Sustainable Development Goals (SDGs).
Representatives from Acwa, China Energy Storage Alliance, China Renewable Energy Engineering Institute, China Southern Power Grid Energy Storage Co., Ltd., EVE Energy, International Hydropower Association, Long Duration Energy Storage Council, Trina Solar, World Resources Institute and other leading institutions gathered to witness the unveiling of the initiative.
Global Energy Storage Alliance Initiative
We, the co-initiators of the Global Energy Storage Alliance (GESA),
Reaffirming the commitment to the United Nations 2030 Agenda for Sustainable Development, in particular Goal 7, namely ensuring access to affordable, reliable, sustainable, and modern energy for all together with the long-term goals established under the Paris Agreement;
Recognising that energy storage is not only a pivotal technology for power systems with high penetrations of renewable energy, but also a core and critical infrastructure element for enhancing system flexibility, reliability, resilience, and cost-effectiveness; and further acknowledging its increasing strategic value in safeguarding national energy security and mitigating geopolitical and supply chain disruptions;
Recognising the irreplaceable nature of international cooperation in the field of energy storage; and emphasising that only through collaboration can we advance technological innovation, consolidate mutual recognition of standards, optimise industrial frameworks, facilitate investment, develop the needed workforce and skills, and accelerate project development to promote energy storage from fragmented implementation to global deployment, thereby realising our collective goal of building a modern energy system;
To this end, we hereby call for the establishment of the Global Energy Storage Alliance (GESA), dedicated to the following vision through pragmatic action in key areas, based on transparency, inclusiveness, technology neutrality, market orientation, sustainability, and respect for different regulatory models:
I. Vision
GESA is mandated to promote the large-scale, technology-diversified, and innovation-driven development of global energy storage. It seeks to foster a global energy storage landscape underpinned by sound markets, a broad range of technologies, industrial collaboration, mutually recognised standards, open, fair, and non-discriminatory international trade, and investment facilitation. Through these efforts, GESA aims to promote energy storage as a core infrastructure of future power systems, providing critical support for climate action, energy transition, and sustainable development.
II. Key Areas of Action
Cultivating Global Dialogue Platforms
Leveraging flagship events including the conferences and expositions of its members across the globe, GESA will facilitate engagement at different levels through both online and offline modalities. Via thematic forums, roundtables, field missions, and expert consultations, GESA will bridge communication between governments, international organisations, research institutions, and industry players. This platform is dedicated to exchanging experiences and best practices regarding supportive policies, market mechanisms, and incentive frameworks, thereby establishing an inclusive, open, and multi-dimensional platform for high-level dialogue.
Building Global Databases and Standard Systems
In coordination with regional industry organisations, GESA will develop voluntary and transparent mechanisms for collecting and sharing aggregated information on energy storage projects, policies, technologies, markets, financing and standards, which will support evidence-based policymaking, investment and market development. Furthermore, GESA will engage with international standards organizations to promote the alignment and mutual recognition of key technical standards.
Strengthening R&D and Dissemination of Frontier Technologies
GESA will reinforce global technological cooperation through joint R&D and demonstration, promoting the commercialisation of diverse technologies—including long-duration, medium-to-short duration, and high-frequency storage. Simultaneously, GESA will foster international R&D collaboration on next-generation storage innovations. GESA will uphold high standard of safety throughout the energy storage life cycle and facilitate knowledge sharing and practices exchange with regard to safety and risk management. By aligning technological deployment with local resource endowments and energy demands, GESA will provide essential support for building modern power systems tailored to national circumstances.
Refining Market Mechanisms and Business Model Innovation
GESA will establish a global platform for dialogue and exchange in market mechanism to ensure that energy storage can participate fairly in various markets and realise its full economic value based on the services it provides in enhancing flexibility, ensuring power supply and strengthening system resilience. In mature markets, focus will remain on optimising power market rules and scaling successful models of energy trading and ancillary services; in emerging markets, GESA will advocate for market designs that reflect the flexibility, regulation capability and value-added contributions of energy storage. We also encourage diversified applications in a wide range of scenarios such as direct green power supply, data centres, and virtual power plants (VPPs) to unlock the multi-faceted commercial potential of energy storage.
Enhancing Supply Chain Coordination and Global Trade
GESA supports to build stable, reliable, resilient and diversified global supply chains of energy storage. Coordinated and internationally connected supply chains are essential to the resilience of global energy storage industries. GESA supports cooperation among regions with complementary industrial strengths, and open, fair and non-discriminatory international trade. Recognising the importance of circular economy and sustainable value chains, GESA will promote circular economy principles across all energy storage technologies.
Facilitating Investment, Financing, and Project Cooperation
GESA is committed to fostering an open, stable, investment-friendly and non-discriminatory investment environment. We encourage increased capital allocation from public, private, and multilateral financial institutions. GESA places emphasis on providing technical assistance, capacity-building, and financial de-risking for projects in developing nations and emerging economies, ensuring the accelerated deployment of energy storage technologies on a global scale.
Energy storage is not merely a strategic contingency for the energy transition but an indispensable cornerstone of it. We call upon all stakeholders dedicated to the advancement of this sector to join GESA. Through a framework defined by synergy, inclusivity, and an action-oriented mandate, we shall harness the full transformative capacity of energy storage to fortify global energy security and realise the goal set in the Paris Agreement and the UN Sustainable Development Agenda.
List of interested stakeholders of GESA
(The order of listing does not imply any ranking)
I. Co-initiators of the GESA Initiative
Acwa
Beijing HyperStrong Technology Co., Ltd.
BYD Energy Storage
CGN Energy International Holdings Co., Limited
China Energy Storage Alliance
China Huadian Overseas Investment Co., Ltd
China Renewable Energy Engineering Institute
China Southern Power Grid Energy Storage Co., Ltd.
Contemporary Amperex Technology Co. Limited
Cornex New Energy Co., Ltd
CRRC Zhuzhou Institute Co., Ltd.
Envision Energy
EVE Energy Co., Ltd.
FoxESS Co., Ltd
Huaneng Clean Energy Research Institute
Institute of Engineering Thermophysics, Chinese Academy of Sciences
Nanjing Phoenix Contact Co., Ltd
POWERCHINA International Group Limited
Rept Battero Energy Co., Ltd.
Robestec
Shuangdeng Group Co., Ltd
SPIC Energy Science and Technology Research Institute
Sungrow Power Supply Co., Ltd.
Trina Energy Storage Solutions (Jiangsu) Co., Ltd.
Xiamen Hithium Energy Storage Technology Co., Ltd
Xiamen Kehua Digital Energy Tech Co., Ltd.
Zhongchu Guoneng (Beijing) Technology Co., Ltd.
II. Organizations Interested in Exploring the GESA Initiative
Energy Storage Canada
Energy Storage Europe
Hungarian Battery Association
International Hydropower Association
Long Duration Energy Storage Council
Upcell Alliance
World Resources Institute
Organized by China Energy Storage Alliance (CNESA), ESIE 2027 is a leading international platform connecting global energy storage stakeholders with China's innovative technologies and supply chain. Bringing together industry leaders, technology providers, investors and buyers, ESIE 2027 fosters technological innovation, business partnerships and international collaboration to accelerate the global energy transition.
AI Innovation Empowers New Energy Storage Scenarios Salon Successfully Held
On the afternoon of November 5, the AI Innovation Empowers New Energy Storage Scenarios Salon was held at the Zhongguancun (Haidian) AI Digital Energy Industrial Park.
Guided by the Zhongguancun Science City Administrative Committee, the event was jointly hosted by the China Energy Storage Alliance (CNESA), Zhongguancun (Haidian) AI Digital Energy Industrial Park and Zhongguancun Cloud Computing Industry Alliance (CCIA). Under the theme Digital-Intelligence Integrates with Energy Storage · Smartly Usher in a New Frontier, the salon focused on the integrated deployment of AI technologies in energy scenarios. It gathered representatives from AI large model firms, cloud computing players, research institutes and leading energy storage enterprises for in-depth discussions on AI-enabled innovation in power and energy scenarios, technological exploration, benchmark use cases and business models. The event facilitated technical exchanges, idea sharing, precise matching of supply and demand across the industrial chain, and collaborative innovation. More than 60 delegates from AI large model, cloud computing, research and energy storage enterprises attended the salon.
In the opening session, the Zhongguancun (Haidian) AI Digital Energy Industrial Park delivered a keynote presentation titled Source of Innovation: Building a New Aggregated Tech Industrial Ecosystem — Sharing on Haikai Holdings’ Industrial Layout and Ecosystem Value. The presentation covered Haikai Holdings’ industrial deployment, the park’s industrial ecosystem and the background of this salon.
During the keynote segment, Zhang Qing, Expert of CSG New Power System (Beijing) Research Institute Co., Ltd.; Yan Yufan, Architect of Hangzhou Eagle Cloud Technology Co., Ltd.; Liu Ming, Chief Algorithm Engineer of ZTE Digital Energy; Zhao Cong, Senior Solution Manager of CLOU Energy Storage, Midea Group; and Shang Wenxiao, Technical Lead of TELD Beijing Branch, gave presentations in sequence. They explored topics including AI practices within new power systems, security governance frameworks for AI Agents in power and energy systems, AI applications for commercial & industrial energy storage, AIDC compute-power coordination energy storage solutions, and how AI boosts efficiency for integrated PV-storage-charging-discharging scenarios.
In the panel discussion, participating guests exchanged views thoroughly on the deployment forms and application progress of power large models, joint overseas expansion by domestic enterprises for the global compute-power coordination market, rollout and cybersecurity risk management of large language models in the power sector, and the balance between component technical performance and cost requirements for energy storage applications.
Panel Discussion & Exchange | Tour of the Park Exhibition Hall
Rooted in Haidian’s industrial ecosystem for AI and digital energy, the event took AI-enabled energy storage as its main thread. It targeted frontline pain points across new power systems, C&I energy storage, AIDC compute-power coordination, PV-storage-charge-discharge integration and AI security governance. It broke down barriers between artificial intelligence and the energy storage industry, linking grid operators, equipment vendors, system integrators, asset operators and capital providers to drive full-lifecycle value for energy storage via digital and intelligent technologies.
The China Energy Storage Alliance (CNESA) will continue to serve as an industrial platform hub, building cross-border cooperation channels connecting AI and energy storage, pooling resources from industry, academia, research and end users, and supporting the commercialization and high-quality growth of the AI + energy storage industry.
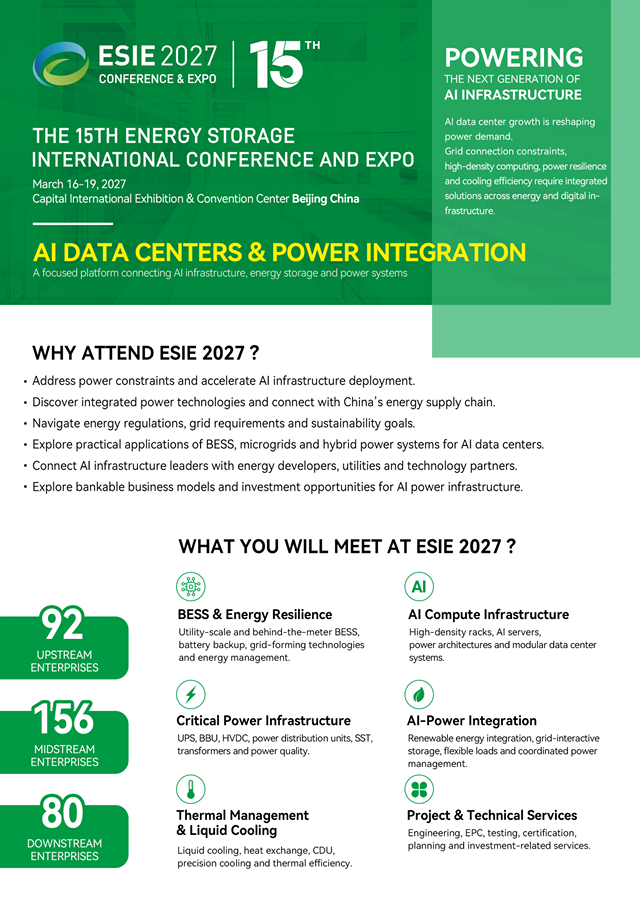
The 15th Energy Storage International Conference and Expo (ESIE 2027), co-hosted by the China Energy Storage Alliance (CNESA), China Energy Research Society (CERS) and the Institute of Engineering Thermophysics, Chinese Academy of Sciences (IET, CAS), will take place from March 16 to 19, 2027, at the Capital International Exhibition & Convention Center in Beijing.
For the first time, ESIE 2027 will launch a dedicated AIDC Compute-Power Coordination Exhibition Zone, showcasing cutting-edge technologies and products including high-rate energy storage for BBU, Solid-State Transformers (SST), HVDC, immersion liquid cooling, cold-plate liquid cooling, direct green power supply, generation-grid-load-storage integration, and coordinated dispatch systems for computing and energy storage. It will also feature themed forums, new product launches and supply-demand matching sessions. Bringing together core buyers including the three major telecom operators, cloud vendors and IDC operators, the expo will continue to serve as a cross-industry platform for computing infrastructure and energy storage, advancing the high-quality development of the energy storage sector.
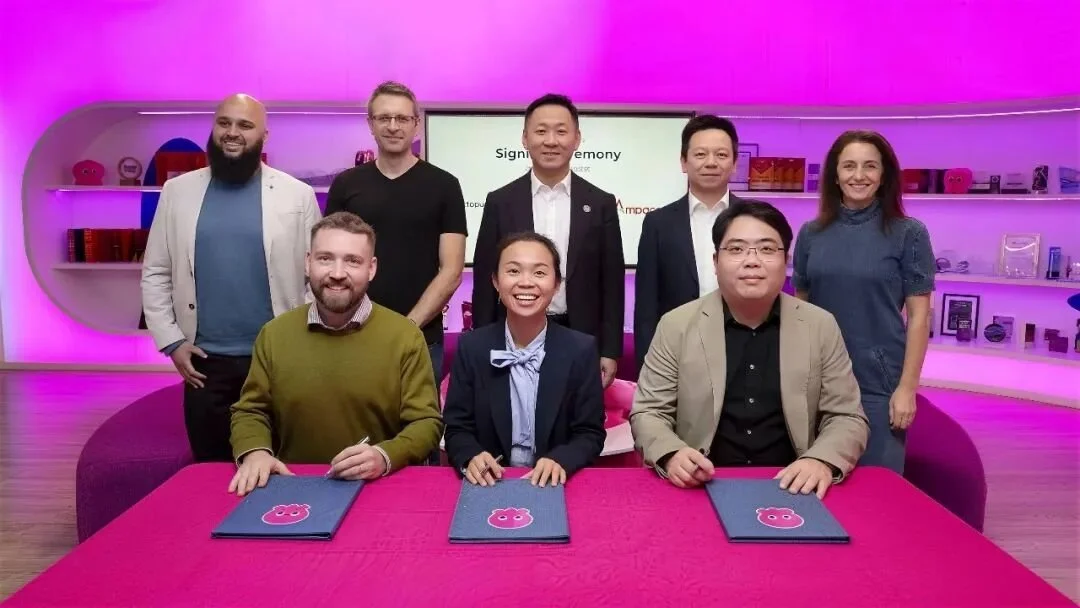
Octopus Energy, Ampace and CATL Sign MoU on Smart Home Energy Storage in Europe
Octopus Energy, Ampace and CATL have signed a memorandum of understanding (MoU) to explore smart residential energy storage solutions for European markets.
The agreement brings together battery technology, energy management software and customer distribution channels, with an initial focus on the UK, France and Spain. It extends the relationship between Octopus Energy and CATL into household energy, following their European heavy-duty truck battery-swapping collaboration announced in June 2026.
Octopus Energy, Ampace and CATL Sign MoU on Smart Home Energy Storage in Europe
Combining Battery Hardware and Smart Energy Services
Under the proposed collaboration, Ampace will develop and manufacture battery cells, battery management systems (BMS) and energy storage systems, supported by CATL’s technology and supply chain capabilities.
Octopus Energy will contribute its European customer channels, smart dynamic-tariff algorithms and virtual power plant (VPP) integration services.
The partners aim to combine these capabilities to accelerate the deployment of residential batteries and enable households to manage electricity use more efficiently.
Octopus Energy, Ampace and CATL Sign MoU on Smart Home Energy Storage in Europe
Connecting Home Batteries with Solar, EVs and the Grid
The collaboration will explore how home energy storage can work alongside rooftop solar, smart electric vehicle charging, vehicle-to-grid (V2G) technology and virtual power plants.
By connecting these technologies, the partners aim to turn household batteries into flexible, dispatchable resources. Coordinated charging and discharging could help households reduce electricity costs while supporting grid flexibility and resilience.
Building on their cooperation in commercial transport, the companies also plan to explore co-branded home energy solutions for European households.
Source: CATL.
World’s Largest Liquid Air Energy Storage Project Connects to Grid in China
A 60 MW liquid air energy storage (LAES) demonstration project developed by China Green Development Investment Group connected to the grid and began generating electricity in Golmud, Qinghai Province, on October 30, 2026.
Described as the world’s largest LAES project, the installation marks a milestone in scaling up the technology and developing a domestic supply chain for long-duration energy storage in China.
The project is part of the National Energy Administration’s new energy storage pilot demonstration program and has been designated a first-of-its-kind major technical equipment project in the energy sector.
World’s Largest Liquid Air Energy Storage Project Connects to Grid in China
Cryogenic Storage Using Air
The system uses a cryogenic liquefaction process operating at approximately −194°C, with air serving as the working medium. Energy is stored by liquefying air and holding it in insulated tanks at atmospheric pressure, then recovered through a power generation process.
Unlike storage technologies that require specific geological formations, LAES offers flexibility in site selection. Its potential for large-scale deployment, long storage durations and long equipment lifetimes makes it a promising option for integrating variable renewable generation.
The Golmud project is designed to store electricity during off-peak periods and deliver it during peak demand, helping address fluctuations in wind and solar output and improve local renewable energy utilization.
Domestic Equipment and Integrated Controls
According to the project announcement, the installation incorporates independently developed intellectual property and uses entirely domestically manufactured equipment. Its power rating and energy storage capacity are reported to be the largest in the global LAES sector.
Development involved collaboration across the supply chain to deliver key equipment, including large centrifugal compressors and liquid expanders. An air purification system removes moisture, carbon dioxide and other impurities to support reliable operation of the cryogenic process.
The plant also integrates compressor and expander controls, process controls, safety instrumentation and gas detection systems. These systems coordinate the compression, liquefaction, storage and power generation stages, while managing interactions between cooling, heating, electricity and air flows.
Advancing Long-Duration Energy Storage
Grid connection represents an important step in moving LAES from smaller demonstration systems toward utility-scale deployment.
The project is expected to provide practical experience for future installations, support the development of China’s long-duration energy storage supply chain, and help integrate higher shares of renewable electricity into the power system.
Source: Project information published by the Golmud Municipal Government.
China’s Highest-Power Single Flywheel Enters Operation at Huaneng’s Lanzhou Plant
A flywheel energy storage project featuring what is reported to be China’s highest-power individual flywheel entered grid-connected operation at Huaneng’s Lanzhou thermal power plant on November 6, 2026. The project uses a dual-flywheel configuration to improve the generating unit’s frequency regulation performance and support grid stability in northwestern China.
The system combines a 5 MW high-power flywheel with a 0.5 MW inertia flywheel. The two units provide complementary, tiered responses: the larger flywheel addresses significant grid frequency deviations, while the smaller unit manages routine, lower-amplitude fluctuations.
According to the report, the thermal generating unit equipped with the dual-flywheel system can respond to grid frequency regulation requests in less than 100 milliseconds, with regulation accuracy exceeding 99.5%.
A 5 MW Flywheel for Fast Frequency Regulation
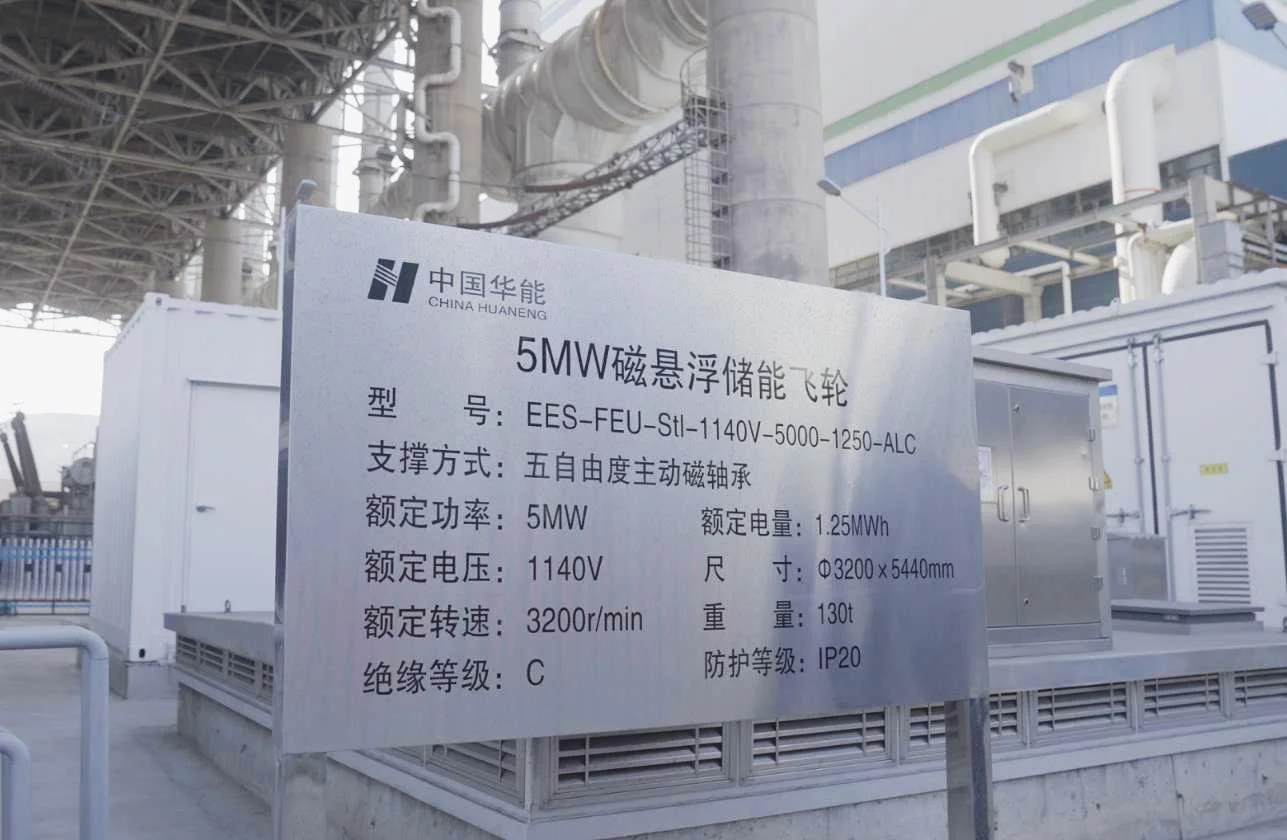
The flywheel energy storage project at Huaneng’s Lanzhou thermal power plant. Photo: China Huaneng.
The 5 MW flywheel is reported to have the highest power rating of any individual flywheel currently operating in China. Its reported specifications include a power ramp rate of 5 MW per second, an energy storage capacity of 1,250 kWh, charge-discharge efficiency above 85%, and a cycle life of up to 10 million cycles.
Flywheel energy storage stores electricity as rotational kinetic energy in a high-speed rotor. During charging, electricity accelerates the rotor; during discharge, the stored kinetic energy is converted back into electricity. Rapid charging and discharging make the technology suitable for applications requiring fast, frequent power adjustments.
Supporting Grid Stability in Northwestern China
The project was led by Huaneng’s Gansu subsidiary, with technology research and development undertaken by Xi’an Thermal Power Research Institute.
The installation is expected to strengthen the plant’s frequency regulation response and improve the regional grid’s ability to withstand disturbances, supporting the safe and stable operation of the power system in northwestern China.
Source: Science and Technology Daily, November 6, 2026. Adapted from the original Chinese report.
Photo credit: China Huaneng.
Energy Storage Leaders Are Building Their Own AIDCs: From Selling Equipment to Owning Computing Capacity—Who Will Be First to Scale Up?
The AIDC sector has continued to gain momentum in 2026, with energy storage companies moving in through different routes. Envision Energy, HyperStrong and GCL Energy Technology have each advanced self-developed data center projects. CATL has used equity investments to connect upstream and downstream players across the industry chain, while companies including Sungrow, NR Electric and Shuangdeng Group have rolled out energy solutions tailored to AIDCs.
The convergence of computing power and energy has become an industry-wide consensus. Yet behind the current boom are several unresolved questions: What differentiated paths are available to energy storage companies entering the AIDC market? Can the business model for building and operating their own computing centers prove commercially viable? And what long-term value will this deep integration of energy and computing ultimately create for the energy storage industry?
Three Routes for Energy Storage Companies Entering the AIDC Market
Route 1:
Asset-Heavy, Self-Built AIDCs: Toward Integrated Power-and-Computing Operations
This is the most capital-intensive route for energy storage companies entering the AIDC market, and the one that extends furthest along the industry chain. Companies act as project investors, acquire land and build intelligent computing clusters, retain ownership of the computing assets and operate them independently. Renewable generation, energy storage and computing loads are brought under a unified dispatch system.
Envision Energy | Envision Galaxy Campus in Ulanqab
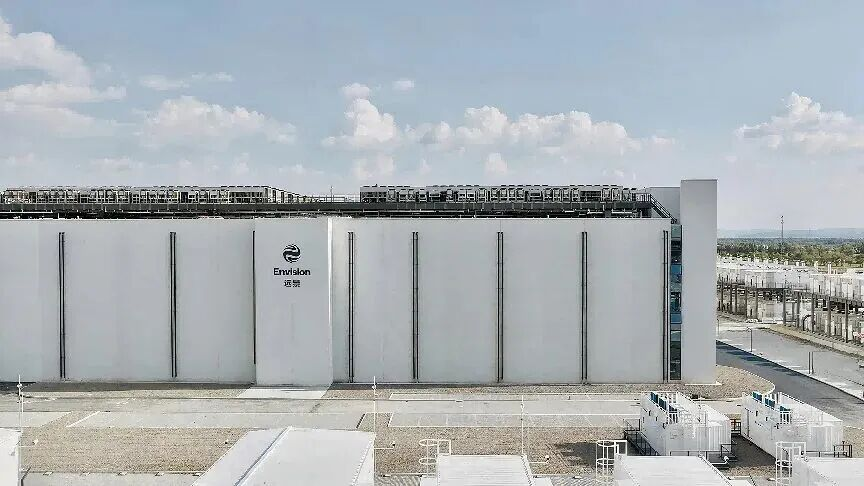
Envision Energy has developed the Envision Galaxy Campus in Ulanqab, Inner Mongolia, which officially commenced operations in August 2026. The project is planned to reach a computing capacity of 3 GW. Once completed, it is expected to support one million accelerators operating in parallel and deliver computing capacity on the scale of one million P; more than 80% of its electricity will be supplied directly by green power. The campus uses Envision’s self-developed 800V high-voltage direct-current (HVDC) power supply system—the first of its kind to enter operation globally—and offers computing-power leasing services to domestic computing clusters and large-model customers.
HyperStrong | Baotou Storage-Computing Integration Project and Token Factory
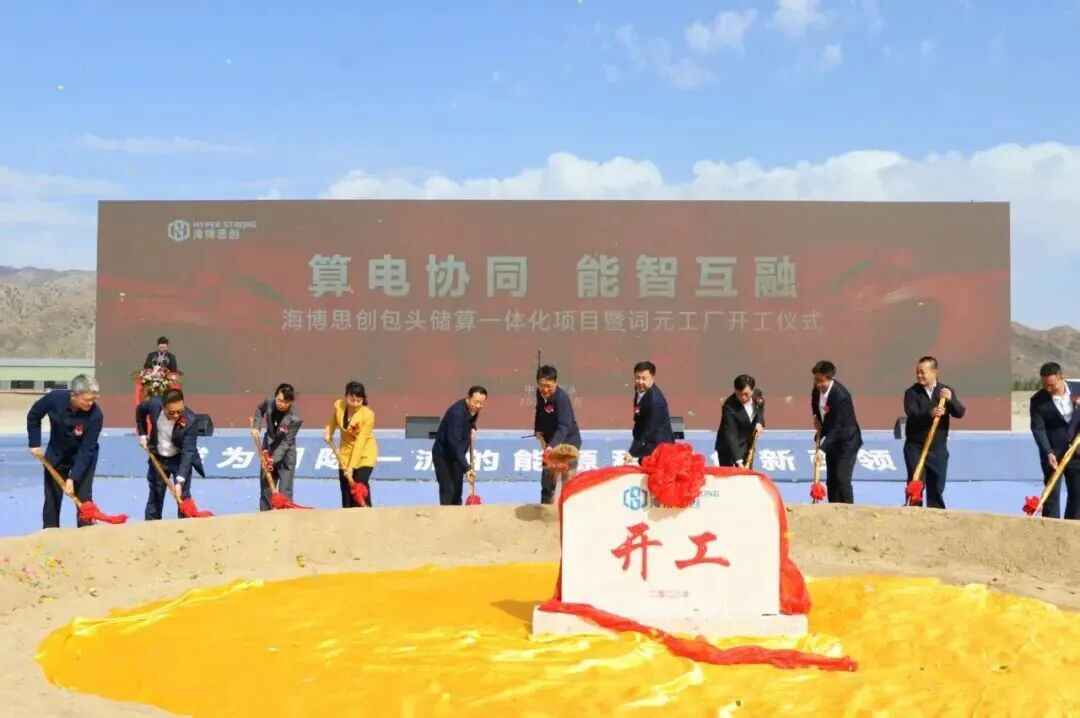
HyperStrong is developing a storage-computing integrated Token Factory in Baotou, Inner Mongolia. The project officially broke ground on September 29, 2026, and is described as China’s first storage-computing integration demonstration project. Its core equipment includes HyperSST solid-state transformers and HyperPTU power container units. Under the innovative Token Factory model, computing capacity is converted into standardized services that can be measured, priced and delivered to customers.
GCL Energy Technology | South China Intelligent Computing Base in Shaoguan, Guangdong, and Zhongwei Token Factory in Ningxia
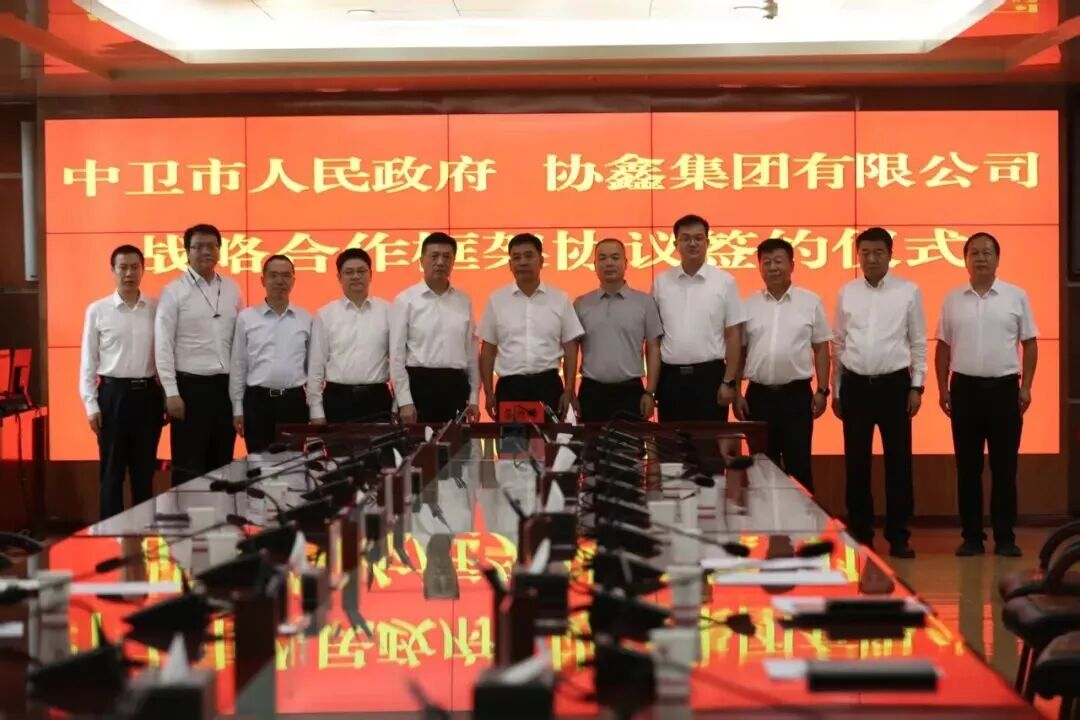
In June and July, GCL Energy Technology signed agreements with the city of Shaoguan and the Zhongwei Industrial Park in Ningxia, respectively, to develop intelligent computing projects. Phase I of the South China Intelligent Computing Base in Shaoguan involves an investment of RMB 10 billion and is planned to include 80,000 standard server racks. Longer-term plans call for a gigawatt-scale, zero-carbon intelligent computing park and a Token operations center. The Zhongwei project centers on the development of a large-scale Token Factory, supported by an AI Token operations platform and integrated new-energy and computing-power infrastructure.
In terms of revenue, this model goes beyond collecting fees for computing-power leasing. Instead, it creates a multi-layered revenue loop:
Basic computing-power leasing provides the core recurring cash flow
Value-added Token services capture higher-margin opportunities
The self-built campus creates demand for the company’s own energy storage equipment and energy solutions
Co-located energy storage assets can participate in electricity markets to generate additional revenue
Route 2:
Capital-Chain Investments: An Asset-Light Position in the Power-and-Computing Ecosystem
Companies following this route do not directly invest in, build or operate computing facilities. Instead, they use equity investments to secure positions in key links upstream and downstream of the computing industry chain.
Representative Case: CATL’s End-to-End Ecosystem Strategy
Rather than building AIDC assets itself, CATL has invested step by step along the chain—from power supply technologies to computing facilities and downstream applications:
An affiliated party acquired a 38.1% stake in VNET Group, a leading AIDC operator, becoming its largest shareholder
CATL increased the capital of the controlling shareholder of Hangzhou Zhongheng Electric and secured a 49% stake, positioning itself in the core HVDC power supply segment
Through an industry investment fund, CATL also invested in the large-model company DeepSeek, gaining exposure to downstream demand for computing power
Through these three layers of investment, CATL has established an industrial loop spanning energy storage batteries, HVDC power supply, computing facilities and demand from large AI models. This provides an industrial foundation for joint R&D and deployment of power-and-computing coordination technologies and solutions.
Route 3:
Supplying the Energy Infrastructure: Focusing on Products and Solutions
This is the route chosen by the vast majority of energy storage companies, and it is where the largest concentration of orders in the AIDC market can currently be found. These companies do not own computing assets. Instead, they draw on their expertise in power electronics, energy storage systems and power management to supply AIDCs with essential energy infrastructure products and solutions.
By technology focus, the key players fall into three categories:
High-voltage power supply and energy-routing solution providers: Companies including Sungrow, NR Electric, Envision Energy, Zhiguang Electric, Kehua Data, KSTAR, Xinfengguang and Sifang are building out solid-state transformer (SST) product portfolios on the back of their power-electronics capabilities in energy storage. Sungrow’s EnerNeo series of SSTs has become one of NVIDIA’s first SST ecosystem partners, while NR Electric’s products have been deployed at Jiangsu’s first energy storage demonstration platform for power-and-computing coordination.
Integrated energy management and energy storage system integrators: Huawei Digital Power, Trina Storage, Kehua Tech, Clou Electronics, HyperStrong, Jinko ESS and Gotion High-tech are leveraging their energy storage system integration capabilities to develop integrated AIDC energy solutions spanning power sources, grids, loads, energy storage and computing.
Suppliers of highly reliable backup-power storage cells and systems: CATL, Shuangdeng Group, EVE Energy, BYD Energy Storage, Great Power, Sunwoda, REPT BATTERO, Narada Power, Pylontech, Ampace and CORNEX are building product portfolios for backup power and energy storage across AIDC scenarios, drawing on their expertise in high-rate energy storage cells.
The Industrial Value of Integrating Energy Storage and Computing
Returning to the question raised at the outset: what can the growing involvement of energy storage companies in AIDCs bring to the industry?
Deeper Technical Validation and Iteration Through Storage-Computing Integration
Under the traditional AIDC development model, energy storage and computing operate in separate chains, limiting the benefits of coordination. The storage-computing integration model led by energy storage companies tightly couples the two. It provides large-scale validation environments for technologies such as SSTs, grid-forming energy storage and HVDC power supply, accelerating technology maturation and cost reductions. This will help AIDC energy solutions evolve from basic supporting infrastructure to integrated, natively designed systems.
Expanding and Upgrading Energy Storage Business Models
As energy storage companies deepen their penetration of the AIDC market, the industry’s revenue models are becoming more diversified and sophisticated. Revenue streams are expanding beyond traditional equipment sales and energy storage station operations to include integrated solutions spanning power sources, grids, loads, energy storage and computing, and further into computing-power leasing and value-added Token monetization. This creates a progressive revenue structure built around “hardware + solutions + operations” and moves the industry beyond monetizing standalone power assets toward a composite value model combining energy, computing and AI.
This industrial convergence creates benefits in both directions: it opens up new market opportunities for the energy storage industry while also accelerating reductions in AIDC energy costs and supporting the transition to low-carbon operations.
Practical Challenges Facing Energy Storage Companies Entering the AIDC Market
Of course, energy storage companies face significant challenges on the road into the AIDC market.
The first is the high capital requirement and operational barrier. Building an AIDC from the ground up requires substantial investment. Moving from supplying energy equipment to operating computing infrastructure also requires time to build the necessary teams, resources and capabilities. The payback period for these projects remains uncertain.
The second is intensifying competition in the computing-power market. AIDC construction continues to accelerate in China, with computing parks being developed across multiple regions. Energy storage companies entering this market from adjacent industries do not necessarily have an advantage in access to computing resources or customer channels.
The third is the risk of technological obsolescence. AI computing technologies are evolving rapidly, while computing architectures, power supply solutions and equipment standards continue to change. Capital-intensive computing campuses therefore face the risk that their technology choices will become outdated and their assets will depreciate more quickly.
Conclusion
The influx of energy storage companies into the AIDC market is not simply a matter of following a cross-industry trend. It is a natural outcome of the convergence of the computing industry and the new-type power system.
The three routes reflect choices made by companies according to their respective resources and strategic positioning. The self-build model is the most capital-intensive and aims to capture the long-term value of integrated power-and-computing operations. Capital investment offers greater flexibility and focuses on industrial synergies and ecosystem development. Supplying core energy infrastructure is the most stable route, allowing companies to translate their existing technological advantages into business results more quickly.
One thing is clear: the rapid growth of AIDCs is continuously reshaping the boundaries of the energy storage industry. Energy storage is no longer merely a backup power source for data centers; it is becoming a critical nexus connecting computing infrastructure with the new-type power system. Power-and-computing coordination is also set to become a major growth driver for the energy storage industry in its next stage of development.
The 15th Energy Storage International Conference and Expo (ESIE 2027), organized by the China Energy Storage Alliance (CNESA), the China Energy Research Society and the Institute of Engineering Thermophysics of the Chinese Academy of Sciences, will be held from March 16 to 19, 2027, at the Capital International Exhibition & Convention Center in Beijing.
For the first time, ESIE 2027 will feature an exhibition dedicated to AIDC power-and-computing coordination. It will showcase frontier technologies and products, including high-rate BBU energy storage, SST solid-state transformers, HVDC, immersion and cold-plate liquid cooling, direct green-power supply, integrated power-source-grid-load-storage systems, and joint dispatch systems for computing and energy storage. The exhibition will be accompanied by thematic forums, new-product launches and matchmaking events, bringing together key buyers such as the three major telecom operators, cloud service providers and IDC operators. It will continue to serve as a platform for cross-sector collaboration between computing and energy storage, supporting the high-quality development of the energy storage industry.
ESIE | 2027 Debuts AIDC Energy Storage Section, Targeting the New Blue Ocean of Data Center Energy Storage
As one of the world's largest energy storage exhibitions, ESIE has witnessed and continues to lead the innovation and development of the global energy storage industry through fourteen editions of heritage.
The 15th Energy Storage International Summit and Exhibition (ESIE 2027), organized by the China Energy Storage Alliance, the China Energy Research Society, and the Institute of Engineering Thermophysics of the Chinese Academy of Sciences, will be held on March 16-19, 2027 at the Capital International Convention & Exhibition Center in Beijing.
ESIE 2027 Debuts
the AIDC Energy Storage Section
An Exploding New Storage Track
ESIE 2027 debuts its AIDC Energy Storage section precisely against the backdrop of this track's explosive growth.
March 2026 - "Computing-electricity coordination" was written into the Government Work Report for the first time, becoming an important lever for the deep integration of computing power and electricity.
April 2026 - The Action Plan on Promoting Two-Way Empowerment Between Artificial Intelligence and Energy explicitly encourages computing facilities to be equipped with grid-forming energy storage, enabling computing facilities to participate in grid operations as flexible, adjustable load-side resources.
June 2026 - The 15th Five-Year Plan for Building a New Energy System calls for promoting direct green power supply projects for computing centers and "strengthening computing with electricity and promoting electricity through computing".
July 2026 - In its reply to a National People's Congress proposal, the National Energy Administration noted that pilot programs will give key consideration to AIDC energy storage application scenarios, and the first-set-of-equipment selection will consider supporting technical equipment for AIDC energy storage application scenarios.
On the market side, according to National Energy Administration data, total electricity consumption of computing centers nationwide reached 170 billion kWh in 2025, and computing electricity consumption at the eight hub nodes of the national integrated computing power network grew at an average annual rate of about 39.5% over the past three years. During the 15th Five-Year Plan period, national computing electricity consumption is expected to grow by more than 100 billion kWh per year on average, reaching an estimated 800 billion kWh by 2030.
The explosive growth in computing demand not only calls for higher power supply reliability, but also raises brand-new requirements for data centers' energy costs, green power consumption, and computing dispatch. AIDC energy storage is precisely the key carrier connecting computing loads, green power supply, and grid regulation.
But Amid High Growth,
AIDC Energy Storage Still Faces Several Practical Problems
Technology routes still evolving. UPS, HVDC, and SST routes coexist, and solutions differ widely between vendors. Many companies remain at the "selling batteries" stage, lacking integrated solution capabilities from rack-level backup power to campus-level energy storage.
Cost and return out of balance. AIDC supporting energy storage carries high initial investment and a long payback period. Current returns rely mainly on peak shaving/valley filling and backup power assurance; value-added revenue channels such as green power trading, demand response, and ancillary services remain underdeveloped.
Missing standards. Technical standards, acceptance specifications, and safety requirements for AIDC energy storage are still being drafted. High-rate cells, BBUs, and liquid cooling integration lack unified standards, leaving poor product compatibility and no basis for procurement and acceptance.
Insufficient supply-demand matching. Energy storage companies do not understand computing, and cloud vendors do not understand energy storage; both sides lack an effective exchange platform. Information gaps persist between the real needs of the three major telecom operators, cloud vendors, and IDC operators on one side, and the product capabilities of energy storage companies on the other.
The 15th Energy Storage International Summit and Exhibition
Debuts the AIDC Energy Storage Section for the First Time
Exhibition + Matchmaking + Launches + Forums in One
1. Exhibition: The Full Chain of Computing Power Supply
AIDC Energy Storage Panorama Exhibition - all technology routes in one visit:
• Rack-level backup power: high-rate BBU cells, supercapacitors (EDLC), hybrid backup solutions
• Data hall-level power supply: lithium battery UPS systems, HVDC high-voltage DC systems, SST solid-state transformers, grid-forming PCS
• Thermal management systems: cold plate liquid cooling, immersion liquid cooling
• Campus-level energy storage: C&I energy storage cabinets, large-scale storage containers, grid-forming energy storage systems
• Software & platforms: AIDC energy storage EMS, computing-electricity coordination dispatch platforms, digital twin O&M systems
• From millisecond-level power support to hour-level energy regulation - every level in a single visit
2. Matchmaking: Onsite Exchange with Domestic and International Buyers
• Domestic: representatives of the three major telecom operators, domestic cloud providers such as Tencent Cloud, and IDC operators such as Chindata and VNET share data center energy storage practices and procurement needs
• International: overseas cloud providers and IDC operators including Amazon, Google, and Meta join the exchange
3. Launches: Global First Releases of AIDC New Products
The hottest technology directions in AIDC energy storage, with concentrated first launches:
• SST solid-state transformers: core equipment of the 800 V high-voltage DC power supply architecture, the next-generation direction of data center power supply transformation
• High-rate BBU cells: 50C+ discharge, millisecond-level response, a must-have for GPU cluster backup power
• Immersion liquid cooling: single-phase and two-phase routes, the required solution for rack power density above 30 kW
• HVDC high-voltage DC: next-generation power supply technology, 2-3 percentage points more efficient than traditional UPS
• Campus-level energy storage systems: AIDC supporting energy storage with multiple revenue streams from peak shaving/valley filling, green power consumption, and demand response
• Multiple industry-first products make their debut, targeting the most cutting-edge technology directions
4. Forums: Computing-Electricity Coordination Thematic Exchanges
A forum series running alongside the exhibition for in-depth discussion of core AIDC energy storage topics:
• Policy interpretation: top-level design and market mechanisms of computing-electricity coordination, and how they affect energy storage returns
• Technology routes: comparison of UPS, HVDC, and SST power supply architectures and selection logic
• Deployment scenarios: rack-level, data hall-level, and campus-level technical requirements and applicable scenarios
• Business models: revenue models and investment return analysis for peak shaving/valley filling, demand response, green power trading, and virtual power plants
• Operators, cloud vendors, IDC operators, and energy storage companies in dialogue to promote supply-demand matching
5. Going Global: International Market Connections
• International buyer delegations: representatives of cloud vendors, IDC operators, EPC contractors, and infrastructure funds from North America, Europe, Southeast Asia, the Middle East, and elsewhere for onsite matchmaking
• Overseas market sessions: the global AIDC energy storage market landscape and regional opportunities; international certification paths such as UL/CE/IEC and AIDC-specific requirements such as NVIDIA BESS certification; overseas project implementation models and profit paths; and localization compliance requirements to help energy storage companies expand into overseas computing markets
Only 30% of Booths Remain
ESIE 2027: Six Major Sections
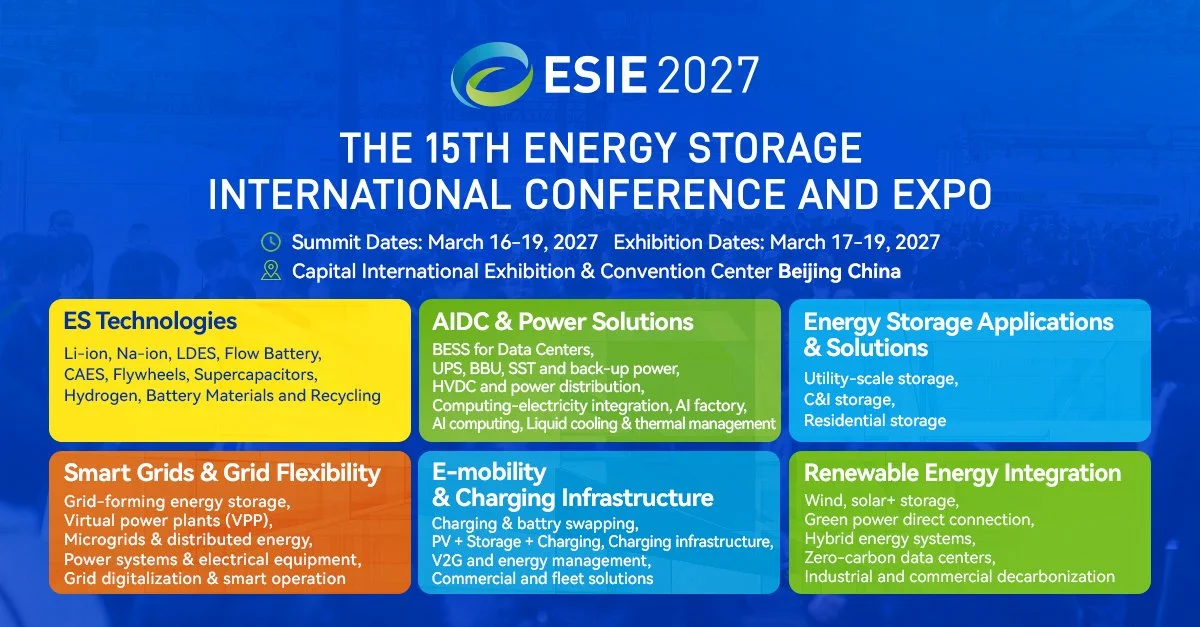
01 New Energy Storage
A panorama of the full technology roadmap of new energy storage, covering frontier technologies such as lithium, sodium, flow batteries, solid-state batteries, compressed air, flywheel, and hydrogen. Frontier technology conferences led by academicians and global first-release events for new energy storage products help companies debut next-generation energy storage technology products.
02 AIDC Energy Storage
The first AIDC display section in a professional energy storage exhibition, focusing on rack-level backup power, data hall-level power supply, power supply architecture upgrades, and thermal management, covering the full chain of BBUs, high-rate cells, UPS, SST, and more. High-value buyers from the three major telecom operators, cloud vendors, and IDC operators in attendance.
03 Full-Stack Energy Storage Solutions
Covering residential, C&I, and utility-scale scenarios, showcasing a complete product matrix from cells and core components to systems, and from hardware and software to operations. Multiple international business matchmaking sessions help companies go global.
04 Smart Grid
Focusing on grid adaptation technologies under high renewable penetration, showcasing grid-forming energy storage, flexible transmission, virtual power plants, and smart microgrids. Professional buyers from grid companies, power design institutes, and renewable plant owners in attendance.
05 Transportation-Energy Integration
Covering charging piles, battery-swap stations, integrated PV-storage-charging stations, V2G bidirectional charging/discharging systems, shore power for ships, port energy storage, and regenerative braking energy storage for rail transit - complete solutions for bidirectional vehicle-grid interaction. Cross-sector buyers from automakers, charging operators, mobility platforms, and transport infrastructure investors in attendance.
06 Green Energy
Around scenarios such as direct green power supply, large energy bases, zero-carbon parks, and integrated energy services, presenting zero-carbon solutions from renewable energy development and power trading to end-use energy. High-value buyers from industrial park owners, local governments, high-energy-consuming enterprises, power retail companies, and integrated energy service providers in attendance.
The World's Largest Energy Storage Exhibition
ESIE 2027: Six Core Advantages
01 Industry Leaders Gathered
• Selected past exhibitors
02 Global Cooperation
• International buyers from 90+ countries and regions, covering core markets in Europe, Southeast Asia, the Middle East, and Africa;
• 4 international business matchmaking sessions for precise supply-demand matching.
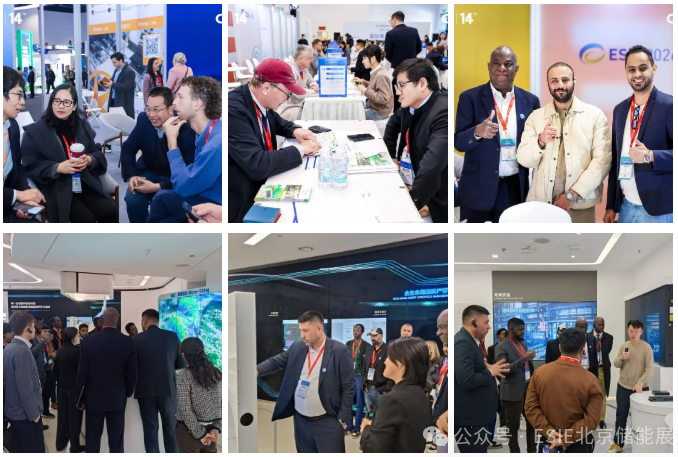
03 Efficient Matchmaking
• Professional exhibition tour groups covering professional buyers such as central and state-owned energy groups, AIDC operators, and C&I park owners;
• Online smart matching plus offline supply-demand exchange to shorten the matchmaking process.
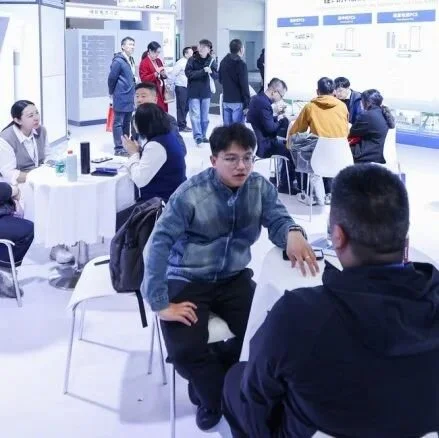
04 Authoritative Leadership
• Government and energy authorities, State Grid, China Southern Power Grid, and power generation groups in attendance.
• Leaders of top energy storage companies engage in deep dialogue on strategic development directions for the new cycle.
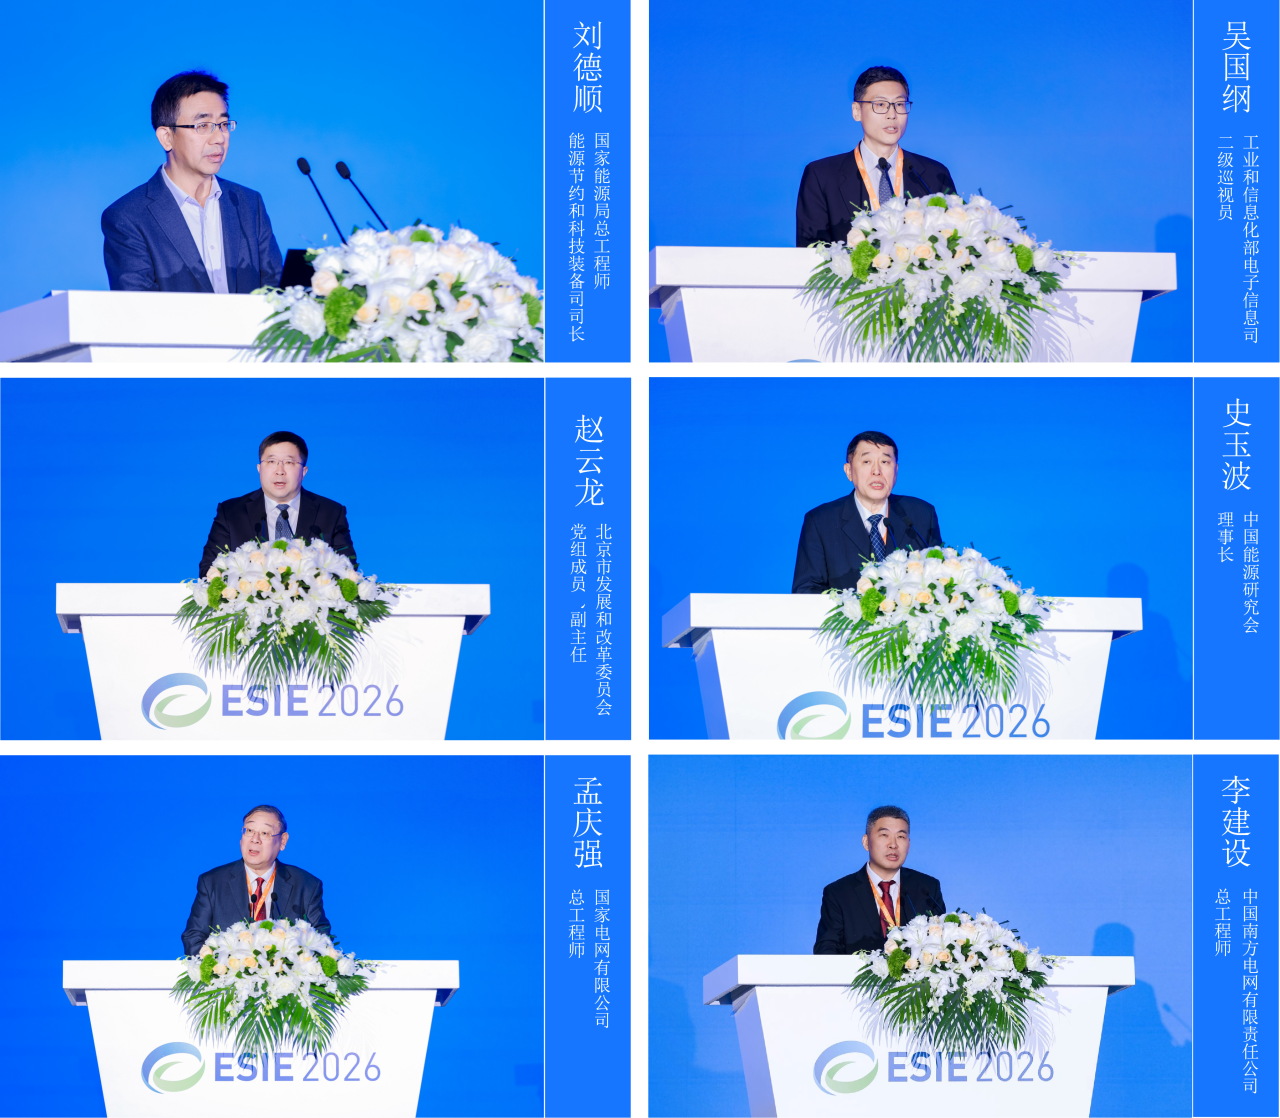
• Selected past guests
05 Technology Leadership
• More than ten academicians of the two academies in attendance;
• Assessment of the development status and future trends of frontier technologies such as hydrogen, long-duration energy storage, short-duration high-frequency energy storage, and grid-forming energy storage;
• Companies' annual blockbuster products make their global debuts here.
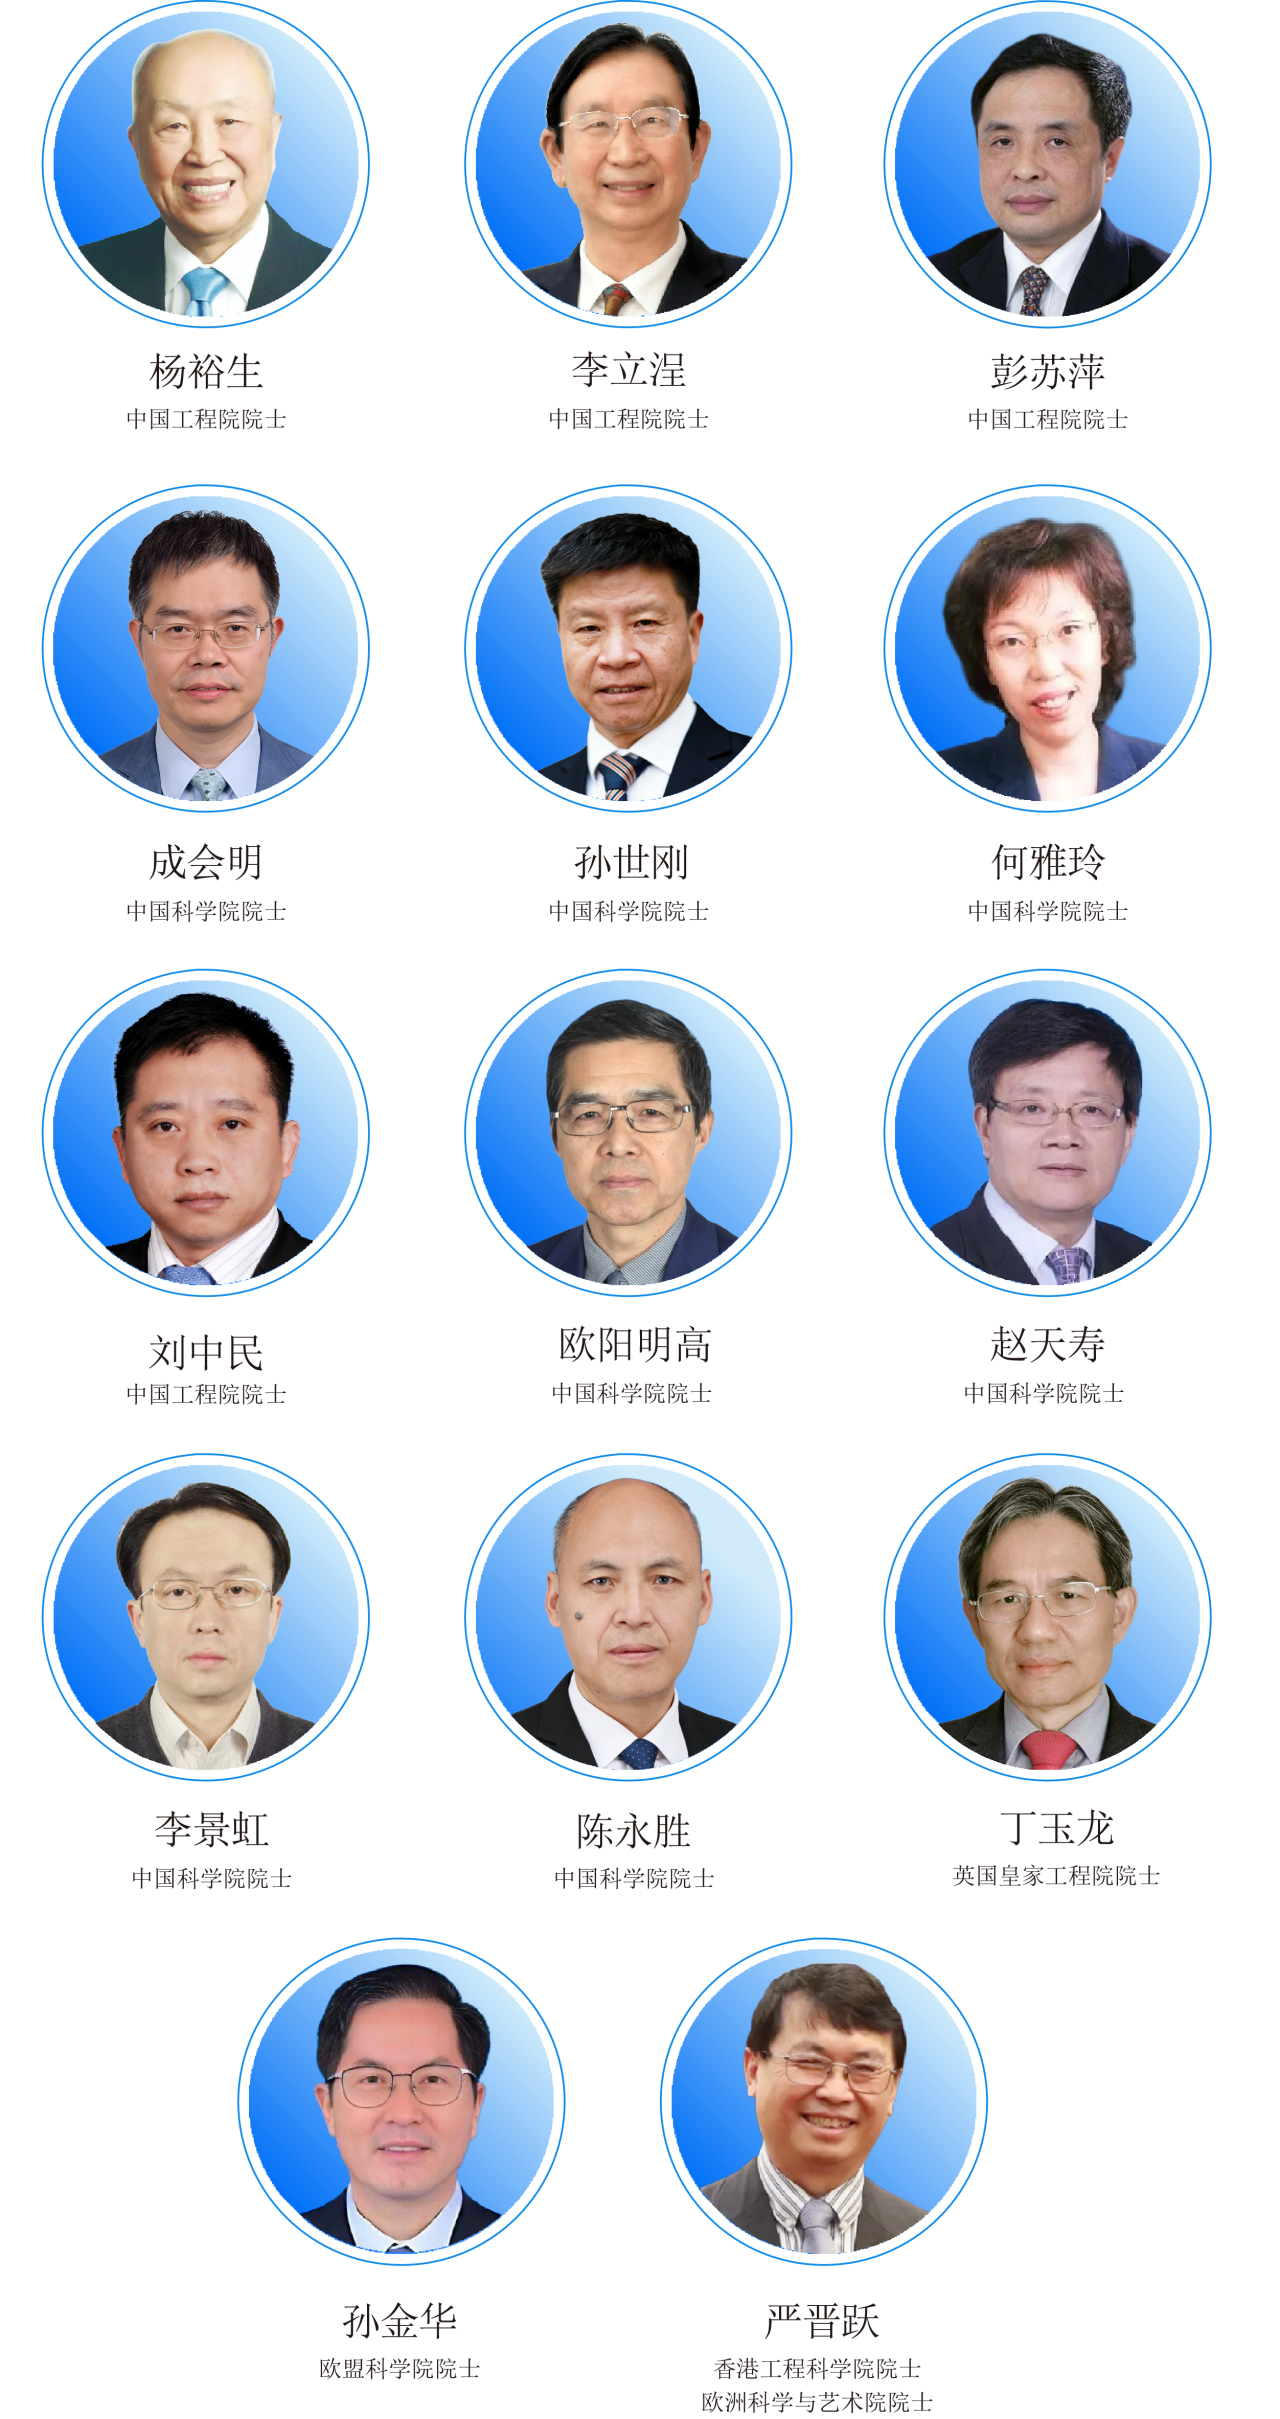
• Selected past guests
06 Industry-Academia-Research-Finance Synergy
• 40+ thematic forums with 400+ industry leaders taking the stage;
• Core topics from policy outlook, market mechanisms, and technology trends to industry-finance matchmaking, building a high ground for thought exchange in the energy storage industry.
March 16-19, 2027
Beijing - Capital International Convention & Exhibition Center
ESIE 2027 cordially invites colleagues from the global energy storage community to reunite.
Together, let us build a new future of high-quality development for new energy storage!
Sungrow EnerNeo SST Becomes the World’s First SST with Dual EU-US System-Level Certification: cTUVus + EMC + 13.8kV Reinforced Insulation
The surge in AI computing demand is pushing data center power architectures toward the 800V DC era. The China Energy Storage Alliance (CNESA) has noted that Sungrow’s EnerNeo solid-state transformer (SST) received system-level certification from TÜV Rheinland at the 2026 OCP Global Summit, becoming the world’s first SST to pass both European (IEC/EN) and American (UL) system-level certification and the first to secure a ticket to large-scale commercial deployment in the European and American data center markets. This article examines the substance of the certification, the technology route and the cost calculus behind the milestone.
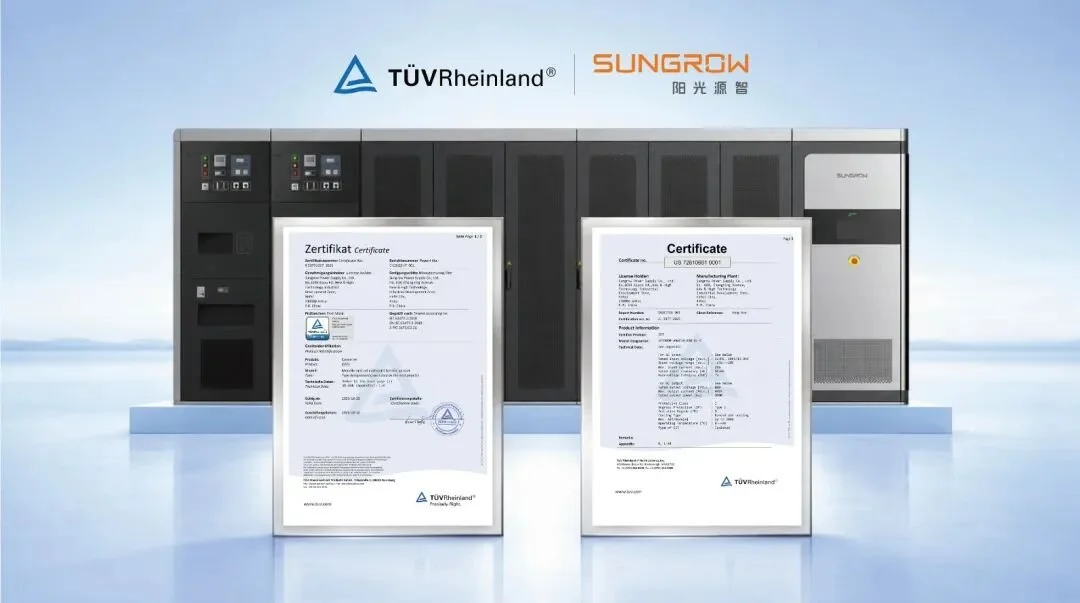
At the 2026 OCP Global Summit, Zhang Di, President of Sungrow Source Intelligence, received a set of certificates from Sean Tilley, Vice President of the Product Services Business Unit of TÜV Rheinland Americas. The EnerNeo SST became the world’s first SST product to pass both European (IEC/EN) and American (UL) system-level certification, with the complete set of cTUVus, EMC and 13.8kV reinforced insulation certificates.
Not One Certificate, but a Stack
During the days of the OCP Global Summit, the convention center in San Jose, Silicon Valley, was packed with data center professionals. It was there that Sean Tilley handed Zhang Di the system-level and key-component certification certificates based on the UL, IEC, EN and 2 PfG series standards.
This certification covers the complete SST system. TÜV Rheinland conducted a system-level assessment of the EnerNeo against safety standards including UL 2877, IEC/EN 62477-1, IEC/EN 62477-2 and 2 PfG 3175, as well as EMC standards including EN 61000-6-2, EN 61000-6-4 and FCC Part 15. The core component, the high-frequency isolation transformer, additionally passed the dedicated 2 PfG 3179 certification, meeting the 13.8kV reinforced insulation requirement.
The outcome: the EnerNeo obtained the TÜV Rheinland certification mark, the cTUVus and EMC certificates, and the corresponding test reports. For Chinese equipment makers aiming to enter the European and American data center supply chains, completing this full set is far more difficult than passing any single test.
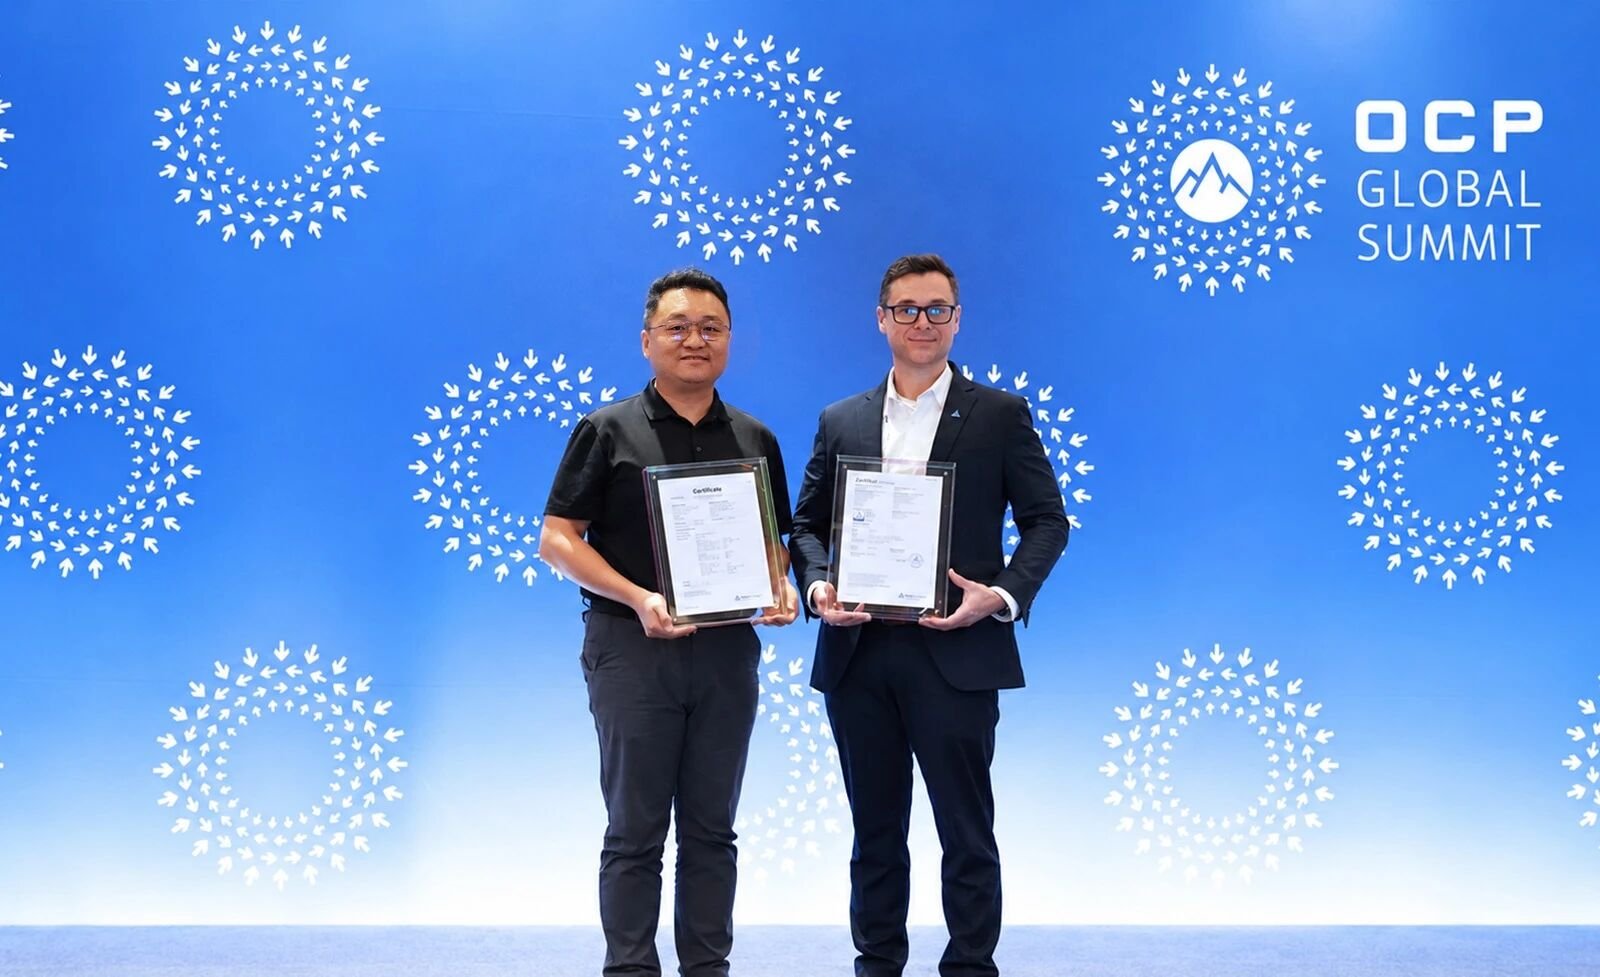
Sean Tilley (right), Vice President of the Product Services Business Unit of TÜV Rheinland Americas, presents the certification certificates to Zhang Di (left), President of Sungrow Source Intelligence.
Why System-Level Certification Is the Real Barrier
Some may ask: SST certification is not news, given that Eaton passed TÜV SÜD’s IEC 62477-2 certification in August. What is the difference?
The key lies in “system-level” and “dual-standard”.
The Solid State Transformer Specification v0.3, effective from June this year under the Open Compute Project (OCP) and jointly developed by Google, Microsoft and NVIDIA, defines the SST as a megawatt-class power electronics converter: a 13.8kV or 34.5kV medium-voltage AC input and an 800V DC output, with a power range corresponding to 5MW or 10MW. The specification covers not only power conversion but also medium-voltage input, low-voltage DC output, auxiliary power, firmware, control and communication, all within the scope of the SST product.
In other words, an SST is no longer just the “transformer” component; it is a complete power electronics system comprising power semiconductors, magnetics, control systems and communication systems. To pass system-level certification, insulation, efficiency, power density and thermal management must all meet the requirements simultaneously, rather than passing part by part.
Certification Dimension
Standards Indicators Involved
US Safety Standards UL 2877
EU Safety Standards IEC/EN 62477-1, IEC/EN 62477-2
Key Component 2 PfG 3175, 2 PfG 3179 (high-frequency isolation transformer,
13.8kV reinforced insulation)
EMC EN 61000-6-2, EN 61000-6-4, FCC Part 15
Certification Marks TÜV Rheinland certification mark, cTUVus, EMC certificates
The European and American markets are particularly strict on this point – UL and cTUVus on the US side, and the IEC/EN series on the European side. For entry into European and American data center procurement lists, system-level dual certification is close to a hard threshold. By securing both at once, the EnerNeo can now compete on equal footing with overseas players such as Delta, Eaton and Vertiv in terms of certification compliance.
800V DC: NVIDIA Sets the Course, Sungrow Delivers First
Why focus on 800V DC? The answer lies in power density.
The white paper “800VDC Architecture for Next-Generation AI Infrastructure”, released by NVIDIA at last October’s OCP Global Summit, has established 800V DC as the standard power architecture for next-generation AI infrastructure, with the SST positioned as the ultimate power supply device in the medium to long term. Sungrow’s 800V solution is also listed in the white paper as a recommended technology route.
The traditional data center power chain is: AC from the grid → step-down via a power-frequency transformer → multi-stage UPS/AC-DC conversion → server racks. Each stage incurs losses, with end-to-end efficiency of about 90%–92%. For megawatt-class racks, hundred-megawatt buildings and gigawatt-scale campuses, these few percentage points of loss translate into enormous electricity bills and thermal loads.
What the EnerNeo does is convert 10–13.8kV medium-voltage AC directly to 800V DC, using SiC power devices and an optimized series-connected H-bridge architecture, eliminating the power-frequency transformer and multi-stage conversion. Published parameters: 98.5% efficiency, 99.999% availability, 312 kW/m² power density, zero partial discharge at rack level (within 21kV), meeting the 42kV power-frequency withstand voltage and 95kV lightning impulse indicators.
According to Sungrow’s own calculation, for a 1GW computing project, the 800V DC architecture can save 400 million kWh of electricity per year. In terms of efficiency difference, 98.5% versus the 90%–92% of the full chain leaves a gap of 6–8 percentage points – no small figure at gigawatt scale.
The EnerNeo SST system and the TÜV Rheinland certificates
Evolution of the power architecture for AI supernode full racks: single-rack power leaps from the 100kW class to the megawatt class, making 800V HVDC an inevitable choice.
The Cost Calculus: SST and Traditional Solutions Are Now on the Same Level
Technology, however good, must pass the cost test. The most-cited criticism of the SST used to be its price; that anchor is now beginning to shift.
In August 2026, the SST procurement budget for the data center of the “Zhiyun Changjingkai” platform was RMB 2 million for 2.5MW of capacity, equivalent to a budgeted unit price of about RMB 0.8/W. In the same year, China Mobile Jiangsu purchased four sets of 2500kVA medium-voltage integrated power systems for its Nanjing Jiangbei Data Center at a winning price of about RMB 1.77 million per set excluding tax, or about RMB 2 million including 13% VAT. 2500kVA is AC apparent power; with the data center load power factor close to 1, the two can be compared at similar capacity levels.
Comparison Item SST Solution Traditional Medium-Voltage Integrated Power
Project Sample Zhiyun Changjingkai 2.5MW SST China Mobile Jiangsu 2500kVA integrated power
Procurement Budget / About RMB 2 million (budget) About RMB 2 million per set (incl. 13% VAT)
Winning Price
Unit Price About RMB 0.8/W About RMB 0.8/W (equivalent at similar capacity)
Capacity Class 2.5MW 2500kVA(≈2.5MW, power factor close to 1)
The comparison is noteworthy: the procurement budget of a 2.5MW-class SST is broadly on par with the winning price of a comparable 2500kVA integrated power system. Once costs reach the same level, the advantages in efficiency, footprint and response speed become decisive factors in procurement decisions.
Certification Is a Ticket, Not the Destination
Back to the OCP Summit. Experts from Google, Microsoft and NVIDIA stood in the audience as Zhang Di received the certificates – a scene carrying more information than the certificates themselves: the core initiators of the OCP SST working group are casting a vote of confidence in a Chinese manufacturer’s technology route.
But this vote is only an entry ticket. The industry is still in the stage of small-batch delivery and customer site validation. Between “certification passed” and “large-scale commercialization” lie multiple tests: engineering reliability, O&M systems, supply chain responsiveness, and acceptance by financing and insurance institutions.
What deserves even closer observation is whether Sungrow Source Intelligence can secure its first large-scale order in Europe and America after obtaining dual-standard certification. Eaton and Delta still hold first-mover advantages in overseas data center O&M and brand recognition; the next challenge for Chinese manufacturers is not laboratory parameters, but the long-term trust of overseas customers.
Three Major Application Segments See Shrinking Returns — Can China’s New Energy Storage Resolve Its Profitability Bottleneck?
BEIJING, 15 October 2026
China Energy Storage Alliance (CNESA) has published its latest in-depth analysis on China’s new-energy-storage industry. After years of breakneck capacity expansion, the sector faces a new reality: newly-commissioned installations declined more than 15 % year-on-year in H1 2026, as profitability pressure mounts across generation-side, grid-side and customer-side segments. Having pursued a policy-fuelled “installed-capacity race”, Chinese new energy storage now stands at a crossroads, shifting focus from “building assets” toward profitable operation and tangible system-level value delivery for the carbon peaking and carbon neutrality goals.
Market Performance Review: Three Transformations — Scale, Discharge Duration and Application Mix
China’s new-energy-storage market has delivered remarkable capacity growth alongside profound structural changes in technology, discharge duration and deployment scenarios.
By the end of 2025, China’s total commissioned electric-energy-storage capacity reached 213.3 GW (+54 % YoY), accounting for 43.0 % of global installed volume and ranking first worldwide. Cumulative new-energy-storage capacity hit 144.7 GW, a 45-fold increase compared with the end of the 13th Five-Year Plan. Lithium-ion batteries represent 66 % of the national electric-storage fleet, while pumped-hydro storage contributes 31 %. Both flow-battery and compressed-air-energy-storage cumulative installations have passed the 1 GW milestone, signalling that long-duration technologies are moving from demonstration toward large-scale roll-out.
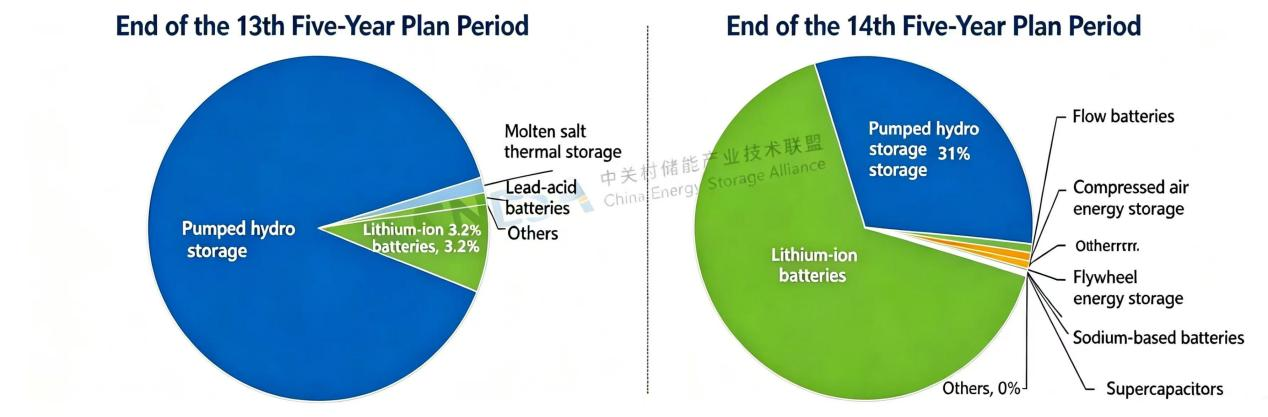
Cumulative Installed Capacity of China’s Electric Energy Storage Market (End-2025), Unit: MW & % | Source: CNESA
Storage project discharge durations keep increasing as the system demands greater long-duration flexibility. The average duration for newly-commissioned projects reached 2.85 hours in 2025, up 58 % versus 2020. Projects offering 4 hours or longer discharge grew 44 % year-on-year and have become the main growth driver.
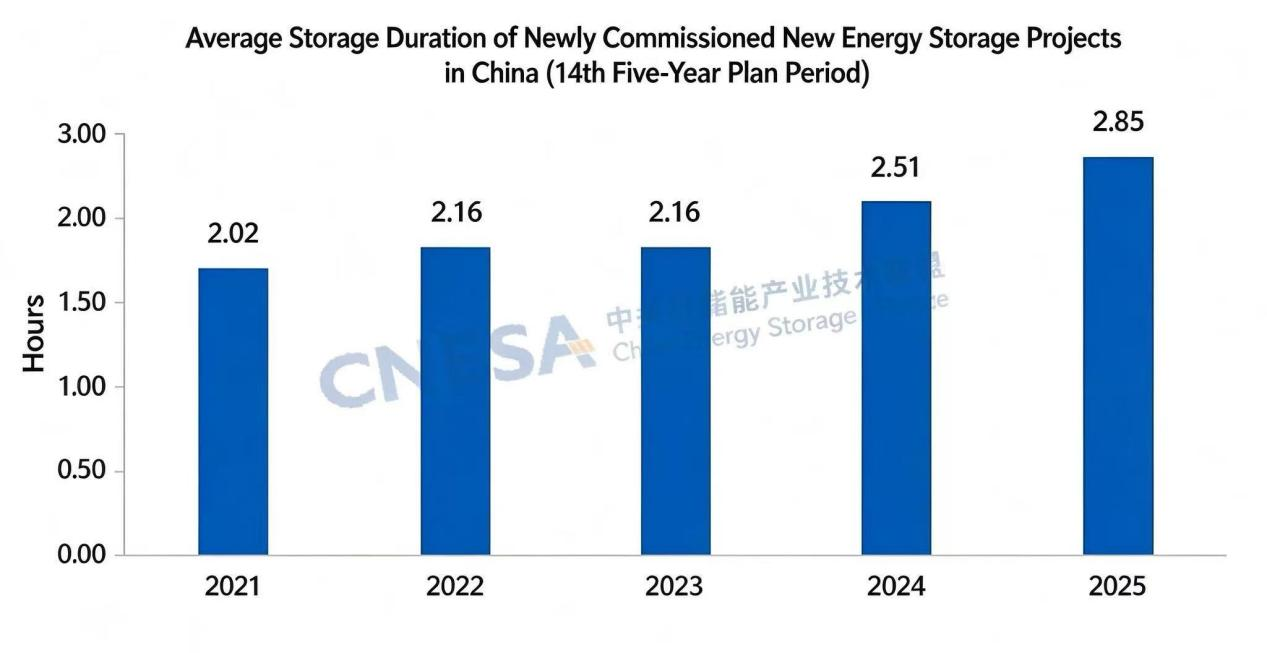
Historical Average Storage Duration of Newly Commissioned New Energy Storage Projects in China during the 14th Five-Year Plan Period, Unit: Hour | Source: CNESA
Application-segment composition has undergone fundamental change. Stand-alone storage now makes up 58 % of cumulative new-energy-storage capacity, 54 percentage-points higher than at the end of the 13th Five-Year Plan. The industry has transitioned from fragmented customer-side deployments toward large-scale, grid-centric stand-alone-storage assets.
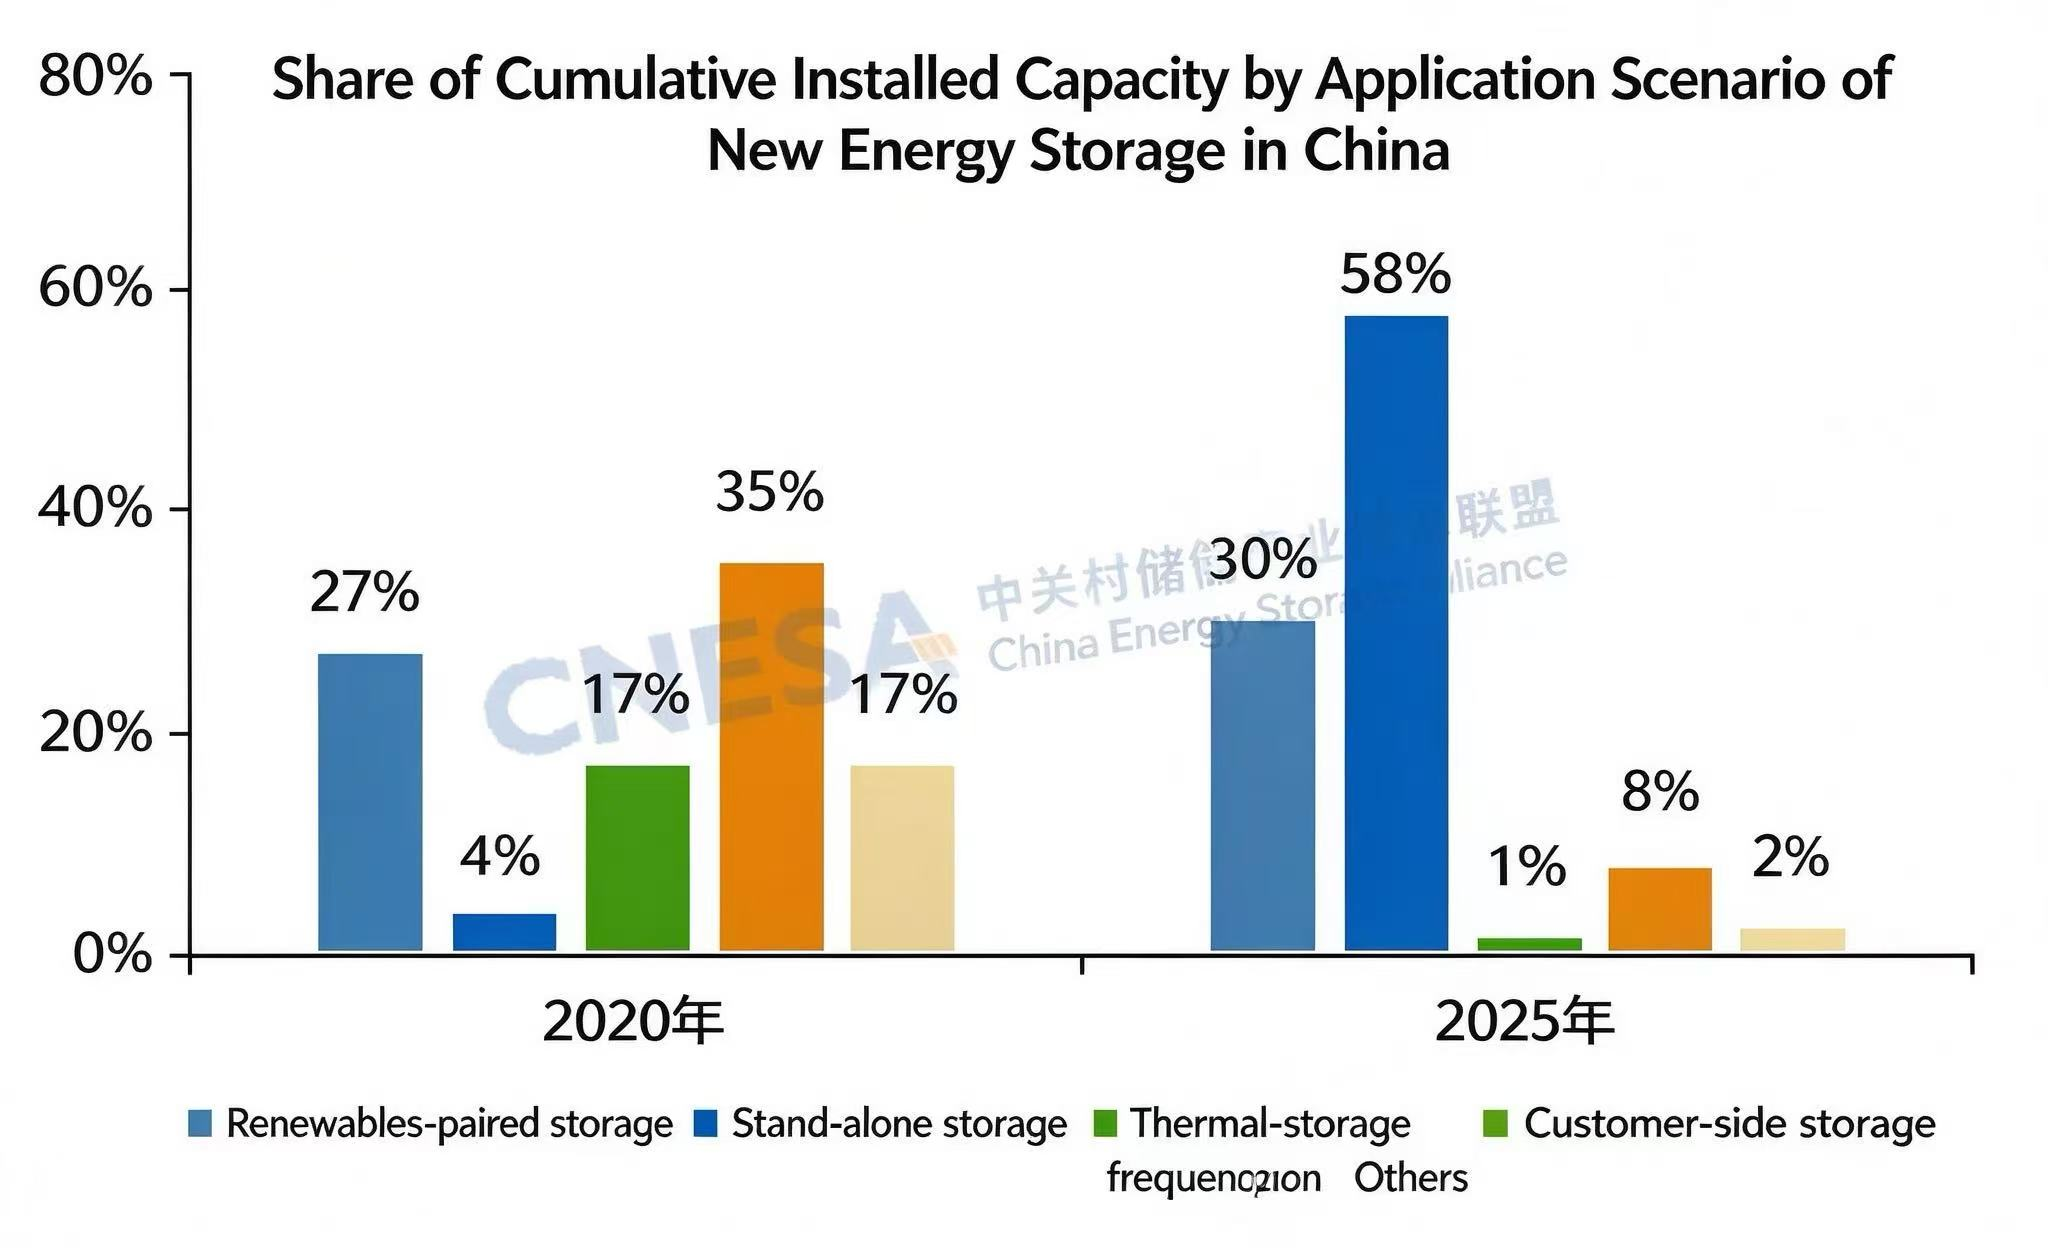
Share of Cumulative Installed Capacity by Major Application Scenarios of New Energy Storage in China, Unit: GW & % | Source: CNESA
Industry Warning: Profitability Compression Triggers First-Ever Installation Downturn
Beneath the capacity expansion, all three core application segments face contracting revenue streams:
· Renewables-paired (generation-side) storage: The abolition of mandatory pairing rules has weakened developer incentives; existing income cannot cover capital and operational expenses.
· Stand-alone (grid-side) storage: Capacity-leasing income, once exceeding 50 % of revenue in some provinces, has sharply fallen following policy adjustments; capacity-tariff mechanisms cannot fully fill the resulting funding gap.
· Customer-side (industrial & commercial) storage: Abolition of administratively-set time-of-use price bands narrows fixed peak-valley spreads, lengthening project payback periods while viable new business models remain under development.
These economic headwinds are reflected in real-world deployment statistics. H1 2026 saw 21.64 GW / 58.20 GWh of new-energy-storage go online; both power and energy metrics dropped by over 15 % year-on-year — the first contraction after multiple years of rapid expansion.
Core Bottlenecks Restraining Storage Profitability
CNESA’s analysis identifies market-design and dispatch-framework shortcomings as the primary obstacles preventing adequate returns for storage assets.
Inefficient dispatch practices limit flexibility utilisation. Renewables-paired-storage utilisation rates remain low, as charge-discharge strategies cannot always adapt dynamically to market signals. A national unified compensation scheme for emergency grid dispatch is absent, so storage’s security-support value cannot be monetised.
Generation-side paired-storage suffers uneven asset quality and narrow revenue streams. Assets built under historic mandatory-pairing requirements often under-perform design specifications and carry safety risks. Projects rely heavily on curtailment-avoidance gains and are frequently prohibited from purchasing power from the public grid, limiting operational flexibility relative to stand-alone storage.
Grid-side stand-alone storage faces unresolved gaps in pricing, cost-recovery, capacity-remuneration and ancillary-service rules. Four concrete market-mechanism bottlenecks constrain commercial performance.
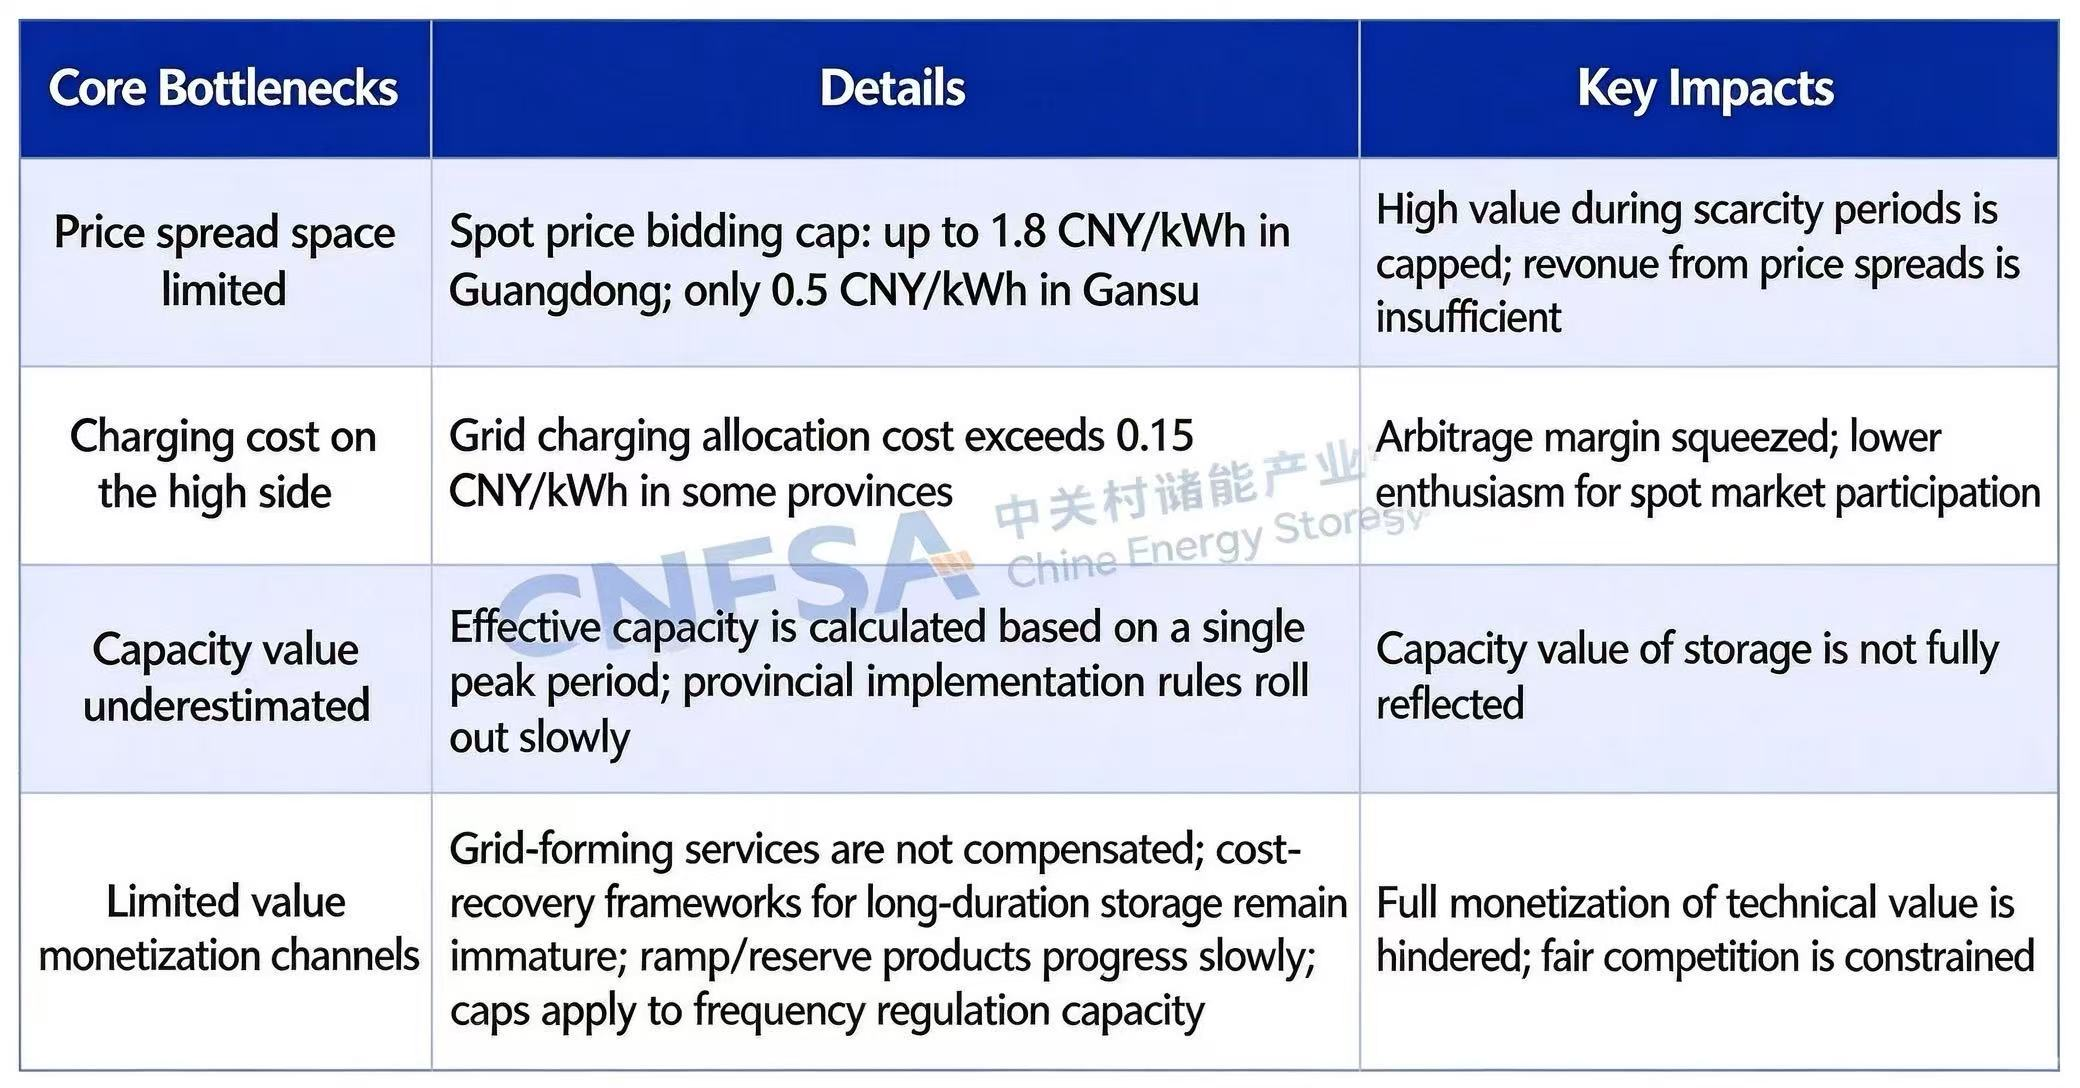
Four Major Market Mechanism Bottlenecks for Stand-Alone Energy Storage | Source: CNESA
Customer-side storage must shift toward multi-market stacked revenue models, yet green-power direct-connection and virtual-power-plant deployments encounter multiple barriers: volatile load-dependent revenues, limited market-product access for VPPs, high forecasting-driven operational risks and incomplete equipment-and-site standards creating safety concerns.
Market Trends: Elevated Strategic Status and Accelerating Power-System Reform
New-energy-storage has advanced from technical-demonstration status to become a core flexible resource for China’s new power system, with successive upward revisions to medium-and-long-term capacity targets:
· 2021: > 30 GW new-energy-storage by 2025
· 2025: > 180 GW new-energy-storage by 2027
· 2026: > 300 GW new-energy-storage by 2030
High-penetration wind-and-solar integration creates sustained structural demand for storage flexibility. CNESA’s dual-modelling outlook (double S-curve plus system-dynamics simulation) forecasts cumulative new-energy-storage power capacity of 365-435 GW by 2030, rising to 527-615 GW by 2035. Decommissioning volumes will generate replacement-equipment demand through the 16th Five-Year-Plan period.
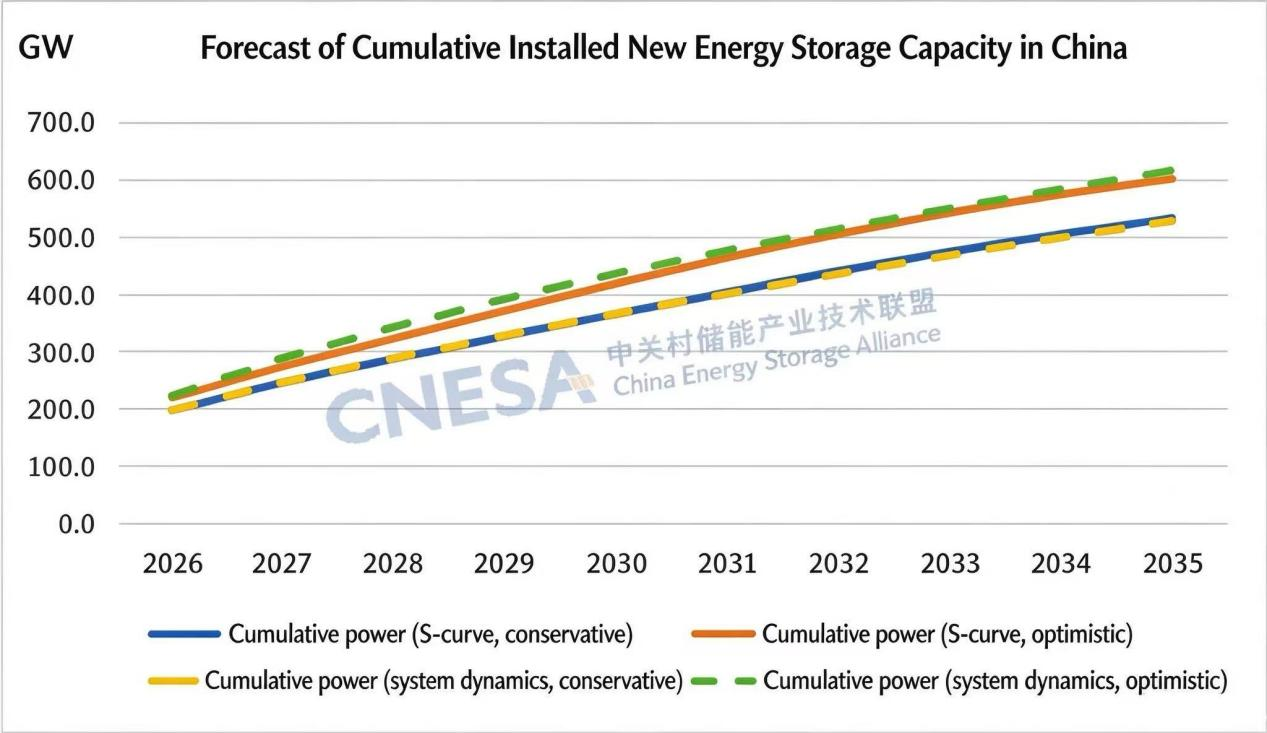
Forecast of Cumulative Installed New Energy Storage Capacity in China, Unit: GW | Source: CNESA
Major national policy documents mark the decisive shift from policy-mandated build-out to market-led growth. Circular 136 removes mandatory pairing as a grid-connection precondition for renewable-energy projects. Circular 114 establishes a national-level capacity-tariff pathway for stand-alone grid-side storage. Updated market rules reform time-of-use pricing and upgrade green-power direct-connection frameworks, while setting clear VPP capacity milestones. Multiple provinces are rolling-out complementary local measures covering spot-market trading, ancillary-service varieties and provincial-level capacity-compensation schemes aligned with national guidance.
Proposed Solutions: Building Multi-Stream Revenue Mechanisms for Storage
CNESA puts forward six policy recommendations to enable the target “capacity remuneration + spot-market income + ancillary-service payment” multi-revenue business model:
1. Refine spot-market price boundaries and push end-users toward spot-indexed tariffs; optimise grid-charge rules to reduce storage operating expenses.
2. Improve dispatch frameworks: permit “renewables + storage” market-entity participation, allow qualified legacy paired-storage assets to convert to stand-alone status, relax grid-power-purchase restrictions and introduce national emergency-dispatch compensation.
3. Enhance capacity-tariff implementation: roll-out provincial detailed rules, adopt time-differentiated effective-capacity assessment, pilot long-duration-storage long-term capacity agreements and progress toward a unified national capacity market.
4. Expand ancillary-service product portfolios including ramp and reserve services; lift frequency-regulation bidding-capacity caps and monetise grid-forming services such as virtual inertia and black-start capability.
5. Support customer-side-storage business-model development: enable re-matching of green-power-direct-connection assets when local loads decline, lower VPP-aggregator entry barriers for multi-market participation.
6. Establish full-lifecycle safety standards; link safety-audit outcomes to market access and capacity-remuneration to build “inspection – rating – revenue” positive incentives.
Strategic Value: Beyond Project Returns — Storage as a Pillar of the New Power System
New-energy-storage delivers peak-shaving, fluctuation-smoothing, inertia and reserve services that stabilise power-system operation amid rising shares of variable renewable generation. It enables wind and solar assets to operate as dispatchable resources and underpins China’s carbon-neutrality transition. National 15th-Five-Year-Plan energy documents clearly define the distinct functional roles of storage across different power-system layers.
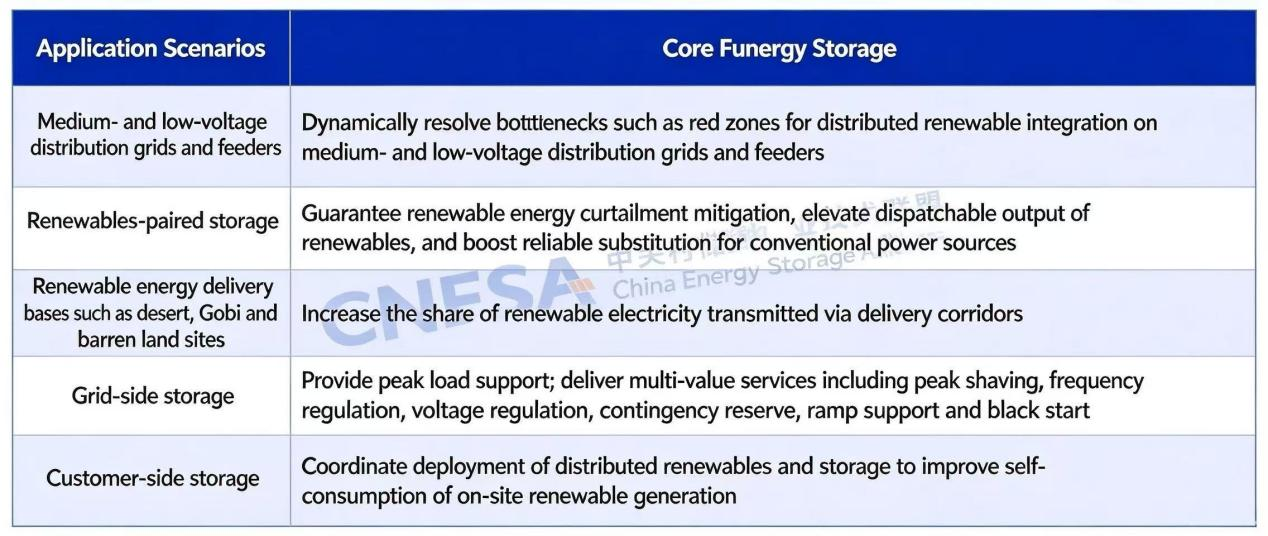
Roles of New Energy Storage within the New Power System | Source: CNESA
Conclusion
Competition in China’s energy-storage sector has moved on from pure installed-capacity racing toward system-value competition. The industry must move past policy-driven expansion and construct complete market-based value-realisation mechanisms that fairly compensate storage for safety, flexibility and economic benefits. This market transition shapes both domestic-industry quality and the operational efficiency of China’s high-renewable-penetration power system.
Contributor: Ran Ze
China’s New Energy Storage Installations Catch Up With 2025 Levels In First Three Quarters; Long-Duration Non-Lithium Storage Projects See Concentrated Commissioning
BEIJING, October 14, 2026
China Energy Storage Alliance (CNESA) has released its latest monthly market assessment for China’s new energy storage sector, showing total newly-commissioned capacity hit 35.30 GW / 102.31 GWh across the first nine months of 2026, broadly matching full-year prior-year performance. After a market correction in H1 2026, the third quarter delivered a strong rebound, driven primarily by stand-alone grid-side energy storage and large-scale long-duration storage assets entering commercial operation.
September marked a turning-point month: newly commissioned new energy storage reached 4.33 GW / 14.08 GWh, rising 42 % year-on-year on power capacity and 69 % on energy capacity, alongside 8 % and 14 % sequential month-over-month growth for power and energy respectively. Q3 total installations surpassed 10 GW for the first time on a quarterly basis, landing at 13.4 GW / 43.0 GWh. While power capacity for the January-September period dipped 3 % year-on-year, energy capacity advanced 6 % versus 2025, signalling larger-duration systems gaining market share.
“Stand-alone energy storage has become the core engine for China’s storage market recovery, as provincial power market reforms open viable revenue pathways for grid-connected storage assets,” said a senior analyst at CNESA. “We are observing an inflection point: long-duration non-lithium technologies are moving beyond demonstration projects toward real-world deployment, even as lithium-iron-phosphate batteries remain the workhorse of the industry. Market expansion will continue to hinge on the roll-out of local electricity market rules and capacity compensation frameworks.”
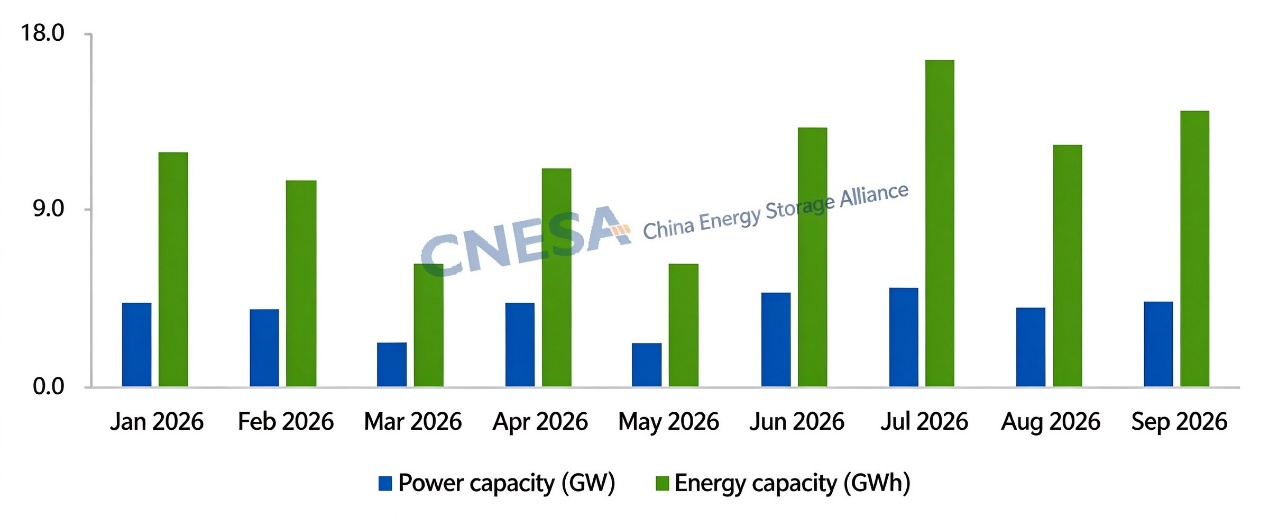
Figure 1 Newly Commissioned Capacity of New Energy Storage Projects in China, September 2026
Data source: CNESA DataLink Global Energy Storage Database
Note: Year-on-year comparison contrasts figures with the same period of the previous year; month-on-month comparison contrasts figures with the immediately preceding statistical period.
Grid-side stand-alone storage accounted for 85.3 % of September’s newly added power capacity at 3.70 GW /12.29 GWh, with power-capacity growth of 112 % year-on-year. Market reforms across multiple provinces are enabling multi-market participation for stand-alone storage assets. Southern China allows stand-alone storage to take part in both frequency-regulation and spot electricity markets; Zhejiang has implemented a breakthrough mechanism allowing daily switching between energy and frequency-regulation market participation, progressively closing the market-oriented profitability loop for stand-alone storage.
Power-side new-energy paired storage saw slower growth, while customer-side deployments continued a downward trend, with industrial-and-commercial storage making up 95.7 % of customer-side additions.
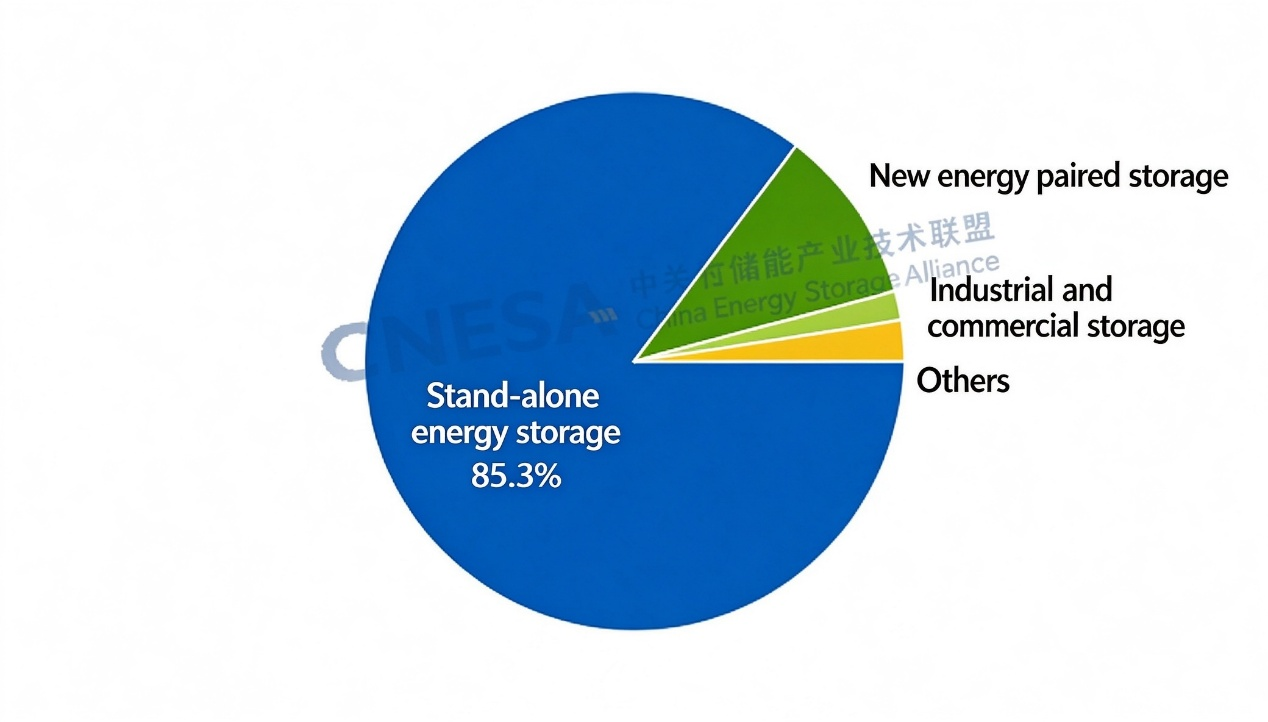
Figure 2 Application Distribution of Newly Commissioned New Energy Storage Projects in September 2026 (Share by Power Capacity)
Data source: CNESA DataLink Global Energy Storage Database
Note: Others include distribution network side, transformer districts, demonstration & research projects, thermal power coupled storage, EV charging stations, rail transit, port shore power, municipal authorities / critical facilities, data centers, etc.
Regional deployment has grown more balanced. North China led September additions with 1.46 GW power capacity, representing 34 % of national volume, followed by East China at 28 %. Guangdong ranked No. 1 for newly-added power capacity (0.83 GW), and Jiangsu topped national energy-capacity rankings (2.86 GWh), boosted by commissioning of the Jintan Salt Cavern Compressed-Air Energy Storage Phase II project. Analysts note that despite strong local demand, Jiangsu still awaits formal launch of its provincial electricity spot market and finalised capacity-compensation provisions for energy storage, creating uncertainty for future project returns.
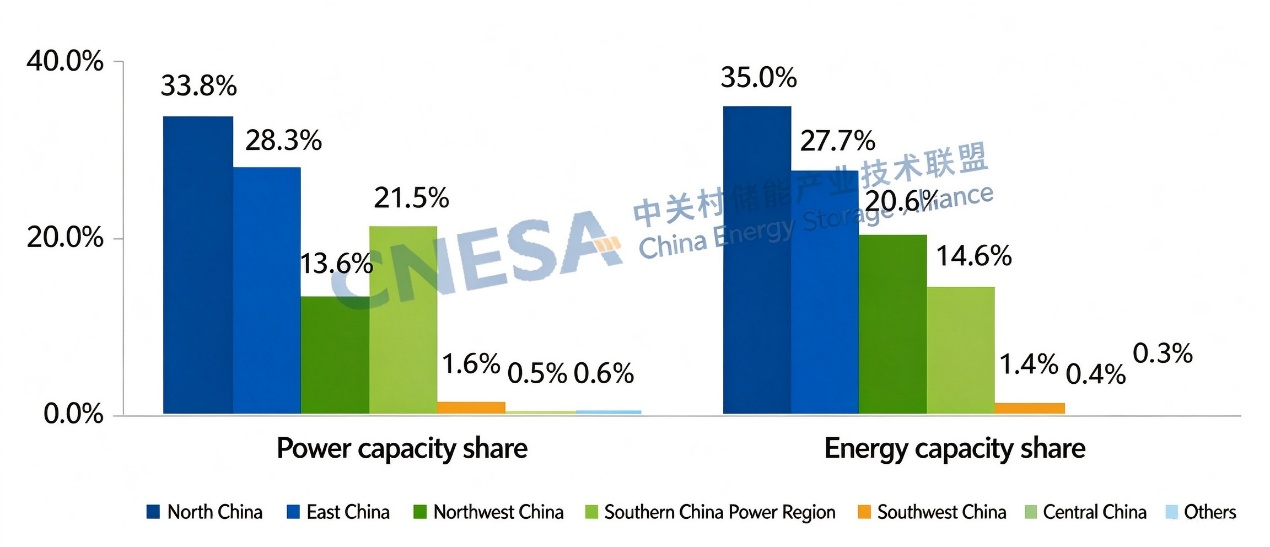
Figure 3 Regional Distribution of Newly Commissioned New Energy Storage Projects in China, September 2026
Data source: CNESA DataLink Global Energy Storage Database
Note: Southern China Power Region covers Guangdong, Guangxi, Guizhou, Hainan and Yunnan; Others include Jilin and Taiwan.
At provincial level, significant gaps exist in project scale among provinces.
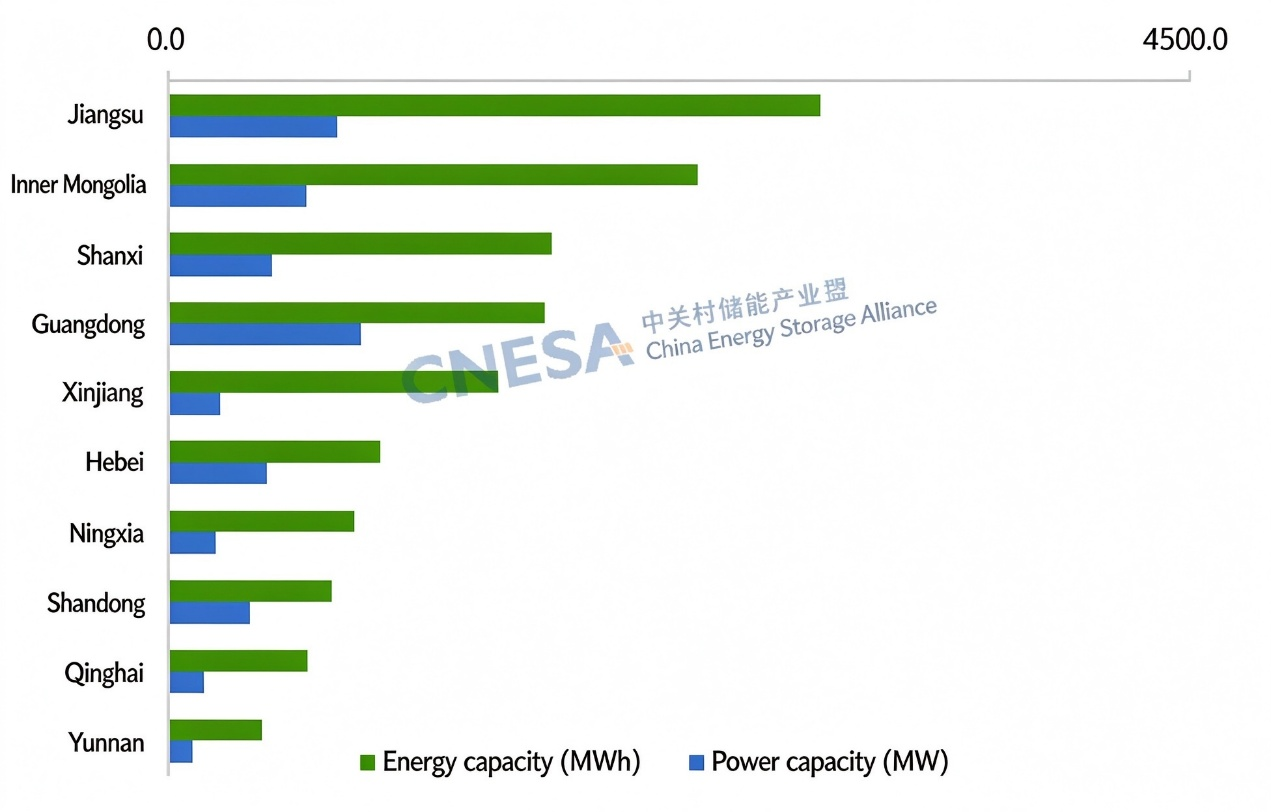
Figure 4 Top 10 Provinces for Newly Commissioned New Energy Storage Projects in China, September 2026 (Ranked by Energy Capacity)
Data source: CNESA DataLink Global Energy Storage Database
Technically, lithium-iron-phosphate batteries still represented 73.08 % of September’s commissioned power capacity. Non-lithium long-duration energy storage captured 23.6 % of monthly power additions, with landmark assets coming online including large-scale compressed-air energy storage facilities, vanadium-redox and iron-chromium flow-battery parks, and multi-technology hybrid demonstration sites. The data confirms a complementary multi-technology landscape is emerging, without near-term full replacement of lithium-based systems.
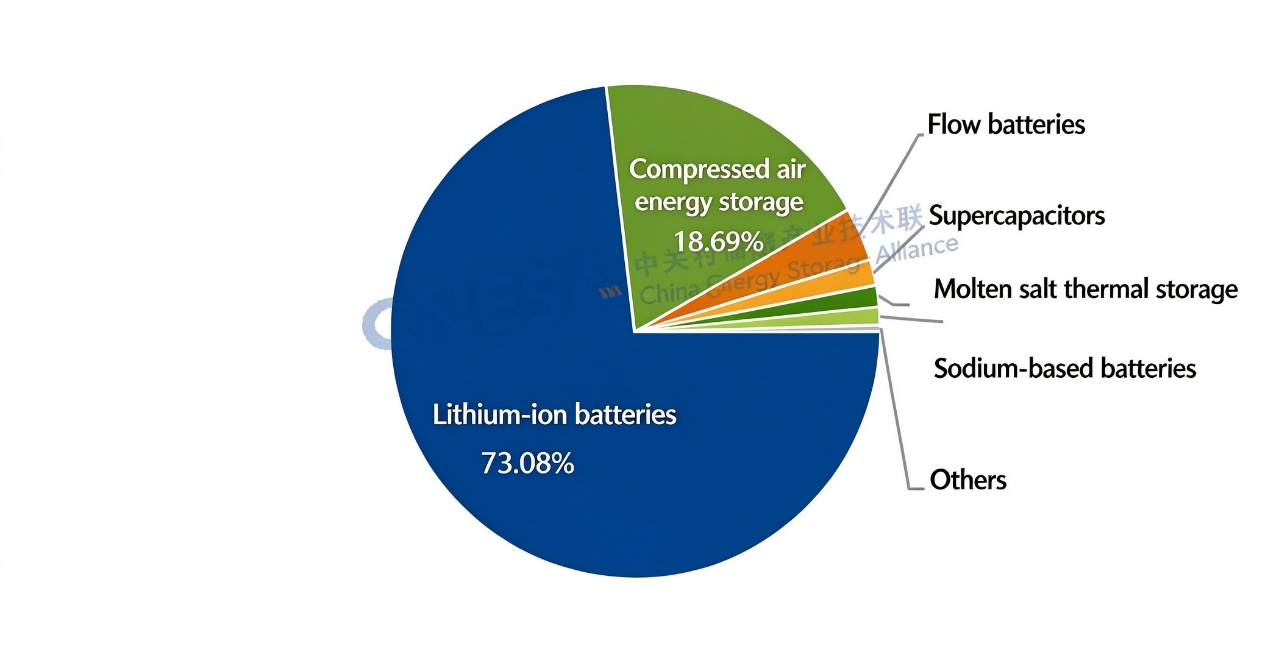
Figure 5 Technology Distribution of Newly Commissioned New Energy Storage Projects in China, September 2026 (Share by Power Capacity)
Data source: CNESA DataLink Global Energy Storage Database
Note: Others include lead-acid batteries and fuel cells.
Key take-aways from CNESA analysis
1. Q3 reversed H1 market softness; stand-alone storage business-model maturity is the primary growth driver, subject to provincial electricity-market rule implementation timelines.
2. Long-duration storage is transitioning from demonstration to early commercial deployment; LFP remains the mainstream baseline technology, with complementary multi-technology mix taking hold.
3. Regional policy divergence creates market variance: high-demand provinces such as Jiangsu depend on completed market-mechanism roll-out to unlock full project revenue potential.
Data cited is sourced from CNESA DataLink Global Energy Storage Database. Figures represent incomplete statistics of newly-commissioned new-energy-storage projects within mainland China.
Two Japan AI Compute Deals in One Day: Osaka's KIX15 Breaks Ground, Tokyo's TOK1 Adds USD 1 Billion
On October 7, Japan's AI compute market saw two investments land in a single day: MC Digital Realty started construction of the KIX15 data center in Osaka, and AirTrunk added USD 1 billion to the TOK1 campus east of Tokyo for liquid cooling deployment. The two projects differ in scale and route, yet both treat liquid cooling as the foundational solution for high-density AI workloads. Energy storage is becoming part of the supporting infrastructure of AIDC.
1. KIX15: Liquid Cooling Reserved at the Design Stage of a New Campus
On October 7, MC Digital Realty, a 50/50 joint venture between Digital Realty and Mitsubishi Corporation, officially started construction of the KIX15 data center at its KIX campus in Ibaraki City, Osaka Prefecture. With an IT capacity of 24 MW, the project is scheduled for commissioning in Q4 2028. As the fifth data center at the KIX campus, KIX15 will bring the joint venture's data centers operating in Japan to ten, with a combined IT capacity of about 220 MW. The project adopts a hybrid air- and liquid-cooling scheme, with liquid cooling reserved at the design stage to accommodate mid- and long-term AI compute expansion. Included in the "Kansai AI Infrastructure Co-Creation Project", it serves hyperscale cloud providers, cloud service providers, and enterprises building their own AI compute capacity. With relatively ample land and power resources, the Kansai region has become the main landing point for foreign capital building compute clusters in western Japan.
2. TOK1: Liquid Cooling Retrofit for an Existing Hyperscale Campus
On the same day, AirTrunk, backed by Blackstone, announced an additional investment of USD 1 billion in its TOK1 campus in Inzai City, Chiba Prefecture, to deploy liquid cooling systems supporting high-density AI compute loads. TOK1 has a total capacity of more than 300 MW. The investment is matched by a USD 1 billion green loan led by Sumitomo Mitsui Banking Corporation, MUFG Bank, and United Overseas Bank. AirTrunk CEO Robin Khuda said TOK1 aims to become Japan's first large-scale AI compute campus; driven by geopolitical factors, a growing number of North Asian customers are choosing to locate their compute capacity in Japan.
3. Two Construction Routes, One Shared Signal
The two projects represent two approaches to building compute capacity in Japan. KIX15 is a greenfield campus with liquid cooling reserved from the design stage for long-term expansion; TOK1 is a retrofit of an existing campus, where liquid cooling upgrades will convert data halls originally serving general cloud business into AIDC, putting built assets to use and shortening the time to service. Different routes, one shared signal: as rack power density keeps rising, traditional air cooling can no longer support large-scale GPU clusters, and liquid cooling is shifting from an optional extra to a threshold requirement for high-density AIDC.
4. Japan as a North Asian Compute Node: Opportunities and Constraints
Japan is fast becoming an important alternative node for compute in North Asia. In the past, overseas cloud providers and compute service providers expanding in Asia preferred Singapore and Malaysia; today, geopolitics, compliance, and low seismic risk are steadily raising Japan's appeal. But the flip side of capital inflows is real constraint: Japan faces its own pressures on power supply, energy consumption approvals, and land costs. New AI compute projects generally need more than two years of construction; when this batch of projects comes online around 2028, the market's supply-demand landscape will change markedly.
5. CNESA Observation: Beyond Cooling, Power Supply and Backup Needs Rise in Tandem
Liquid cooling addresses thermal management, but high-density AI data halls are raising requirements for power supply reliability, emergency backup, and green power support at the same time, needs that energy storage is positioned to serve. UPS-integrated storage, data center backup power, and battery energy storage systems that participate in grid regulation are gradually becoming part of the supporting infrastructure of AIDC; with power supply tight in Japan, the urgency is even greater. For China's industries, both the liquid cooling and energy storage supply chains stand to win follow-on orders from the wave of overseas compute construction.
LG Electronics Wins 5 GW Chiller Framework Deal in North America: Data Center Cooling Enters Full-Chain Competition
On October 5, LG Electronics announced a long-term chiller supply framework agreement with North American infrastructure platform AIR Control Concepts, covering large AI data center projects in the United States and Canada with a combined capacity of more than 5 GW. This is not a single-site equipment order but a supply arrangement spanning multiple projects and multiple years. The China Energy Storage Alliance (CNESA) notes that rapid GPU power iterations are turning data center cooling from a supporting function into a capacity constraint for AI infrastructure, and thermal management and energy storage are rising in tandem within AIDC infrastructure.
1. What 5 GW Means
Measured against the 50-100 MW IT loads of medium-sized AI data centers in China, 5 GW equates to the cooling capacity of fifty to sixty, or even over a hundred, medium-sized data halls, close to the cooling volume of a core-city compute cluster. The partner, AIR Control Concepts, is a North American infrastructure platform spanning HVAC, electrical, and controls businesses, integrating more than 50 operating companies and over 3,500 technical staff, with long-standing involvement in North America's core data center clusters and top-tier global operators among its customers. A long-term framework agreement with such a platform marks the formal entry of LG chillers into North America's mainstream AI data center supply chain. The order momentum is backed by figures: in the first half of 2026, LG's data center cooling solution orders reached USD 428 million, and the company expects total orders for the year to reach the "billions of dollars" level; the earlier target of KRW 1 trillion (about USD 680 million) in chiller revenue for 2027 is likely to be met ahead of schedule at the current pace.

2. Where the Heat Comes From: Chip Power Pushes Air Cooling to Its Limit
The North American data center cooling market is about USD 9.35 billion in 2026, close to 40% of the global total; within it, the AI thermal management segment is growing at a compound annual rate of about 22%, among the fastest in the data center industry. The root cause is chip power: a single Blackwell-architecture GPU now has a thermal design power (TDP) of 1,000 W, and the next generation could approach 1,400 W. Once rack power density exceeds 200 kW, traditional air cooling can no longer hold, and liquid cooling moves from an option to a must. For liquid cooling to scale, retrofitting campus chiller plants is an unavoidable prerequisite: of the roughly USD 725 billion in combined 2026 capital expenditure by the four major North American cloud providers, about 75% is going to AI infrastructure, and cooling is a hard requirement within it. The division of labor is clear: chillers are the campus-level source of cooling, producing chilled water and ultimately rejecting heat outdoors, while CDUs (coolant distribution units) are the rack-level hub, connecting the chiller's chilled-water loop on one side and server cold plates on the other, precisely controlling the temperature, pressure, and flow of the coolant on the chip side.
3. LG's Three Steps
First, aligning with chipmakers' standards. This year, LG's 600 kW, 1 MW, and 2.6 MW CDUs successively passed NVIDIA infrastructure qualification, and the 2.6 MW CDU entered the first batch of the NVIDIA DSX Ready list, effectively NVIDIA's official entry threshold for AI factory infrastructure, granting seamless integration with NVIDIA compute cluster reference architectures. Verification of the 4 MW CDU is underway, and LG has also become a preferred partner for NVIDIA power and cooling solutions.
Second, moving capacity forward. On October 1, LG announced a new chiller and CDU production base in Virginia, USA, alongside capacity expansion at its Changwon and Pyeongtaek plants in Korea, forming a three-base layout across the US and Korea to shorten delivery cycles for North American projects and meet local supply chain requirements.
Third, expanding its footprint. Beyond North America, data center cooling projects in the Middle East and Indonesia are advancing in parallel; drawing on synergies across the group's electronics, HVAC, and energy divisions, LG aims to move from a single-product supplier to an end-to-end data center thermal management solution provider.
4. The Logic of the Cooling Business Has Changed: From Support to Capacity (CNESA Observation)
A few years ago, data center cooling was a supporting business where vendors competed on energy efficiency ratio, price, and delivery time. That logic is being rewritten: whether a vendor can keep pace with GPU power iterations, align with chipmakers' standards, and withstand heat densities of several hundred kilowatts per rack is now the ticket to entry. Customers no longer ask for single products but for complete solutions from chip cold plates to campus chiller plants, making full-chain integration the dividing line. Notably, LG appears in both the energy storage and CDU columns of the NVIDIA DSX Ready partner list: power supply and cooling are equally hard requirements for high-density AIDC, and cooling and energy storage are both becoming capacity constraints in AI infrastructure. Only vendors whose capacity and service networks span the global market can capture this wave of demand.
10C Ultra-High Rate + Extreme Fire Test: Shuangdeng DP60 AIDC Lithium System Launched Overseas
Shuangdeng Group has confirmed its participation in the 15th Energy Storage International Summit and Exhibition (ESIE 2027). The company will present its annual new products and full-scenario solutions, and cordially invites industry colleagues to gather for the annual global energy storage event!
As the global AI computing wave surges forward, high pulse load impacts, high-density rack deployment, and 24/7 uninterrupted computing output mean that the demands of AIDC scenarios on backup power storage have long surpassed basic stable power supply, forcing the industry to redefine the safety boundaries and performance ceilings of systems.
On September 30, Shuangdeng Group officially launched the DP60 high-rate AIDC lithium system overseas. As a new-generation high-power energy storage backup product built for AI computing centers, DP60 relies on a full-chain safety architecture and breakthrough extreme performance to build a solid, reliable energy foundation for AIDC computing-electricity coordination.
Safety is the bottom line of computing energy storage, and the core origin of DP60's development.
At the launch event, Shuangdeng publicly presented the results of an extreme large-scale fire test of the DP60 system under the UL 9540A framework. The test abandoned ideal laboratory conditions, reproducing 1:1 real boundary conditions of a machine room - 100% SOC fully charged, zero-spacing dense rack arrangement, and enclosed heat accumulation - and fully reproducing the complete thermal runaway process of the cells. The measured results showed that thermal runaway and open flames were strictly confined within a single cabinet, with no cross-cabinet fire spread, no explosion risk, no high-voltage arcing, and no re-ignition after the test; all assessment indicators passed in one go.
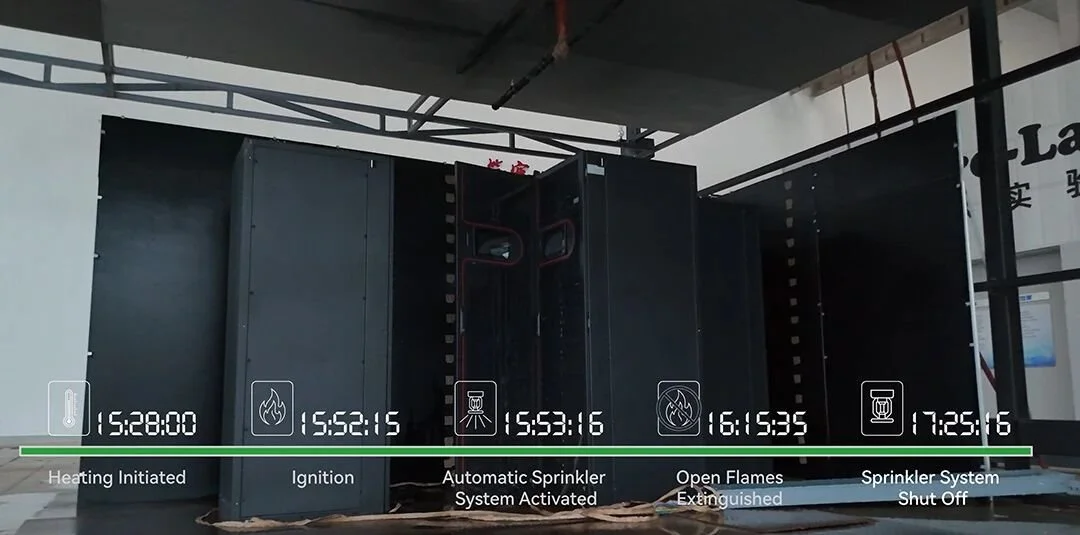
Beyond safety, DP60 comprehensively resets the performance benchmark of AIDC energy storage backup, achieving coordinated breakthroughs in three dimensions - power, space, and lifecycle:
10C ultra-high-rate discharge: millisecond-level response to computing power spikes
The system responds at the millisecond level to pulsed high-power loads brought by large model training, withstands instantaneous power impacts, keeps computing clusters continuously online under drastic load fluctuations, and easily adapts to the dynamic power throughput characteristics of AI business.
Extreme power density: releasing core space value of the machine room
A single cabinet occupies only 0.48 square meters, with a maximum output power of 630 kW and a power density of 1,312.5 kW per square meter. In intelligent computing machine rooms where space is at a premium, it sharply compresses the area taken by backup power systems, freeing more cabinet resources for computing deployment and effectively reducing data center infrastructure investment.
Ultra-high power and simplified link design: long-term stable operation
The system adopts large-capacity ultra-high-rate single cells and simplified series-parallel links, reducing electrical connection nodes, lowering system failure probability, and improving on-site integration and O&M efficiency. It matches the development needs of computing business over the long term, maximizing the full-lifecycle value of the equipment.
From the foundation of telecom energy storage to the main track of AIDC energy storage, Shuangdeng insists on starting from real scenarios rather than conceptual technology deductions, putting products through validation under extreme operating conditions. Every fire test and every round of reliability validation is, in essence, a solemn commitment to the safety of customer assets.
In the computing era, the reliability of the energy foundation determines the ceiling of the digital world. The DP60 high-rate AIDC lithium system integrates safety, power, and space efficiency, providing global intelligent computing centers with energy storage backup solutions that combine high performance and high safety, and supporting the high-quality deployment of green computing infrastructure.
At the launch site, the Shuangdeng team held in-depth exchanges with overseas customers, design institutes, and system integrators, conducting focused discussions on core topics such as global AIDC safety compliance standards, localization adaptation of overseas projects, and optimization of computing-storage coordination architectures, working with industry partners to empower the sustainable development of AIDC energy.
In the future, Shuangdeng will continue to deepen its presence in the AIDC energy storage track, leveraging full-industry-chain self-developed manufacturing capabilities to continuously refine product safety and performance, and building a safe, efficient, and sustainable computing-storage ecosystem with industry partners.
Abu Dhabi Raises 2035 Energy Storage Target to 15 GW: PV-Storage and AI Computing Drive Growth in Tandem
In September 2026, the Emirates Water and Electricity Company (EWEC) released its latest long-term plan: up to 15 GW of battery energy storage and more than 35 GW of solar PV capacity in Abu Dhabi by 2035. PV-storage pairing on the energy transition side, and new high-reliability power supply demand from AI data centers. Chinese energy storage companies have already secured orders across several links.
1. A Three-Step Target Raise: Over 35 GW Solar and Up to 15 GW Storage by 2035
Abu Dhabi's capacity targets have been raised repeatedly: the 2035 solar target set in 2024 was 18 GW, raised to over 30 GW in May 2026, and raised again in September 2026 to over 35 GW, together with a storage goal of up to 15 GW set for 2035 for the first time. On the interim timeline, the 2030 solar target stands at 14 GW, meaning at least 21 GW more must be added between 2031 and 2035. As Abu Dhabi's sole purchaser and supplier of electricity and water, EWEC stated that as this advanced capacity comes online, the flexibility contribution of gas-fired generation is expected to decline, and storage will take on the main balancing role.
2. Flagship Project First: 5.2 GW Solar + 19 GWh Storage
Abu Dhabi's storage expansion is not confined to planning. Local energy giant Masdar and EWEC are jointly developing a flagship project pairing 5.2 GW of solar PV with 19 GWh of battery storage, designed to deliver 1 GW of continuous renewable power. Construction began in 2025, with commercial operation targeted for 2027. The project involves a total investment of more than AED 22 billion, is expected to create about 10,000 jobs, and will cut about 5.7 million tonnes of CO2 emissions annually. It marks Abu Dhabi's shift from "solar mainly for daytime generation" to "large-scale PV paired with storage to provide dispatchable renewable power". Chinese companies are deeply involved: BYD Energy Storage signed an 11.275 GWh storage system supply agreement featuring 2,710 Ah blade cells; Sungrow secured a 7.5 GWh storage order in the north zone plus a 2.6 GW PV inverter supply agreement; and PowerChina signed the EPC contract for the 2.1 GW + 7.75 GWh RTC solar-storage project, worth about RMB 13.962 billion. Beyond utility-scale projects, Abu Dhabi is also extending into distributed markets: a PV-plus-storage self-consumption policy for agriculture was launched in February 2026 and extended to residential users in April.
3. Emissions Main Line: Power and Water Carbon Emissions Down Over 45%
These moves serve Abu Dhabi's broader emissions reduction goals. EWEC projects that total carbon emissions from power and water production will fall from about 42 million tonnes in 2019 to about 23 million tonnes by 2035, a reduction of more than 45%. Solar power, battery storage, and reverse osmosis desalination are identified as the three core drivers.
4. AIDC: The Second Growth Curve for Storage
The sharp raise of Abu Dhabi's storage targets is closely tied to the region's fast-moving AI data center buildout. In the desert west of Abu Dhabi, a planned "UAE-US AI campus" covering about 26 square kilometers is under construction. Led by UAE artificial intelligence company G42, its first phase, "Stargate UAE", plans a USD 30 billion investment to build a 1 GW compute cluster, with the first 200 MW expected to enter service in 2026. According to Reuters, changes in the regional security situation may shift the project from a single large campus to multiple sites across the UAE, with studies on protective measures such as building some facilities underground or inside mountains and deploying air defense systems and electronic jamming equipment; G42 said the project is "on track".
The power characteristics of AI loads explain exactly why storage is being added in tandem. Unlike traditional data centers, AI training and inference clusters show large, fast power fluctuations, with far higher requirements for supply continuity and power quality than general loads. Khalid, the storage procurement lead of the RTC project, said the project explicitly requires storage to serve both PV peak regulation and the backup needs of nearby new AIDC computing parks; the differing load characteristics of the two forced the drawings to be redone at the design stage. Green power compliance requirements are also driving storage attachment: the UAE requires new large computing projects to use at least 60% green power, and since PV cannot supply stable power around the clock, storage becomes the hard carrier of compliance. Large computing projects without their own storage typically wait three to five years in the municipal grid connection queue, while adding storage reduces reliance on grid expansion. Acceptance standards likewise reflect the special requirements of computing loads: storage PCS power response must be within 10 milliseconds, annual system availability must reach 99.999%, and all suppliers must complete tens of thousands of load impact simulation tests at local laboratories in Abu Dhabi before entering the site. Institutionally, in January 2026 Abu Dhabi announced plans for a dedicated electricity tariff mechanism for AI data centers, offering globally competitive prices to hyperscale data centers.
For Chinese energy storage companies, AIDC scenarios are reshaping the competitive threshold of overseas utility-scale storage projects: response speed, availability, and simulation validation are becoming new entry tickets. The combined "PV + storage + computing" demand in the Middle East is opening new space for storage applications.
Source material: EWEC's plan and public reports by Reuters and other media
Energy Storage Becomes Core Infrastructure: Three-Layer AIDC Power Architecture Points to 209 GWh of Data Center Storage by 2030
As large-model training and inference scale up, power consumption at AI compute clusters keeps climbing, and the role of energy storage in AI data center (AIDC) campuses is undergoing a fundamental shift—from an optional backup device to core infrastructure that underpins stable compute operations. The logic behind this shift lies in the layering of the power architecture: the white, grey and green zones correspond to regulation needs at the millisecond, minute and hour levels respectively, and energy storage product portfolios are being restructured accordingly.
1. White, Grey and Black Zones: Storage Matched to Each Layer
A large AIDC campus can be divided, from the inside out, into three zones, each imposing distinct technical requirements on energy storage. The white zone sits inside the server racks, where CBUs and BBUs together absorb the millisecond-level power transients generated by GPUs; products there must deliver both high power density and moderate energy density. The grey zone lies at the power distribution side of the machine rooms, where 800 V high-voltage direct current (HVDC) systems are gradually replacing conventional UPSs; storage units connect directly to the 800 V DC bus and, beyond basic backup duty, participate in peak shaving and demand response. The green zone sits at the interface between the campus and the public grid, where long-duration storage and grid-forming storage smooth the output fluctuations of wind and solar power, keep compute supply uninterrupted, and provide dispatchable capacity to the grid.
The three zones operate on different timescales: milliseconds inside the racks, minutes on the distribution side, and hours at the grid connection point. AIDC energy storage is therefore no longer a single backup battery but a multi-layer combination of rack-level BBUs, machine-room BESS and campus-level storage, with diversified product forms and technology routes.
2. Market Data: The Track Enters a Phase of Acceleration
Two sets of figures—energy consumption and installed capacity—trace the growth curve. Global data center electricity consumption totaled 415 TWh in 2024 and is forecast to double to 945 TWh by 2030. In China, computing-center electricity use reached 170 billion kWh in 2025, or 1.6% of total electricity consumption, and is expected to rise to 800 billion kWh, roughly 6%, by 2030.
Energy storage installations are scaling up in tandem. Global data center storage additions grew from 4 GWh in 2020 to 16.5 GWh in 2024, a compound annual growth rate of 43.0%; industry forecasts put the 2030 figure at 209.4 GWh, lifting the 2024-2030 CAGR to 52.7%. In the first half of 2026, global shipments of lithium battery energy storage systems reached 461.3 GWh, up 71% year on year, with China leading at 202.5 GWh (up 49%) and North America and Europe up 83% and 74% respectively. AIDC storage demand is concentrated in North America, where compute clusters are densest; as overseas orders continue to flow, China’s storage supply chain stands to benefit.
3. Orders Materializing: The Fluence-EVE Long-Term Deal
The market’s acceleration is translating into concrete orders. Energy storage integrator Fluence posted revenue of USD 649.8 million in the third quarter of fiscal 2026 (ended June 30, 2026), up 7.8% year on year and nearly 40% quarter on quarter; new orders signed in the quarter topped USD 1.44 billion, and backlog rose 14% sequentially to USD 6.4 billion. Data center-related orders amounted to roughly USD 850 million, including a contract worth more than USD 500 million with a hyperscale compute operator as well as a large behind-the-meter storage order—AIDC business has become a new growth pillar for Fluence.
On the cell side, EVE Power, a subsidiary of EVE Energy, signed a battery supply framework agreement with Fluence for 2027-2031, covering a total of 206 GWh: 16 GWh committed for delivery in 2027 and 190 GWh of reserved capacity for 2028-2031. In the first half of 2026, EVE Energy shipped 44.46 GWh of energy storage batteries, up 54.88% year on year. The company says it has built backup power solutions covering the full range of AIDC scenarios, and that the long-term deal anchors a strategic partnership while securing medium- and long-term demand from overseas compute storage in advance.
4. Supply Chain and Risk Notes
Rising AIDC storage demand benefits multiple links of the industry chain: upstream, in raw materials and power electronics components, players include Ganfeng Lithium, Tianqi Lithium, Xinleineng, Actionpower and Sinofuse; midstream, in cells and power equipment, EVE Energy, Azure, Zhongheng Electric, Megmeet, Jinpan Technology and TGOOD; downstream, in system integration, Sungrow, CATL and HyperStrong.
For storage companies, the layered power architecture means product matrices must be rebuilt around timescales—millisecond-level power support, minute-level peak shaving and demand response, and hour-level long-duration regulation coexist, and no single product line can cover every scenario. Meanwhile, long-term contracts plus framework agreements are becoming the typical commercial form of overseas AIDC storage, locking in three to five years of visible demand.
Risks deserve equal attention: the pace of technology iteration in AIDC power architectures, delivery and capacity ramp-up of storage products, and the speed at which compute storage demand actually materializes at home and abroad could all fall short of expectations. Worth watching going forward are the progress of layered storage technology routes and the conversion of orders into actual deliveries.
Source material: company announcements by Fluence and EVE Energy, and public media reports
BDx Breaks Ground on 640 MW AI Campus in Indonesia: With Hydro Power and Liquid Cooling, Power-First Becomes the Main Line of Southeast Asia's Compute Race
On September 22, Singapore-based data center operator BDx Data Centers held a groundbreaking ceremony in West Java, Indonesia, for its 640 MW CGK4 AI campus. The project's significance goes beyond its scale: 845 MVA of grid capacity secured in advance, a hydro power arrangement being pursued with a state-owned water company, and direct-to-chip liquid cooling supporting racks of up to 500 kW - in Southeast Asia's AI infrastructure race, power supply capability is replacing land and site selection as the first precondition.
1. Project Profile: Six Buildings, About Three Years to Complete
The CGK4 (AI Campus 2) Jatiluhur campus is located in Purwakarta, about 5 km from the Jatiluhur Dam and about a two-hour drive from the capital, Jakarta. The project has secured 845 MVA of grid capacity from state utility PLN, and construction of the first of six planned buildings has begun; the campus is expected to be developed over about three years. The first 120 MW building is planned to enter service in early 2027, providing 120 MW of IT capacity in phases. The project adopts direct-to-chip liquid cooling designed to support racks with power demands of up to 500 kW, and holds certification under the NVIDIA DGX-Ready Managed Data Center program (April 2025). On the latest developments: Indonesian outlet Selular reported in October 2026 that West Java Governor Dedi Mulyadi requested construction be paused until approvals such as the AMDAL environmental impact analysis and the PBG building permit are complete; BDx said it is cooperating with the government, and the early-2027 target for the first phase is unchanged.
2. Power First: Grid Capacity and Hydro Supply
BDx is advancing a hydro power arrangement with state-owned water company Perum Jasa Tirta II as part of its efforts to secure low-carbon electricity for the campus. Across its three AI-focused campuses in Indonesia (CGK3/3A, CGK4, CGK5), the company has secured more than 1.2 GVA of grid capacity in total, and in 2026 obtained a USD 320 million loan facility to support its Indonesian expansion. The expansion comes as Indonesia seeks to attract more data center investment and build AI and cloud computing capabilities, with operators competing for land, power, and connectivity, especially in and around Jakarta.
3. Demand Signals and Official Statements
BDx Data Centers CEO Mayank Srivastava said Indonesia is entering a new phase of digital and AI development, and CGK4 is a long-term investment in the infrastructure this phase requires. BDx Indonesia CEO Agus Hartono Wijaya said the project will enable local companies, government agencies, and developers to run advanced AI workloads domestically. According to BDx, CGK4 has attracted interest from hyperscale cloud service providers, technology companies, AI cloud providers, and enterprises, though the company has not disclosed customers or contract values.
4. CNESA Observation: With Power as the Constraint, Space for Storage Opens Up
From the storage industry's perspective, the project sends three signals. First, 845 MVA locked in advance and more than 1.2 GVA across three campuses show that the primary constraint in campus competition is power, not land - stable supply capability directly determines whether a project can land and come online on schedule. Second, hydro direct supply is a low-carbon power path, but hydro output fluctuates seasonally, amplifying the role of campus-level storage in peak regulation and backup. Third, 500 kW racks and direct-to-chip liquid cooling mean supply reliability and thermal management requirements are rising together, making backup storage demand a certainty. For Chinese companies, the accelerating AIDC buildout in Southeast Asia opens a window for the storage and liquid cooling supply chains to go overseas; BDx has not disclosed its equipment suppliers, which is a potential entry point. As campus competition shifts from "site selection" to "power access", the toolkit for stable supply and green power assurance - storage, hydro supply, and liquid cooling - is becoming the hard requirement of AIDC infrastructure.
Source material: public information from BDx Data Centers and reports by DatacenterDynamics, Selular, and other media
Canadian Solar Eternalplanet Secures RMB 100 Million-Level Financing to Accelerate Global Expansion of EP Cube
Shenzhen Eternalplanet Energy Technology Co., Ltd. (“Eternalplanet”) recently announced the completion of a new financing round worth over RMB 100 million. The round was led by Zhengxuan Investment, with the proceeds to be primarily used for new product development, global market expansion, and supply chain enhancement.
Zhengxuan Investment is a professional investment firm focused on high-tech and innovative companies, with key investment areas including advanced manufacturing, artificial intelligence and robotics, new energy, new materials, semiconductors, and aerospace. Xia Zuoquan, Chairman of Zhengxuan Investment, is one of the co-founders of BYD.
The investment reflects Zhengxuan Investment’s confidence in Eternalplanet’s technological capabilities in residential energy storage and its ability to commercialize products across global markets.
EP Cube Gains Traction Across Global Residential Energy Storage Markets
Eternalplanet’s flagship product, the EP Cube residential energy storage system, has continued to demonstrate strong commercial traction while expanding its global footprint.
Since entering mass production in 2022, EP Cube has been launched in more than ten countries and regions, including the United States, Japan, Italy, the United Kingdom, and Germany.
In Italy and Japan, two highly competitive residential energy storage markets, EP Cube has emerged as one of the faster-growing brands in recent years. Following its market launches in the two countries in 2023 and 2024, respectively, EP Cube reached an approximately 5% market share in each market in 2025.
New Financing to Support the Next Stage of Growth
The new funding will support Eternalplanet’s next phase of development across three key areas: next-generation product R&D, global market expansion, and supply chain optimization.
The company also plans to increase investment in its AI-powered energy management platform, overseas sales and distribution channels, and localized after-sales service teams.
“Residential solar-plus-storage markets around the world are shifting from subsidy-driven growth toward value-driven growth. Product innovation will remain at the core of our competitive strategy. We will continue to pursue full-stack in-house R&D and deepen our presence in key overseas markets, including the United States, Japan and Europe. Through strong product capabilities and localized operations, our goal is to establish EP Cube as a trusted home energy system brand recognized by customers worldwide,” said Yin Shaowen, Founder and General Manager of Eternalplanet.
“As solar and energy storage become increasingly integrated, storage is emerging as a new engine of growth. Eternalplanet is focused on global markets and high-value-added businesses. We take a long-term approach, relying on strong products to navigate industry cycles while creating and sharing long-term value with our customers, employees, suppliers and investors,” said Zhuang Yan, Chairman of Eternalplanet.
About Eternalplanet
Founded in 2021, Shenzhen Eternalplanet Energy Technology Co., Ltd. is a technology company focused on integrated home energy solutions and is majority-owned by Canadian Solar Group. Its business covers R&D, manufacturing, sales, and customer service.
Its flagship EP Cube home energy storage system is now available in more than ten countries and regions worldwide. Through intelligent, safe and reliable residential energy storage solutions, Eternalplanet aims to help households achieve greater energy independence and embrace a greener, lower-carbon lifestyle.
About Zhengxuan Investment
Zhengxuan Investment is a professional investment institution focused on high-tech and innovative companies. Its key investment areas include advanced manufacturing, artificial intelligence and robotics, new energy, new materials, semiconductors, and aerospace.
New Member | Sinotrans Limited (Sinotrans): Expert in End-to-End Integrated Logistics Solutions for Energy Storage Cabinets (Copy)
Sinotrans Limited (referred to as “Sinotrans”) has recently completed its membership admission process and officially joined the China Energy Storage Alliance (CNESA) as a member organization.
I. Company Profile
Founded in 2002, Sinotrans Limited (Sinotrans) is the only nationwide specialized chemical logistics platform enterprise under China Merchants Group and Sinotrans Limited, headquartered in Shanghai.
The company's operational network covers core chemical industry clusters across China, complemented by a global chemical supply chain service system. Focused on energy chemicals and hazardous chemical-related emerging sectors, the company delivers full-chain integrated supply chain solutions, providing customers with safe, resilient, efficient, smart, and green end-to-end integrated logistics services.
The company offers full-chain service capabilities covering warehousing and transportation of dangerous goods and general chemicals, international freight forwarding, multimodal transport, and bulk chemicals. It has long served Fortune Global 500 energy and chemical companies, central and state-owned enterprises in the sector, and leading private chemical companies. Concurrently, the company is deeply engaged in emerging strategic industries, with a service footprint spanning electronics and semiconductors, new energy vehicles, power batteries, energy storage, and high-end pharmaceuticals, demonstrating multi-industry, high-standard, full-scenario integrated supply chain service capabilities.
Certified to ISO 9001, ISO 14001, and ISO 45001, the company has built a mature HSEQ safety management system, established one of China's first emergency response networks, and participated extensively in the drafting and revision of multiple national and industry standards, continuously setting new benchmarks for safe, compliant, and efficient operations in hazardous chemical logistics.
II. Core Capabilities
Nationwide and Global Network Coverage
Strategically deploying warehousing, container yards, and transport capacity nationwide, with precise coverage of key chemical parks and coastal core ports. Leveraging the mature global networks of China Merchants Group and Sinotrans Limited, the company integrates global port agency, overseas warehousing, and distribution resources to open cross-border end-to-end logistics corridors.
Standardized HSEQ Safety Management System
A 24/7 coordinated emergency response mechanism, full-process tiered risk inspection and control, dedicated contingency plans, and regular emergency drills enable high-safety operations throughout hazardous chemical logistics.
Professional Hazardous Goods Operations Teams
All staff are certified to operate, with a large pool of certified professionals in hazardous goods handling, transportation, and customs declaration. Deeply experienced in chemical and emerging-sector storage and transportation scenarios, the teams possess mature risk assessment and on-site response capabilities.
Full-Chain Compliance Qualification System
Holding complete qualifications for dangerous goods road transport, oversize cargo transport, hazardous waste transfer, and hazardous chemical warehousing, the company operates a closed-loop compliance system that fully meets the stringent regulatory requirements for dangerous goods.
Smart Digital Full-Chain Control
Self-developed integrated hazardous chemical logistics platforms and transport information management systems enable digitalized order dispatch, warehouse management, in-transit monitoring, delivery verification, and end-to-end traceability - fully visible and auditable throughout, ensuring delivery stability.
III. Full-Chain Logistics Solutions for Energy Storage Cabinets
Driven by the dual demand of domestic wind-solar-plus-storage projects and the concentrated overseas shipment of equipment, the energy storage industry has entered a period of rapid growth, with surging demand for batch deliveries of energy storage cabinets. Energy storage cabinets present industry-wide pain points - oversize and overweight dimensions, high transport difficulty, challenging lifting and securing operations, Class 9 dangerous goods characteristics, and inconsistent import/export regulations and standards across countries - which traditional logistics providers struggle to address with one-stop, safe, and compliant delivery.
To address these pain points, Sinotrans has developed a standardized, practical full-process supply chain solution for energy storage cabinets, providing one-stop coverage of the domestic and overseas delivery needs for all categories and scenarios of energy storage equipment, spanning the complete chain from domestic transport and ocean shipping to overseas last-mile delivery.
(1) Domestic Transport Services
Dual-Qualification Transport Capacity
A compliant fleet holding both Class 9 dangerous goods and oversize cargo transport qualifications, with ample batch transport capacity to meet the overweight, over-height, and over-width road transport requirements of energy storage cabinets.
Nationwide Long-Haul Trunk Transport
Rich practical experience in high-risk and extreme road conditions, including deliveries to wind-solar-plus-storage project hubs such as Tibet, Heilongjiang, and Qinghai. One-stop services cover pre-dispatch route surveys, long-distance cross-regional oversize permits, transport capacity matching for complex road conditions, and safety control for long-haul transport of lithium battery equipment, ensuring projects are commissioned on schedule.
Professional Inland Securing and Reinforcement
Multiple professional lashing and securing solutions tailored to cabinet structures and lithium battery module characteristics, effectively mitigating the risks of cabinet deformation, cell displacement, and precision component damage caused by vibration and tilting during long-haul transport.
IoT Full-Journey Visualized Safety Control
IoT-enabled visual monitoring throughout the journey, capturing real-time vehicle positioning, transport shock and vibration, and ambient temperature and humidity data, enabling full online visual control with early warnings of transport risks.
(2) Ocean Shipping Services
Hazardous Goods Warehousing and Yards at Core Ports
Dedicated dangerous goods warehousing and container yards at major outbound ports, including Shanghai, Taicang, Ningbo, and Xiamen, providing temporary storage and port consolidation services for energy storage cabinets.
Dangerous Goods Shipping Booking
Cooperative booking arrangements with shipping lines for dangerous goods, coordinating hazardous cargo capacity and supporting multiple shipping modes, including container vessels, breakbulk vessels, and heavy-lift vessels.
Export Compliance Declaration Services
A professional declaration team precisely handles document review, maritime filing and declaration, and customs clearance procedures, ensuring compliant entry of energy storage cabinets to ports.
Efficient Port Consolidation Operations
Coordinated scheduling of dangerous goods vehicles for port consolidation and direct truck-to-vessel loading.
(3) Overseas Last-Mile Delivery Services
Overseas On-Site Route Surveys
Conducting on-site surveys of overseas transport routes before project commencement to plan optimal delivery paths in advance, avoiding overseas road weight, height, and access restrictions and ensuring smooth door-to-door delivery.
Destination Port Lifting Solutions
Pre-matching lifting equipment capacity and safety regulations at destination ports, with customized lifting operation plans that avoid demurrage and cabinet damage caused by mismatched or insufficient lifting equipment.
Destination Port Clearance and Distribution
Leveraging Sinotrans Limited's overseas self-operated network and local partner resources to provide one-stop destination port customs clearance, discharge and transfer, and last-mile delivery services, covering the world's core energy storage export markets.
Cross-Border Regulatory Adaptation Support
Assisting customers in mapping destination-country certification requirements, with full compliance support from domestic transport through to overseas delivery.
(4) Value-Added Services
Insurance Coverage
Comprehensive cargo risk coverage across road transport, ocean shipping, port lifting, and yard storage, safeguarding energy storage equipment throughout the entire journey.
Green Logistics
Product carbon footprint calculation, import/export compliance consulting, and low-carbon logistics services, aligned with the green, low-carbon direction of the energy storage industry.
As domestic wind-solar-plus-storage projects are rolled out at an accelerating pace and new energy enterprises quicken their global expansion, demand for long-distance domestic transport and global bulk shipping of energy storage equipment will continue to grow. Leveraging its nationwide network, practical experience on high-difficulty routes, compliant qualified transport capacity, and global service network, Sinotrans is committed to deep collaboration and complementary synergy with energy storage enterprises, continuously delivering safe, efficient, and stable end-to-end energy storage supply chain solutions, jointly ensuring the efficient delivery of energy storage projects at home and abroad, and supporting China's new energy industry in maintaining its global leadership.
New Member | Sinotrans Limited (Sinotrans): Expert in End-to-End Integrated Logistics Solutions for Energy Storage Cabinets (Copy)
Sinotrans Limited (referred to as “Sinotrans”) has recently completed its membership admission process and officially joined the China Energy Storage Alliance (CNESA) as a member organization.
I. Company Profile
Founded in 2002, Sinotrans Limited (Sinotrans) is the only nationwide specialized chemical logistics platform enterprise under China Merchants Group and Sinotrans Limited, headquartered in Shanghai.
The company's operational network covers core chemical industry clusters across China, complemented by a global chemical supply chain service system. Focused on energy chemicals and hazardous chemical-related emerging sectors, the company delivers full-chain integrated supply chain solutions, providing customers with safe, resilient, efficient, smart, and green end-to-end integrated logistics services.
The company offers full-chain service capabilities covering warehousing and transportation of dangerous goods and general chemicals, international freight forwarding, multimodal transport, and bulk chemicals. It has long served Fortune Global 500 energy and chemical companies, central and state-owned enterprises in the sector, and leading private chemical companies. Concurrently, the company is deeply engaged in emerging strategic industries, with a service footprint spanning electronics and semiconductors, new energy vehicles, power batteries, energy storage, and high-end pharmaceuticals, demonstrating multi-industry, high-standard, full-scenario integrated supply chain service capabilities.
Certified to ISO 9001, ISO 14001, and ISO 45001, the company has built a mature HSEQ safety management system, established one of China's first emergency response networks, and participated extensively in the drafting and revision of multiple national and industry standards, continuously setting new benchmarks for safe, compliant, and efficient operations in hazardous chemical logistics.
II. Core Capabilities
Nationwide and Global Network Coverage
Strategically deploying warehousing, container yards, and transport capacity nationwide, with precise coverage of key chemical parks and coastal core ports. Leveraging the mature global networks of China Merchants Group and Sinotrans Limited, the company integrates global port agency, overseas warehousing, and distribution resources to open cross-border end-to-end logistics corridors.
Standardized HSEQ Safety Management System
A 24/7 coordinated emergency response mechanism, full-process tiered risk inspection and control, dedicated contingency plans, and regular emergency drills enable high-safety operations throughout hazardous chemical logistics.
Professional Hazardous Goods Operations Teams
All staff are certified to operate, with a large pool of certified professionals in hazardous goods handling, transportation, and customs declaration. Deeply experienced in chemical and emerging-sector storage and transportation scenarios, the teams possess mature risk assessment and on-site response capabilities.
Full-Chain Compliance Qualification System
Holding complete qualifications for dangerous goods road transport, oversize cargo transport, hazardous waste transfer, and hazardous chemical warehousing, the company operates a closed-loop compliance system that fully meets the stringent regulatory requirements for dangerous goods.
Smart Digital Full-Chain Control
Self-developed integrated hazardous chemical logistics platforms and transport information management systems enable digitalized order dispatch, warehouse management, in-transit monitoring, delivery verification, and end-to-end traceability - fully visible and auditable throughout, ensuring delivery stability.
III. Full-Chain Logistics Solutions for Energy Storage Cabinets
Driven by the dual demand of domestic wind-solar-plus-storage projects and the concentrated overseas shipment of equipment, the energy storage industry has entered a period of rapid growth, with surging demand for batch deliveries of energy storage cabinets. Energy storage cabinets present industry-wide pain points - oversize and overweight dimensions, high transport difficulty, challenging lifting and securing operations, Class 9 dangerous goods characteristics, and inconsistent import/export regulations and standards across countries - which traditional logistics providers struggle to address with one-stop, safe, and compliant delivery.
To address these pain points, Sinotrans has developed a standardized, practical full-process supply chain solution for energy storage cabinets, providing one-stop coverage of the domestic and overseas delivery needs for all categories and scenarios of energy storage equipment, spanning the complete chain from domestic transport and ocean shipping to overseas last-mile delivery.
(1) Domestic Transport Services
Dual-Qualification Transport Capacity
A compliant fleet holding both Class 9 dangerous goods and oversize cargo transport qualifications, with ample batch transport capacity to meet the overweight, over-height, and over-width road transport requirements of energy storage cabinets.
Nationwide Long-Haul Trunk Transport
Rich practical experience in high-risk and extreme road conditions, including deliveries to wind-solar-plus-storage project hubs such as Tibet, Heilongjiang, and Qinghai. One-stop services cover pre-dispatch route surveys, long-distance cross-regional oversize permits, transport capacity matching for complex road conditions, and safety control for long-haul transport of lithium battery equipment, ensuring projects are commissioned on schedule.
Professional Inland Securing and Reinforcement
Multiple professional lashing and securing solutions tailored to cabinet structures and lithium battery module characteristics, effectively mitigating the risks of cabinet deformation, cell displacement, and precision component damage caused by vibration and tilting during long-haul transport.
IoT Full-Journey Visualized Safety Control
IoT-enabled visual monitoring throughout the journey, capturing real-time vehicle positioning, transport shock and vibration, and ambient temperature and humidity data, enabling full online visual control with early warnings of transport risks.
(2) Ocean Shipping Services
Hazardous Goods Warehousing and Yards at Core Ports
Dedicated dangerous goods warehousing and container yards at major outbound ports, including Shanghai, Taicang, Ningbo, and Xiamen, providing temporary storage and port consolidation services for energy storage cabinets.
Dangerous Goods Shipping Booking
Cooperative booking arrangements with shipping lines for dangerous goods, coordinating hazardous cargo capacity and supporting multiple shipping modes, including container vessels, breakbulk vessels, and heavy-lift vessels.
Export Compliance Declaration Services
A professional declaration team precisely handles document review, maritime filing and declaration, and customs clearance procedures, ensuring compliant entry of energy storage cabinets to ports.
Efficient Port Consolidation Operations
Coordinated scheduling of dangerous goods vehicles for port consolidation and direct truck-to-vessel loading.
(3) Overseas Last-Mile Delivery Services
Overseas On-Site Route Surveys
Conducting on-site surveys of overseas transport routes before project commencement to plan optimal delivery paths in advance, avoiding overseas road weight, height, and access restrictions and ensuring smooth door-to-door delivery.
Destination Port Lifting Solutions
Pre-matching lifting equipment capacity and safety regulations at destination ports, with customized lifting operation plans that avoid demurrage and cabinet damage caused by mismatched or insufficient lifting equipment.
Destination Port Clearance and Distribution
Leveraging Sinotrans Limited's overseas self-operated network and local partner resources to provide one-stop destination port customs clearance, discharge and transfer, and last-mile delivery services, covering the world's core energy storage export markets.
Cross-Border Regulatory Adaptation Support
Assisting customers in mapping destination-country certification requirements, with full compliance support from domestic transport through to overseas delivery.
(4) Value-Added Services
Insurance Coverage
Comprehensive cargo risk coverage across road transport, ocean shipping, port lifting, and yard storage, safeguarding energy storage equipment throughout the entire journey.
Green Logistics
Product carbon footprint calculation, import/export compliance consulting, and low-carbon logistics services, aligned with the green, low-carbon direction of the energy storage industry.
As domestic wind-solar-plus-storage projects are rolled out at an accelerating pace and new energy enterprises quicken their global expansion, demand for long-distance domestic transport and global bulk shipping of energy storage equipment will continue to grow. Leveraging its nationwide network, practical experience on high-difficulty routes, compliant qualified transport capacity, and global service network, Sinotrans is committed to deep collaboration and complementary synergy with energy storage enterprises, continuously delivering safe, efficient, and stable end-to-end energy storage supply chain solutions, jointly ensuring the efficient delivery of energy storage projects at home and abroad, and supporting China's new energy industry in maintaining its global leadership.
Sign up for our free monthly newsletter to stay informed about the Chinese energy storage market.